RRT Logo
  • HOME
  • ABOUT US
  • PROPERTIES FOR SALE
  • SELL YOUR HOME
  • SEARCH BY LOCATION
    • Cape Coral
    • Fort Myers
    • Fort Myers Beach
    • North Fort Myers
    • Lehigh Acres
    • Sanibel
    • Alva
    • Labelle
    • Estero
    • Matlacha
  • (239) 242-2000
CONTACT US
RRT Logo
RRT Logo
  • HOME
  • ABOUT US
  • PROPERTIES FOR SALE
  • SELL YOUR HOME
  • SEARCH BY LOCATION
    • Cape Coral
    • Fort Myers
    • Fort Myers Beach
    • North Fort Myers
    • Lehigh Acres
    • Sanibel
    • Alva
    • Labelle
    • Estero
    • Matlacha
  • (239) 242-2000
CONTACT US
RRT Logo
  • HOME
  • ABOUT US
  • PROPERTIES FOR SALE
  • SELL YOUR HOME
  • SEARCH BY LOCATION
    • Cape Coral
    • Fort Myers
    • Fort Myers Beach
    • North Fort Myers
    • Lehigh Acres
    • Sanibel
    • Alva
    • Labelle
    • Estero
    • Matlacha
  • (239) 242-2000
CONTACT US
Author: Penny
HomeArticles Posted by Penny
rNR6H1lPJa8-740×480-1-740×480
Uncategorized
September 15, 2026by Penny

Hyper-Local Cape Coral & Fort Myers Real Estate Insights

Daily market read for Monday, September 14, 2026

The Cape Coral and Fort Myers real estate markets are active, but buyers and sellers are not experiencing the same conditions everywhere. Neighborhood, property type, waterfront access, insurance costs, HOA fees, and overall condition are having more influence than broad citywide averages.

The latest local figures available as of September 12 place Cape Coral’s median sale price near $349,900, with homes spending approximately 99 days on the market. Fort Myers is showing a median sale price near $325,000, with marketing times close to 100 days.

Those numbers are useful starting points, but they do not tell the full story. A direct Gulf-access home in Cape Coral, a downtown Fort Myers condominium, a home in the Yacht Club area, and a property in an inland subdivision may all be responding to different buyer demand.

Southwest Florida market conditions this month

The latest regional data points to a market that is stabilizing rather than surging.

The FGCU Regional Economic Research Institute reported improving sales activity across the three-county coastal region, with approximately:

  • 14% year-over-year growth in single-family home sales
  • 17% year-over-year growth in condominium sales
  • A 4% decline in the real median single-family sale price
  • An 8% decline in the real median condominium sale price
  • A Lee County Housing Affordability Index near 1.35 for all residential properties
  • A real median rent decline of approximately 9% year over year

In practical terms, more transactions are taking place, but buyers remain selective. Sellers are no longer able to rely on limited competition or rapid price appreciation to support an ambitious asking price.

Mortgage rates are also keeping buyers focused on the complete cost of ownership. Freddie Mac’s weekly mortgage survey reported a 30-year fixed average near 6.76% for the week ending September 10, 2026. Insurance, property taxes, flood coverage, HOA fees, and maintenance can significantly change the monthly payment beyond principal and interest.

Cape Coral market update 2026: waterfront access is the dividing line

Cape Coral remains one of the most varied real estate markets in Southwest Florida. Citywide statistics combine several very different categories, including inland homes, freshwater canal properties, bridge-restricted Gulf-access homes, and direct sailboat-access residences.

Freshwater canal homes

Freshwater canal properties continue to appeal to buyers who want water views, a dock, kayaking, fishing, or an attractive outdoor setting without paying the full premium associated with direct Gulf access.

However, buyers should verify the canal’s width, depth, seawall condition, dock configuration, and connection to the broader canal system. “Waterfront” does not automatically mean that a property offers practical boating access to the Gulf.

Gulf access with bridges

Some Cape Coral homes provide saltwater access but require travel beneath one or more bridges. This may work well for buyers using smaller boats, pontoons, or other vessels that fit within the available clearance.

When comparing two homes advertised as Gulf access, ask:

  • How many bridges are along the route?
  • What are the bridge clearances?
  • Is the route navigable at typical tide levels?
  • How long is the trip to open water?
  • Are there locks, canals, or other restrictions?
  • What are the current conditions of the seawall, dock, and lift?

Direct Gulf and sailboat access

Direct Gulf-access and sailboat-access homes typically command the highest waterfront premiums because they offer a more convenient route to open water and may accommodate larger vessels.

Current broad pricing ranges reported for Cape Coral include approximately:

Property category General pricing range
Freshwater canal homes Mid-$400,000s and up
Gulf access with bridge restrictions Approximately $600,000–$650,000
Direct Gulf or sailboat access Approximately $700,000–$755,000 and up
Premium riverfront or extensively upgraded homes $1 million or more

These figures are not appraisals. A home’s value can change substantially based on renovation quality, canal exposure, bridge clearance, seawall age, dock and lift condition, flood zone, insurance availability, and distance to the Caloosahatchee River.

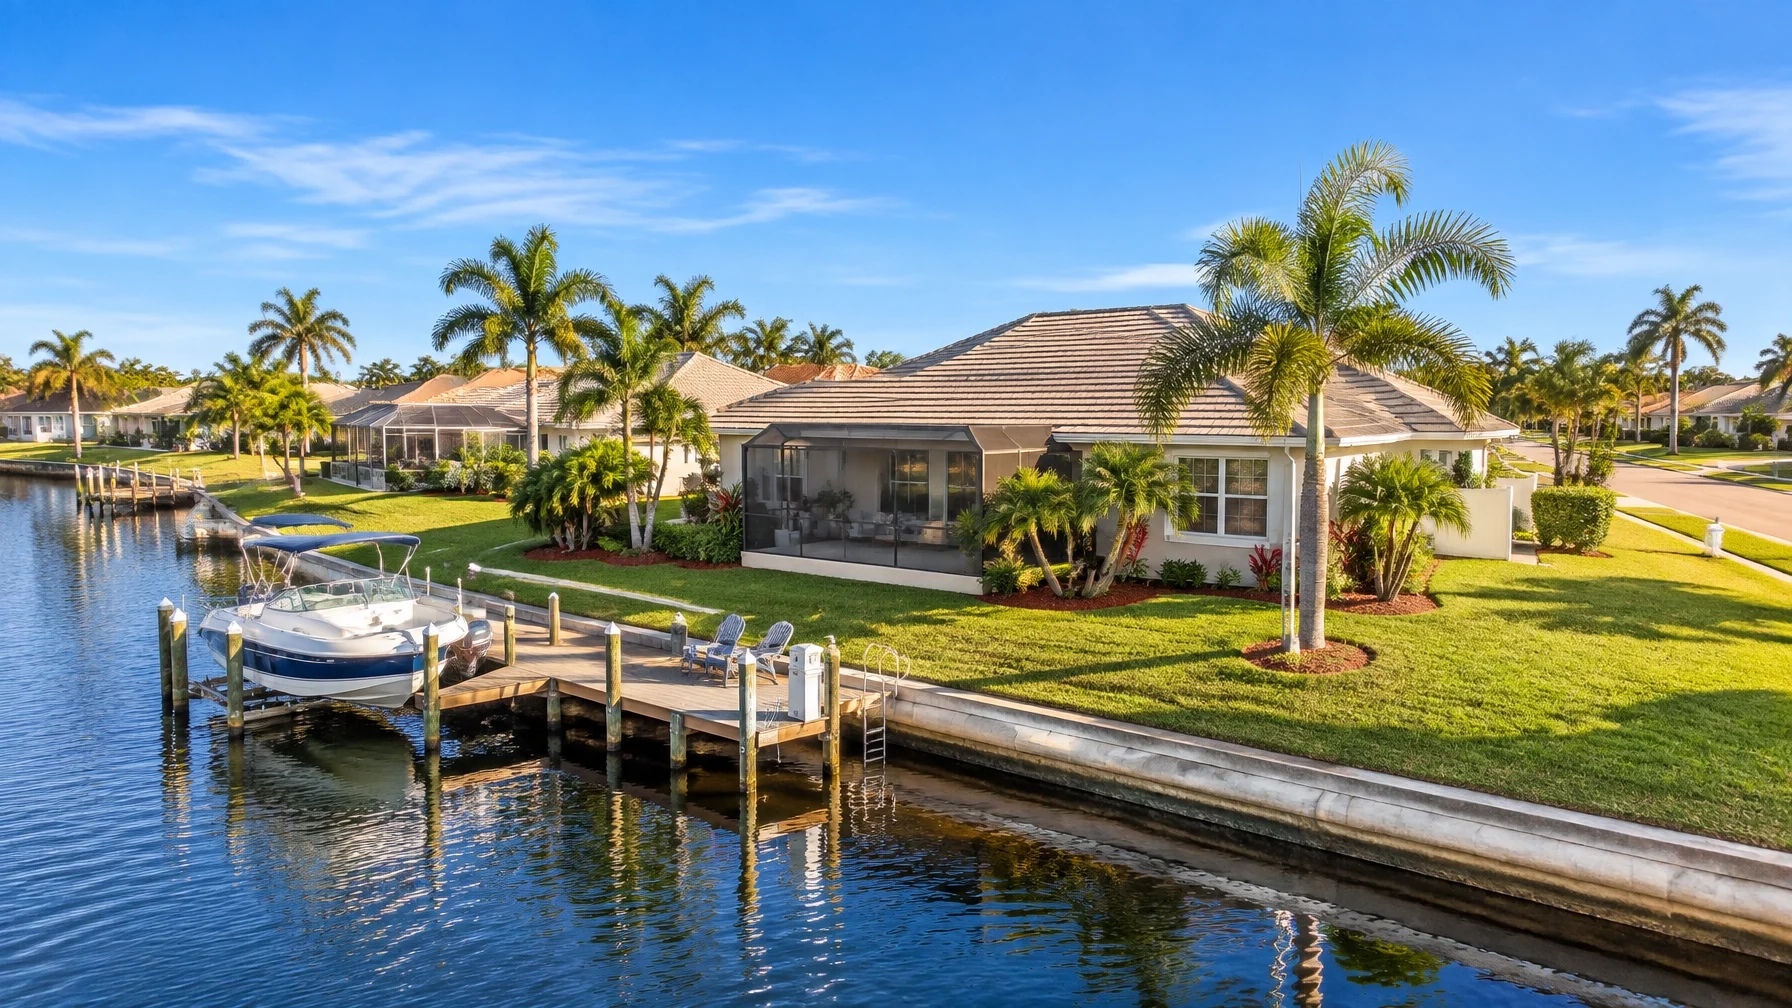
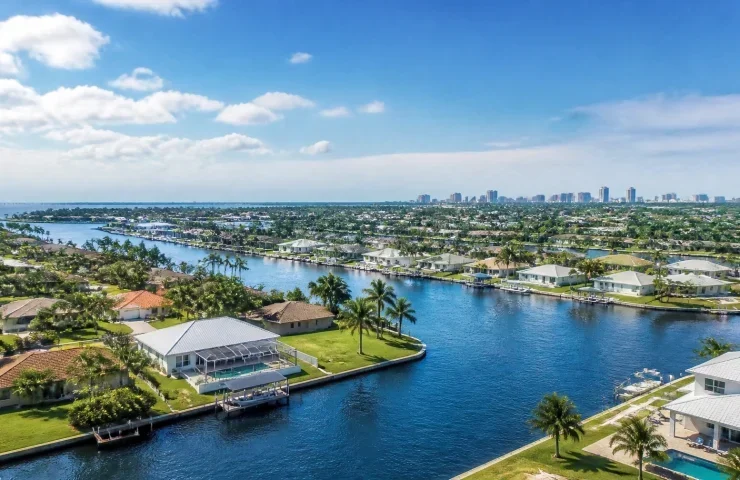
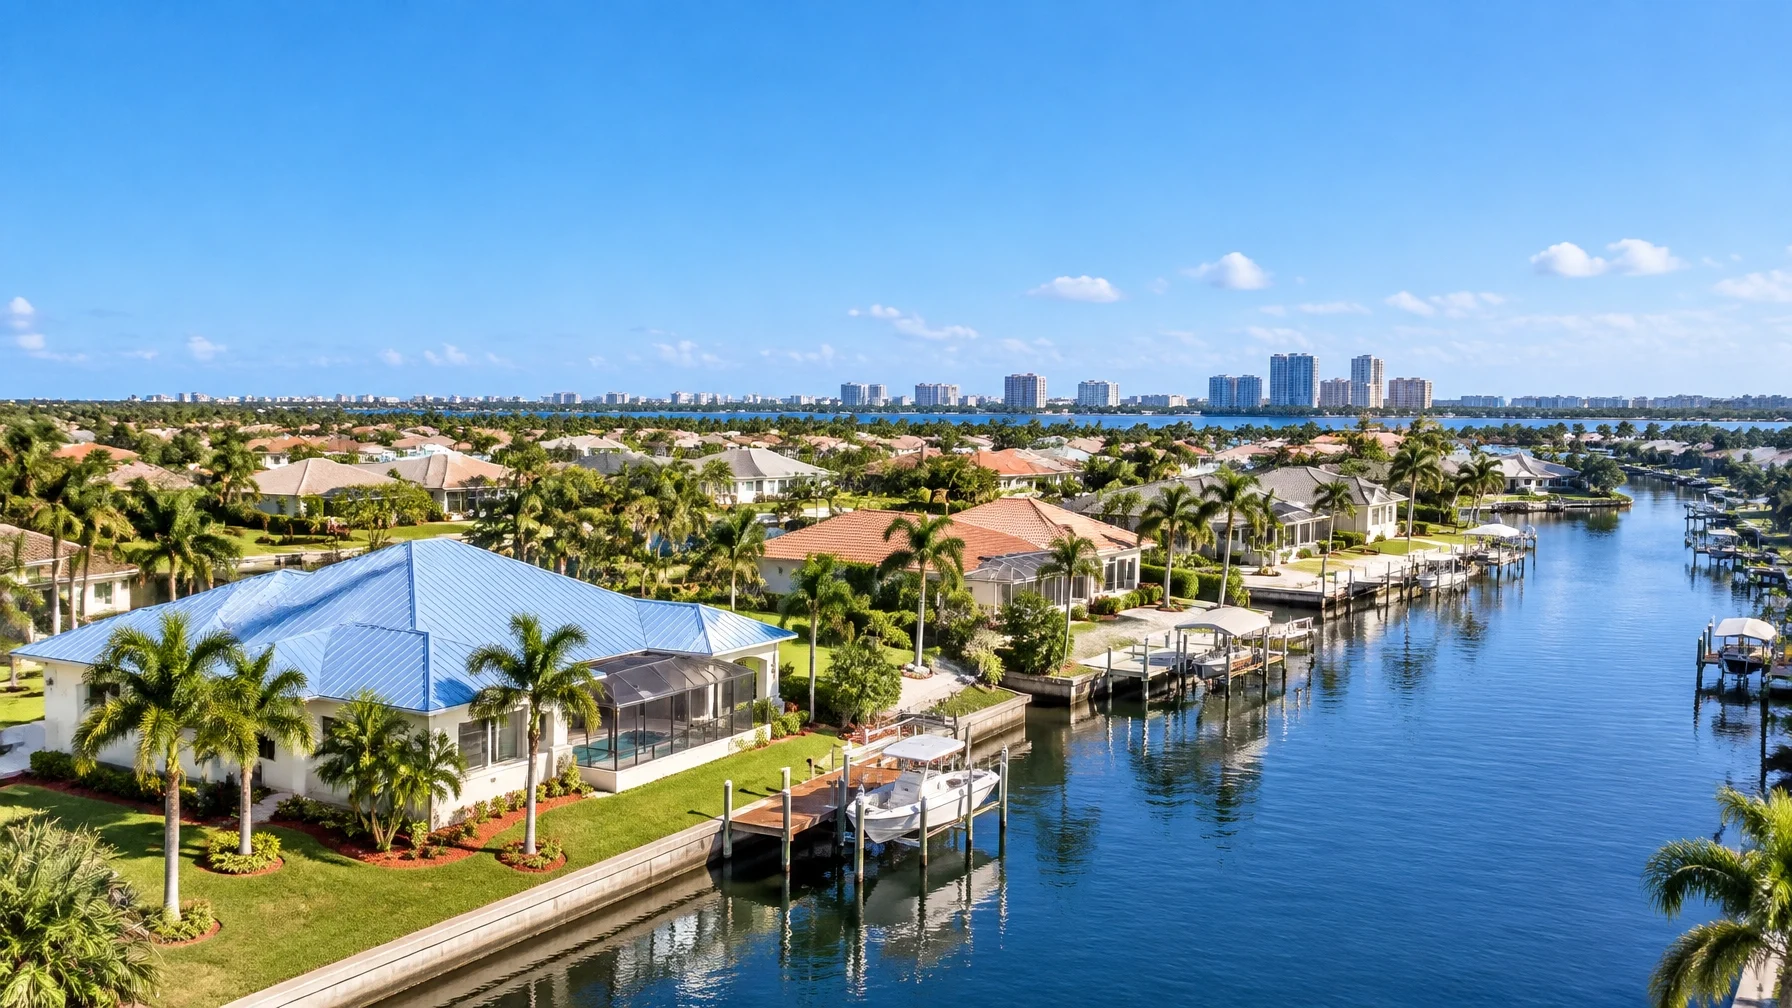
Cape Coral canal-front home with dock and boat access

Cape Coral neighborhoods to watch

Yacht Club area

The Yacht Club area and surrounding 33904 properties continue to attract buyers who value established neighborhoods, river access, and proximity to Cape Coral amenities.

At the same time, many homes in the area are older. Buyers are paying close attention to roofs, electrical systems, storm history, permits, seawalls, flood insurance, and the quality of renovations.

A renovated direct-access home may draw strong interest, while an older property requiring significant work needs to be priced according to its actual condition: not simply its waterfront location.

Cape Harbour

Cape Harbour remains a distinct lifestyle destination, with marina amenities, waterfront dining, and a more defined community atmosphere. Recent neighborhood-level reporting placed the median list price near $509,000, although individual properties vary considerably.

Buyers should evaluate the specific view, building, association fees, rental restrictions, dock rights, and relationship to the marina. Investors should also test projected rental income against management costs, insurance, vacancy, and association rules.

Pelican

Pelican includes a mix of inland, canal-front, and Gulf-access homes. Recent reporting placed the neighborhood’s median near $535,000, but that figure covers a wide range of properties.

The most relevant comparable sale for a Gulf-access home is usually another Gulf-access home with a similar boating route: not simply any property within the same ZIP code.

Fort Myers real estate trends: a segmented market

Fort Myers offers a different mix of housing from Cape Coral. Buyers can choose among established single-family neighborhoods, downtown condominiums, gated communities, golf properties, townhomes, and newer developments near major roads and employment centers.

Recent local reporting places Fort Myers single-family median sale prices in the general $430,000–$445,000 range for certain tracked segments, with approximately 4.3 to 4.5 months of supply. Broader citywide statistics, which include more property types and geographic areas, show a median closer to $325,000 and marketing times around 100 days.

This difference demonstrates why buyers should avoid relying on one statistic without checking the property category behind it.

Downtown Fort Myers and riverfront condominiums

Downtown Fort Myers attracts buyers who value restaurants, cultural events, historic character, river views, and a more walkable lifestyle.

Condominiums may offer a lower entry price than waterfront single-family homes, but the monthly ownership cost can vary significantly. Before purchasing, review:

  • Association reserves and financial statements
  • Current or planned special assessments
  • Master insurance and individual unit coverage
  • Roof and building maintenance responsibilities
  • Rental and pet restrictions
  • Flood exposure and deductibles
  • Parking and storage arrangements

The reported decline in real median condo prices may create opportunities, but a lower purchase price does not necessarily mean a lower total cost.

Established Fort Myers neighborhood with mature landscaping and well-maintained homes

Golf and gated communities

Golf communities continue to attract seasonal residents, retirees, and buyers looking for organized amenities. However, costs vary widely between communities.

Buyers should investigate mandatory or optional memberships, club dues, food and beverage minimums, HOA fees, capital reserves, rental restrictions, and future assessment risk. A home with a lower asking price may still have a high monthly carrying cost.

What buyers should do now

The current market gives buyers more time to compare properties than they had during the peak years. That does not mean every home is easy to negotiate. Well-priced, move-in-ready properties with manageable insurance profiles can still attract serious attention.

Buyers should:

  1. Obtain a current preapproval before making offers.
  2. Compare recent closed sales, not just active listings.
  3. Request insurance estimates early.
  4. Review roof age, permits, storm repairs, and major systems.
  5. Investigate seawalls, docks, lifts, and boating routes on waterfront properties.
  6. Review HOA or condominium documents during the due diligence period.
  7. Calculate the full monthly cost, including taxes, insurance, fees, and maintenance.
  8. Pay attention to cumulative days on market and repeated price reductions.

For buyers relocating from another state or country, local conditions can be especially difficult to evaluate remotely. A property may look attractive online while presenting very different insurance, flood, maintenance, or rental considerations in person.

Home-buying due diligence with keys, inspection materials, and insurance documents

What sellers and investors should watch

Sellers

Today’s buyers have alternatives, and pricing based on a neighbor’s optimistic list price can lead to extended market time.

Sellers should price against recent comparable sales in the same neighborhood and property category. Waterfront sellers should clearly explain the access route, bridge clearance, seawall condition, dock, lift, and insurance profile. A listing described only as “waterfront” may leave buyers with unanswered questions.

High-impact repairs, complete documentation, strong photography, and realistic pricing can help a property stand out.

Investors

Investors should underwrite conservatively. With Lee County rents reportedly down approximately 9% year over year and mortgage rates near 7%, projected returns should not depend on aggressive rent growth or immediate appreciation.

A complete analysis should include:

  • Realistic rent and vacancy
  • Insurance and flood coverage
  • Property management
  • Taxes and HOA fees
  • Repairs and capital reserves
  • Pool, seawall, dock, or lift maintenance
  • Financing costs
  • Rental restrictions
  • Resale liquidity

A less expensive condominium may offer a lower entry point, but association assessments or rental rules can affect returns. A waterfront home may have strong lifestyle and rental appeal, but its maintenance and insurance costs must be modeled carefully.

The September 14 takeaway

The Cape Coral and Fort Myers market is active, but selective. Sales are improving across Southwest Florida, while real prices remain softer than a year ago. Inventory has tightened in some segments, but buyers still have negotiating room when a property is overpriced, outdated, or burdened by high insurance and association costs.

Cape Coral buyers should distinguish carefully between freshwater canals, bridge-restricted Gulf access, and direct sailboat access. Fort Myers buyers should separate single-family homes from condominiums and evaluate the complete cost of ownership.

Whether you are researching cape coral real estate agents, comparing realtors cape coral buyers and sellers can work with, or tracking the latest Fort Myers real estate trends, the most useful market information is specific to the property and neighborhood.

You can search available Southwest Florida properties, learn more about RE/MAX Realty Team, or contact the office for property-specific guidance throughout Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding communities.

RE/MAX Realty Team office serving Cape Coral and Southwest Florida

Market figures are approximate and may vary by source, reporting period, property type, and geographic boundary. This article is for general informational purposes only and is not an appraisal, insurance quote, lending decision, or substitute for individualized real estate, legal, tax, insurance, or financial advice.
Read More
92VFnQSTNEJ
Uncategorized
September 14, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Daily market read for Sunday, September 13, 2026

Today’s Southwest Florida market conversation is less about broad headlines and more about the costs and characteristics that determine whether a specific property makes sense.

For buyers, insurance availability and waterfront access can change the monthly budget and long-term value of a home. For sellers, accurate pricing and clear property details are increasingly important. For investors, declining rents mean that conservative underwriting is essential.

Here is the latest hyper-local read for Cape Coral and Fort Myers.

Florida’s insurance market is showing signs of stabilization

Florida’s property insurance market remains an important part of every real estate decision, but conditions are improving compared with the uncertainty of recent years.

More than 17 private insurance carriers have re-entered or newly entered the Florida market, giving homeowners and buyers more options than they had during the tightest part of the insurance crisis. The Florida Office of Insurance Regulation has reported continued growth in the number of companies writing residential property policies.

Citizens Property Insurance has also approved an average rate reduction of approximately 8.7% for many policyholders in 2026. The exact change depends on the policy type, location, coverage, and individual risk profile, but the broader direction is positive.

You can review updates from the Florida Office of Insurance Regulation and Citizens’ rate information through Citizens Property Insurance.

Older roofs still require extra attention

A more stable insurance market does not mean every home is equally easy to insure.

Older homes, particularly those with aging roofs, may still face more detailed underwriting questions, inspection requirements, coverage limitations, or higher premiums. Buyers should not assume that a property is insurable simply because it is currently occupied or has an existing policy.

Before making an offer, ask for:

  • The roof’s installation date and permitting records
  • Recent four-point or roof inspections
  • Wind mitigation documentation
  • Information about prior claims
  • Current insurance declarations, when available
  • Estimates for replacement cost and wind coverage

Carriers are increasingly willing to consider older roofs when their condition and construction can be documented. However, roof age remains a major factor in both insurability and negotiations.

Wind mitigation inspections can deliver meaningful savings

A wind mitigation inspection is often one of the most cost-effective steps a Florida homeowner can take to reduce insurance costs. The inspection documents features such as:

  • Roof shape and construction
  • Roof-to-wall connections
  • Roof deck attachment
  • Secondary water resistance
  • Hurricane-resistant windows and doors
  • Shutters and garage-door protection

Depending on the home and carrier, qualifying features may generate significant credits on the wind portion of the policy. Buyers should ask whether a current inspection is available, while sellers may benefit from completing one before listing.

A relatively modest inspection cost can make a home easier to evaluate, improve buyer confidence, and potentially reduce the total insurance premium.

Southwest Florida home inspection focused on roof and hurricane-readiness features

Cape Coral waterfront pricing depends on the access tier

Cape Coral waterfront properties are not one uniform category. A freshwater canal, a Gulf-access canal with bridges, and direct Gulf access can attract different buyers and command very different prices.

Based on July–August 2026 market data, approximate median prices are:

Waterfront category Approximate median price
Freshwater canal $465,000
Gulf access with bridges $615,000
Direct Gulf access, no bridges $692,500

These figures help explain why a simple “waterfront” label is not enough when comparing Cape Coral homes.

Freshwater canal homes

Freshwater canal properties often appeal to buyers who want a water view, private dock, kayaking, fishing, or a larger outdoor setting without paying the full premium for Gulf access.

The key questions are usability and condition. Buyers should confirm the canal’s width and depth, the condition of the seawall, dock, and boat lift, and whether the waterway connects to other canals or recreational areas.

Freshwater access may offer excellent lifestyle value, but it should not be priced like a direct Gulf-access property.

Gulf access with bridges

Gulf-access homes with bridges can provide a boating lifestyle while remaining more affordable than direct-access properties. However, the route to open water may be affected by bridge clearance, tides, canal conditions, and the size of the buyer’s boat.

During due diligence, buyers should ask:

  • How many bridges are on the route to open water?
  • What are the bridge clearances?
  • Is the route navigable at typical tide levels?
  • How long is the trip to the river or Gulf?
  • Are there locks, restrictions, or maintenance concerns?

The answers can affect both enjoyment and resale appeal.

Direct Gulf access

Direct Gulf-access properties, particularly those with no bridges between the home and open water, generally command the highest waterfront premium. They may be especially attractive to boaters who want faster access and fewer route limitations.

That premium should still be evaluated against the full ownership picture. Seawalls, docks, boat lifts, electrical systems, flood exposure, storm damage history, and insurance costs can materially affect the value of a waterfront property.

Cape Coral waterfront inventory is down year over year, with approximately 4.9 months of supply in this segment. That is roughly balanced rather than extremely tight. Well-priced, move-in-ready homes can sell efficiently, while properties with aging marine infrastructure or unrealistic list prices may give buyers meaningful negotiating leverage.

Cape Coral canal-front home with private dock and boat lift

Overall inventory still gives buyers room to negotiate

Cape Coral’s overall market has approximately 7 to 8 months of supply, which favors buyers. The waterfront segment is tighter than the broader citywide market, but buyers still have options and time to compare condition, access, insurance, and price.

Current citywide benchmarks remain approximately:

  • Cape Coral: $349,900 median sale price and about 99 days on market
  • Fort Myers: $325,000 median sale price and about 100 days on market

These are broad figures. A renovated home with a newer roof, manageable insurance, and a desirable location may perform very differently from an outdated property with deferred maintenance.

For buyers, longer marketing periods create opportunities to negotiate repairs, credits, price adjustments, or favorable terms. For sellers, the message is straightforward: accurate pricing and preparation matter more than simply testing the highest possible list price.

Lee County investors should underwrite conservatively

Lee County rents have declined, making it more important for investors to use realistic income assumptions. A property that appeared attractive when rents were rising may produce a very different return today.

Investors should stress-test each purchase using:

  • Conservative market rent
  • Vacancy and turnover
  • Property management
  • Insurance increases
  • Property taxes
  • Repairs and maintenance
  • HOA or condominium fees
  • Flood coverage, when applicable
  • Financing costs
  • Future capital expenditures

For a Cape Coral waterfront rental, that analysis should also include seawall, dock, lift, pool, and exterior maintenance. For a Fort Myers condominium, association reserves, master insurance, assessments, rental rules, and building condition deserve close review.

The best investment is not necessarily the property with the lowest purchase price. It is the property whose income, expenses, tenant demand, and resale prospects remain reasonable under conservative assumptions.

Well-maintained Cape Coral rental home with tropical landscaping in bright natural light

Practical guidance for today’s market

For buyers

Get an insurance estimate before making an offer, especially for older homes, waterfront properties, and homes with aging roofs. Verify the exact type of water access rather than relying on listing language. Review seawalls, docks, lifts, flood exposure, and permitting during due diligence.

For sellers

Gather roof records, wind mitigation reports, permits, insurance information, and marine-infrastructure documentation before listing. Price the property against comparable homes with similar access and condition. Clear information can reduce buyer uncertainty and help prevent renegotiation later.

For investors

Use current rents rather than optimistic projections. Include vacancy, insurance, maintenance, management, and capital expenses in the first version of your analysis: not as an afterthought. If the deal only works with perfect occupancy or aggressive rent growth, it may not be sufficiently durable.

Search Southwest Florida properties with local guidance

RE/MAX Realty Team serves buyers, sellers, renters, and investors throughout Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding communities.

  • Search SWFL properties
  • Learn more about RE/MAX Realty Team
  • Contact our office

Summary and takeaway

The September 13, 2026 market is being shaped by property-level details.

Florida’s insurance landscape is stabilizing, with more private carriers returning, an approximately 8.7% Citizens rate reduction, and increased attention to wind mitigation. Older roofs still require careful review, but documented condition and storm-resistant features can improve a home’s insurance profile.

In Cape Coral, waterfront value depends heavily on access: approximately $465,000 for freshwater canal homes, $615,000 for Gulf access with bridges, and $692,500 for direct Gulf access. Inventory is tighter in the waterfront category, but buyers retain leverage when marine infrastructure is aging or pricing is unrealistic.

Across Cape Coral and Fort Myers, longer marketing periods give buyers room to compare and negotiate. Investors should remain cautious because Lee County rents have declined.

The best real estate decisions today come from evaluating the complete ownership picture: price, insurance, condition, access, monthly costs, and long-term usability.

Data disclaimer: All figures in this article are approximate and may vary by source, property type, geographic boundary, and reporting period. Cape Coral waterfront figures reflect July–August 2026 market data, while citywide prices, days on market, inventory, insurance conditions, and rent trends reflect the latest available information as of September 13, 2026. This article is for general informational purposes only and is not financial, legal, tax, insurance, or investment advice. Consult qualified professionals before making a real estate decision.

Read More
R2clqscSl2j
Uncategorized
September 12, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Daily market read for Saturday, September 12, 2026

Southwest Florida’s housing market is becoming more active, but the recovery is not uniform across every city, neighborhood, or property type. Buyers are returning, sellers are adjusting expectations, and the details of a property: water access, insurance, HOA fees, condition, and location: matter more than a broad regional headline.

For today’s hyper-local read, Cape Coral’s median home sale price is approximately $349,900, with homes spending about 99 days on the market. Fort Myers is showing a median sale price near $325,000, with approximately 100 days on the market.

Those figures provide useful context, but they do not tell the whole story. A freshwater canal home in Cape Coral, a direct Gulf-access property, a downtown Fort Myers condominium, and a home in a golf community may all respond to different market forces.

The broader Southwest Florida market

The latest regional benchmark comes from the FGCU Regional Economic Research Institute’s Third Quarter 2026 Real Estate Report, published September 8 and based primarily on second-quarter data.

The report shows a market with improving sales activity but softer real prices:

  • Single-family home sales increased 14% year over year, reaching approximately 5,600 sales across the three-county coastal region.
  • Condominium sales increased 17%, reaching approximately 1,320 sales.
  • Real median single-family prices declined about 4% year over year.
  • Real median condominium prices declined about 8% year over year.
  • Lee County’s Housing Affordability Index was approximately 1.35 for all residential properties and 1.30 for single-family homes.
  • Real median rents in Lee County declined approximately 9% year over year.

An affordability index above 1.0 generally indicates that the benchmark household has enough income to qualify for the typical home under the report’s assumptions. However, the actual monthly cost of ownership still depends on mortgage terms, insurance, taxes, flood coverage, HOA or condominium fees, and maintenance.

The overall message is not that the market is collapsing. It is that Southwest Florida is moving through a reset: more transactions are taking place, while buyers remain selective and inflation-adjusted prices are softer than they were a year ago.

Cape Coral: the waterfront category matters

Cape Coral’s approximately $349,900 median sale price and 99-day marketing period suggest a market where buyers have time to compare options. But Cape Coral is not one single market. Waterfront access can create substantial differences in value, usability, insurance, and buyer demand.

Waterfront homes and canal access in Cape Coral

Freshwater canals

Freshwater canal homes are often attractive to buyers who want water views, a dock, kayaking, fishing, or a more open backyard setting without paying the premium associated with Gulf access.

These properties can offer a compelling lifestyle value, but buyers should understand that freshwater canal access is not the same as navigable access to the Gulf. The canal’s width, depth, seawall condition, and connection to the broader canal system all deserve review.

Gulf access with bridges

Some Cape Coral homes offer saltwater or Gulf access but require travel beneath bridges. This can be perfectly suitable for many boaters, particularly those using smaller vessels. However, bridge height and timing can affect the type of boat that can reach the property and how easily an owner can access open water.

When comparing two homes that are both advertised as “Gulf access,” buyers should ask:

  • How many bridges are between the property and open water?
  • What are the bridge clearances?
  • Is the route navigable at typical tide levels?
  • How long does the boat trip take?
  • Are there restrictions related to canals, locks, or neighboring structures?

Direct Gulf access

Direct Gulf-access properties, including some sailboat-access locations, often command a premium because they reduce travel time and may accommodate larger boats. But the premium should be evaluated against the entire ownership profile.

Buyers should examine the dock, seawall, lift, electrical systems, storm exposure, flood zone, elevation, and insurance availability. A waterfront feature can increase enjoyment and resale appeal, but it can also add significant maintenance and replacement costs.

Cape Coral’s current market rewards buyers who distinguish between these waterfront tiers rather than relying on a listing description alone. Sellers, meanwhile, need to explain the access clearly and price the property according to comparable homes with similar boating characteristics.

Fort Myers: single-family homes and condos are different markets

Fort Myers’ median sale price near $325,000, combined with approximately 100 days on market, reflects a diverse housing landscape. The city includes established single-family neighborhoods, townhomes, condominium communities, gated developments, golf properties, and homes near downtown, medical services, shopping, and employment centers.

The most important distinction is often between single-family homes and condominiums.

Single-family buyers typically focus on lot size, roof age, storm protection, renovation needs, insurance, and proximity to services. In Fort Myers, a modest home in an established neighborhood can appeal to a full-time resident, retiree, or investor seeking fewer community restrictions.

Condominium buyers must look beyond the purchase price. Monthly association fees, reserves, building maintenance, master insurance, assessments, rental rules, pet policies, and approval procedures can materially change the total cost of ownership. The FGCU report’s approximately 8% year-over-year decline in real median condo prices may create opportunities, but buyers should complete careful association-level due diligence.

Established Fort Myers neighborhood with single-family and condominium homes

Neighborhood-level differences to watch

Yacht Club area

The Yacht Club area is appealing to buyers who value proximity to the Caloosahatchee River, waterfront recreation, and established Fort Myers amenities. Properties near the river may receive additional buyer interest, but flood exposure, insurance, seawall condition, and storm-related improvements should be evaluated carefully.

The neighborhood’s location can support lifestyle appeal, yet buyers should compare the cost of ownership against nearby homes that may offer similar access without the same waterfront-related expenses.

Cape Harbour

Cape Harbour represents a distinct Cape Coral lifestyle, with marina-oriented amenities, waterfront dining, and a more defined destination feel than many residential canal areas. Condominiums, attached homes, and nearby single-family properties may attract buyers looking for boating access and walkable entertainment.

Values can vary considerably depending on the view, marina relationship, building, association fees, rental policies, and proximity to amenities. For investors, projected rental income should be tested against current rents, management costs, insurance, vacancy, and association rules.

Downtown Fort Myers

Downtown Fort Myers attracts buyers who prioritize restaurants, cultural events, historic character, and a more walkable environment. The housing mix includes condominiums, loft-style residences, historic homes, and nearby single-family properties.

Downtown properties may have a different resale audience from suburban homes. Some buyers are paying for lifestyle and location rather than a large yard or extensive square footage. Parking, building reserves, association fees, flood considerations, and rental restrictions are especially important when evaluating a downtown condominium.

Golf communities

Golf communities throughout Cape Coral and Fort Myers can appeal to seasonal residents, retirees, and buyers seeking organized amenities. However, golf ownership costs vary. Some communities have mandatory memberships, while others operate with optional or social memberships. HOA fees, club dues, capital reserves, course maintenance, and rental restrictions should be reviewed before making an offer.

A lower purchase price does not automatically mean a lower monthly cost. Buyers should compare the full carrying cost of a golf-community home with similar properties outside the community.

Mortgage rates remain part of the equation

Freddie Mac’s weekly mortgage data place average 30-year fixed mortgage rates near 6.7% to 6.8%. At those rates, even modest differences in purchase price, insurance, taxes, and HOA fees can have a meaningful effect on the monthly payment.

Buyers should obtain a current preapproval, compare loan programs, and ask lenders to estimate the full payment: not just principal and interest. It is also wise to request insurance estimates early, particularly for older homes, waterfront properties, condominiums, and homes with prior storm damage or aging roofs.

The right question is not simply, “Can I qualify for this home?” It is, “Does the complete monthly cost fit comfortably within my long-term plan?”

What today’s market means for buyers, sellers, and investors

Buyers

Use longer marketing times to compare properties and negotiate thoughtfully. Review recent closed sales from the same neighborhood and property type. In Cape Coral, compare waterfront access in detail. In Fort Myers, compare single-family homes with condos only after accounting for all recurring fees and maintenance responsibilities.

Sellers

Pricing must reflect current buyer behavior rather than past peak-market expectations. A well-presented home with accurate pricing, clear disclosures, and realistic insurance information can stand out. Properties that are overpriced or unclear about waterfront access, association costs, or condition may remain on the market considerably longer.

Investors

Lee County rents are down approximately 9% year over year, so investment projections should remain conservative. Underwrite using realistic rent, vacancy, insurance, maintenance, taxes, financing, and management costs. The best investment is not necessarily the least expensive property; it is the one with a sustainable relationship between purchase price, operating expenses, tenant demand, and resale potential.

RE/MAX Realty Team serves Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding Southwest Florida communities. Buyers, sellers, and investors can search available SWFL properties, learn more about the team, or contact RE/MAX Realty Team for property-specific guidance.

RE/MAX Realty Team office serving Southwest Florida

Summary and takeaway

The September 12, 2026 market is active but selective. Cape Coral’s median sale price is approximately $349,900, with homes taking about 99 days to sell. Fort Myers is near $325,000, with approximately 100 days on market. Regional sales are rising, real prices are softer, Lee County affordability has improved, and rents have declined.

Cape Coral buyers should focus closely on the difference between freshwater canals, Gulf access with bridges, and direct Gulf access. Fort Myers buyers should separate the single-family and condominium markets and review total ownership costs. Neighborhoods such as Yacht Club, Cape Harbour, downtown Fort Myers, and golf communities each bring their own pricing and lifestyle considerations.

The best decision will come from understanding the specific property, neighborhood, insurance profile, and financial plan: not from relying on one broad median.

Data disclaimer: Market conditions change frequently, and the figures in this article are approximate. Cape Coral and Fort Myers statistics may vary by source, property type, geographic boundary, and reporting period. The FGCU figures primarily reflect regional second-quarter 2026 data, while the local median prices and days-on-market estimates reflect the latest available market read as of September 12, 2026. This article is for general informational purposes and is not financial, legal, tax, insurance, or investment advice. Consult qualified professionals before making a real estate decision.

Read More
rNR6H1lPJa8-740×480
Uncategorized
September 11, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Daily market read for September 11, 2026

Southwest Florida’s real estate market is active, but it is not moving uniformly. Cape Coral waterfront homes, downtown Fort Myers condos, golf communities, and traditional single-family neighborhoods are each responding to different levels of inventory, pricing, insurance costs, and buyer demand.

The latest regional data points to a market that is stabilizing rather than surging. Sales are improving, inventory has tightened in several segments, and prices are generally softer than during the market’s peak. However, well-priced homes in desirable locations can still attract serious attention: especially when they offer strong condition, manageable insurance costs, and features buyers cannot easily replace.

Here is the hyper-local Cape Coral market update 2026 buyers, sellers, and investors need to know.

The Southwest Florida market at a glance

The latest available reports show a market with more transactions but less pricing power for sellers than in recent boom years.

According to the latest Realtor.com Cape Coral–Fort Myers market report, the combined market recorded:

  • A median list price near $380,000
  • Approximately 95 days on market
  • Median asking prices down roughly 6.2% year over year
  • Nearly one in five listings with a price reduction
  • Active listings down year over year, even as new listings edged higher

The FGCU Regional Economic Research Institute adds important context. In its latest regional report, single-family sales increased approximately 14% year over year, while the real median single-family price declined about 4%. Condo sales also increased, but median condo prices fell more sharply.

That combination: more sales alongside softer prices: suggests buyers are returning, but they remain selective and price-conscious.

Mortgage rates are still part of the equation. Freddie Mac reported a 30-year fixed average of 6.76% for the week ending September 10, 2026, up from 6.71% the previous week. At this rate, insurance, taxes, HOA fees, and flood coverage can materially change a buyer’s monthly payment.

Cape Coral: the citywide numbers do not tell the whole story

Cape Coral remains one of the most varied real estate markets in Southwest Florida. A home in northern Cape Coral without water access is competing in a very different market from a renovated sailboat-access property in the Yacht Club area or a newer home near Cape Harbour.

Current Cape Coral indicators show:

  • Median sale prices generally in the mid-$300,000s
  • Median list prices closer to the low-to-mid $400,000s
  • Typical market times around 85 to 100 days, depending on the data source and property type
  • Approximately 4.5 to 4.9 months of supply
  • Fewer listings than last year in several segments

The gap between list price and sold price is especially important. A property listed at $425,000 is not automatically worth $425,000. Buyers are comparing recent closed sales, insurance estimates, inspection findings, seawall condition, and total monthly ownership costs before making offers.

The strongest demand continues to center on properties with:

  • Newer roofs and updated major systems
  • Pools and usable outdoor living areas
  • Reasonable insurance profiles
  • Completed renovations with permits
  • Larger lots or attractive canal exposure
  • Convenient access to shopping, dining, schools, and major roads

Cape Coral canal homes and waterfront properties in bright natural light

Cape Coral waterfront: access matters more than the label

“Waterfront” is not one category in Cape Coral. The value of a canal home depends heavily on how the property connects to open water and what ownership costs come with that access.

Approximate current pricing tiers include:

Property type Approximate market range
Freshwater canal homes Mid-$400,000s and up
Gulf-access homes with bridge restrictions Approximately $600,000–$650,000
Direct Gulf or sailboat access Approximately $700,000–$755,000 and up
Premium riverfront or extensively upgraded properties $1 million or more

These are broad ranges, not appraisals. A canal’s width, bridge clearance, lock system, seawall age, dock, lift, boating route, and proximity to the Caloosahatchee River can significantly affect value.

Yacht Club area

The historic Yacht Club area and surrounding 33904 properties benefit from established neighborhoods and desirable access to the river and Gulf. However, many homes are older, and buyers are paying close attention to renovation quality, storm history, roofs, electrical systems, seawalls, and flood insurance.

A renovated direct-access home can command a substantial premium. An older property requiring major work may need a significant adjustment, even if the location is attractive.

Cape Harbour

Cape Harbour remains a premium lifestyle location because of its marina, waterfront setting, restaurants, and community atmosphere. Recent neighborhood-level listing data placed its median list price near $509,000, although individual properties vary widely.

Buyers should separate marina or lifestyle appeal from actual boating access. They should also verify rental rules, dock rights, association fees, and any restrictions affecting future use.

Pelican

Pelican includes a mix of off-water, canal-front, and Gulf-access homes. Recent listing data placed the neighborhood’s median near $535,000, but the range is broad. Updated Gulf-access homes can sit well above the neighborhood median, while inland properties may trade closer to the broader Cape Coral market.

For both buyers and sellers, the most relevant comparable sales are usually within the same waterfront tier: not simply within the same ZIP code.

Fort Myers: single-family homes and condos are moving differently

Fort Myers is more segmented than a citywide median suggests. The area includes downtown condos, established neighborhoods, gated golf communities, older single-family homes, townhomes, and newer construction near major roads and employment centers.

Recent local market reporting places Fort Myers single-family median sale prices roughly in the $430,000–$445,000 range, with approximately 4.3 to 4.5 months of supply. One local snapshot showed median days on market near 50 days for single-family homes, although broader Fort Myers and metro statistics are closer to 90–100 days depending on the reporting method.

Condos are generally more buyer-friendly. Median prices have been reported around $220,000–$233,000, with approximately 6.5 to 6.9 months of supply in some segments.

Established Fort Myers neighborhood with mature landscaping and well-maintained homes

Downtown Fort Myers and riverfront condos

Downtown Fort Myers attracts buyers who prioritize restaurants, entertainment, river views, walkability, and proximity to the historic river district. Condo pricing is often more accessible than waterfront single-family pricing, but monthly carrying costs can vary considerably.

Before purchasing a downtown or riverfront condo, review:

  • Association reserves and financial statements
  • Current and potential special assessments
  • Master insurance and individual unit coverage
  • Roof and building maintenance
  • Rental restrictions
  • Pet and occupancy rules
  • Flood exposure and deductibles
  • Parking and storage arrangements

A lower purchase price does not always mean a lower monthly cost. HOA fees, insurance, taxes, and assessments need to be included in the affordability calculation.

Golf and gated communities

Golf communities such as Heritage Palms and other established Fort Myers developments continue to appeal to seasonal residents, retirees, and lifestyle buyers. Buyers are comparing more than the home itself. They are also evaluating club fees, membership requirements, food and beverage minimums, rental rules, reserves, and future assessments.

Well-maintained homes with reasonable fees can attract attention. Properties with dated interiors, high monthly costs, or unclear association finances may require more time and sharper pricing.

What the current market means for buyers

Buyers have more negotiating room than they did during the fastest years of the market, but the best properties may still move quickly.

If you are shopping in Cape Coral or Fort Myers:

  1. Get fully pre-approved before making serious offers.
  2. Compare recent closed sales, not just active listings.
  3. Request insurance estimates early.
  4. Investigate roofs, permits, seawalls, docks, lifts, and storm repairs.
  5. Review HOA or condo documents before the inspection period expires.
  6. Calculate the complete monthly payment.
  7. Pay attention to cumulative days on market and repeated price reductions.

For waterfront buyers, ask specifically about travel time to open water, bridge height restrictions, seawall permits, flood insurance, and dock condition. For Fort Myers condo buyers, association finances may be just as important as the unit’s finishes.

Home-buying due diligence with keys, inspection materials, and insurance documents

What sellers should do now

Today’s buyers are informed and have alternatives. Pricing based on a neighbor’s ambitious asking price: or on a sale from several years ago: can lead to extended market time.

Sellers should:

  • Price against recent comparable sales in the same neighborhood and property type
  • Complete high-impact repairs before listing
  • Gather roof, permit, insurance, and renovation records
  • Present pools, outdoor areas, docks, and canal access clearly
  • Explain bridge clearance and boating routes
  • Review showing activity during the first two weeks
  • Be prepared to respond to market feedback

In waterfront neighborhoods, presentation must communicate the property’s practical advantages. “Waterfront” is not enough. Buyers want to know whether the access is useful, whether the seawall is sound, and whether the insurance profile is manageable.

What investors should watch

Investors should underwrite Cape Coral and Fort Myers properties conservatively. Lee County rents have declined approximately 9% year over year in recent regional reporting, while mortgage rates remain near 7%.

A complete investment analysis should include:

  • Realistic rent and vacancy
  • Property management
  • Insurance and flood coverage
  • Property taxes
  • HOA or condo fees
  • Repairs and capital reserves
  • Pool, seawall, dock, or lift maintenance
  • Financing costs
  • Rental restrictions
  • Resale liquidity

A lower-priced condo may offer an attractive entry point, but association restrictions or assessments can affect returns. A waterfront home may have strong rental and lifestyle appeal, but seawall, storm, insurance, and maintenance expenses must be modeled carefully.

The September 11 takeaway

The Cape Coral and Fort Myers market is active, but selective. Regional sales are improving, inventory has tightened in important segments, and prices are generally stabilizing after a period of correction. At the same time, buyers still have time to investigate properties and negotiate: particularly when a home is overpriced, outdated, or burdened by high insurance and association costs.

Cape Coral offers the greatest range of waterfront possibilities, from freshwater canals to direct Gulf access. Fort Myers provides a broader mix of established neighborhoods, golf communities, downtown condos, and single-family homes near employment and amenities.

The most important lesson is simple: the citywide median is only the starting point. Neighborhood, access, property condition, insurance, HOA costs, and financing will determine the real opportunity.

Whether you are comparing Cape Coral real estate agents, searching for experienced Realtors Cape Coral buyers and sellers can rely on, or evaluating current Fort Myers real estate trends, local guidance matters. Search available Southwest Florida properties, learn more about RE/MAX Realty Team, or contact our office for help with your next move.

RE/MAX Realty Team office in Cape Coral

Market figures are approximate and may vary by source, reporting period, property type, and geographic boundaries. This article is for general informational purposes only and is not an appraisal, insurance quote, lending decision, or substitute for individualized real estate, legal, tax, insurance, or financial advice.

Read More
lQH58gFo8OT-740×480-1-740×480-2-740×480-1-740×480
Uncategorized
September 11, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Weekly market pulse for Friday, September 11, 2026

Southwest Florida’s housing market is giving buyers more room to evaluate their options, while well-positioned homes still attract serious attention. Sales activity is improving, prices have softened from recent highs, and the cost of borrowing remains an important part of every buyer’s decision.

Here is the latest hyper-local look at Cape Coral and Fort Myers real estate, including ZIP-level pricing, waterfront premiums, neighborhood comparisons, mortgage rates, and the upcoming Federal Reserve meeting.

Mortgage rates rose slightly this week

According to Freddie Mac’s Primary Mortgage Market Survey, the average 30-year fixed mortgage rate was 6.76% on September 10, 2026, up from 6.71% the previous week and 6.35% a year ago.

The average 15-year fixed rate was 6.09%, up from 6.04% last week and 5.50% a year ago. The 30-year fixed rate’s 52-week range is currently 5.98% to 6.76%.

The increase is modest, but affordability math still matters. On a $400,000 loan, the principal-and-interest payment at 6.76% is approximately $2,600 per month before taxes, insurance, HOA fees, and other costs. A small rate change may not determine whether a buyer qualifies, but it can affect the comfortable purchase price and monthly budget.

The practical approach is to compare multiple lenders, understand the full monthly payment, and avoid assuming rates will automatically fall after the next Federal Reserve meeting.

What to watch during the September FOMC meeting

The Federal Open Market Committee is scheduled to meet September 15–16, 2026.

Buyers should not assume that a Federal Reserve announcement will immediately produce lower mortgage rates. The Fed influences short-term interest-rate policy, while 30-year mortgage rates are also heavily affected by bond markets, inflation expectations, economic data, and investor demand.

Even if the FOMC changes policy, mortgage rates could move higher, lower, or remain relatively steady depending on how markets interpret the announcement. Sellers should also avoid pricing a home around an expected rate change. Current comparable sales, condition, location, insurance costs, and buyer demand remain more reliable pricing indicators.

Southwest Florida market direction: more sales, softer real prices

The FGCU Regional Economic Research Institute’s Third Quarter 2026 SWFL Real Estate Report, released September 8, provides important regional context from the second quarter.

Across Southwest Florida:

  • Single-family home sales increased 14% year over year to approximately 5,600.
  • Condominium sales rose 17% to approximately 1,320.
  • Real median single-family prices declined 4% compared with Q2 2025.
  • Real median condominium prices declined 8% year over year.
  • Lee County’s Housing Affordability Index was 1.35 for all residential properties and 1.30 for single-family homes.
  • Real median rents in Lee County declined approximately 9% year over year.

In simple terms, more properties are changing hands even as prices remain below prior peaks. That combination can create opportunities for buyers who are prepared, while sellers need realistic pricing and strong presentation.

Lee County’s July and August market context

Lee County recorded approximately 1,762 closed residential sales in July 2026. Single-family inventory was around 5.5 months, while condo and townhome supply was approximately 6.9 months.

The median time to contract was about:

  • 73 days for single-family homes
  • 112 days for condominiums

Homes sold for roughly 93% of asking price, depending on the report and whether the metric uses original or final list price. Approximately 22% of listings had experienced price reductions, reinforcing the importance of launch pricing and ongoing market feedback.

This is not a market where every property sells immediately. However, it is also not a market without demand. Buyers have more opportunities to negotiate, particularly when a property has been sitting, needs repairs, carries high insurance costs, or is priced above comparable sales.

Cape Coral ZIP-level snapshot

Cape Coral waterfront home and canal in bright natural light

Cape Coral remains highly segmented. A canal-front home, a newer inland home, and a property near the river can have very different values even within the same ZIP code.

Approximate 2026 snapshots include:

Cape Coral ZIP Approximate median sale price Typical market time
33904 Around $375,000 Approximately 52–81 days, depending on source
33914 Roughly $421,000–$495,000 Highly variable by property type and location
33991 Around $389,900 Approximately 102–161 days in some reporting periods
33993 Around $445,000 Approximately 86 days

Citywide Cape Coral median sale prices are approximately $352,000–$355,000, while median list prices are closer to $414,000–$425,000. The gap between list and sale prices shows why buyers should analyze closed sales rather than relying only on active listings.

Water access creates another layer of pricing:

  • Freshwater canal homes: generally mid-$400,000s and up
  • Gulf-access homes with bridge restrictions: approximately $600,000–$650,000
  • Sailboat or direct-access properties: approximately $700,000–$755,000 and higher
  • Premium riverfront, wide-basin, or extensively upgraded homes: often $1 million or more

For buyers seeking SWFL waterfront homes, boating access is only part of the analysis. Bridge clearance, canal depth, tides, seawall condition, dock permits, boat lift capacity, and travel time to open water can materially affect value.

Fort Myers real estate trends by area

Fort Myers neighborhood near the Caloosahatchee River with palms and condominium buildings

Fort Myers citywide median sold prices are approximately $319,900–$329,000, depending on the reporting period and property mix. The city offers a wider range of housing styles and price points than many buyers realize.

  • Gateway: Master-planned homes commonly range from approximately $400,000 to $700,000, depending on size, updates, amenities, and location within the community.
  • McGregor corridor: Many homes fall in the mid-$400,000s to more than $2 million, with river proximity, mature landscaping, lot size, and renovations driving the spread.
  • San Carlos Park: A practical option for buyers seeking homes without mandatory HOA fees, with many properties typically priced around $300,000–$500,000.
  • Downtown riverfront condos: Established buildings often range from $400,000–$800,000, while newer luxury construction can exceed $900,000.

Fort Myers tends to offer more established neighborhoods, mature trees, proximity to downtown amenities, and a broader selection of condos. Cape Coral offers a larger supply of single-family homes, canals, boating access, and newer construction in many areas.

Cape Coral vs. Fort Myers: which fits your goals?

Consideration Cape Coral Fort Myers
Typical citywide pricing Approximately $352,000–$355,000 median sale price Approximately $319,900–$329,000
Strongest lifestyle appeal Canal living, boating, newer residential areas Downtown, established neighborhoods, riverfront, cultural amenities
Waterfront options Freshwater, gulf-access, sailboat-access, riverfront Riverfront homes and condos, McGregor corridor
Condo options Available, but single-family homes are prominent Broader selection of established and downtown condos
Buyer priorities Water access, lot, seawall, bridge restrictions Location, building condition, HOA, flood and insurance considerations

The right choice depends on how you plan to use the property. A boater may prioritize Cape Coral access, while a buyer who values walkability, downtown dining, or a condominium lifestyle may prefer Fort Myers.

Total-cost underwriting is essential

Purchase price is only one part of the decision in Southwest Florida. Buyers should review:

  • Roof age and remaining useful life
  • Flood zone and elevation
  • Wind mitigation features
  • Current homeowners and flood insurance estimates
  • Seawall, dock, lift, and pool condition
  • Electrical, plumbing, and HVAC age
  • Condo reserves, master insurance, pending assessments, and association budgets

For investors, Lee County’s approximately 9% decline in real median rents is also important. A property that looked attractive using older rent assumptions may produce a different return today.

For sellers, these same details influence buyer confidence. Documentation of roof work, mitigation improvements, seawall repairs, permits, and insurance history can help reduce uncertainty during negotiations.

How local guidance can help

Whether you are comparing Cape Coral waterfront homes, evaluating a Fort Myers condo, preparing to sell, or looking for a rental investment, hyper-local advice matters. A neighborhood-level pricing strategy is more useful than a broad city average.

Search available Southwest Florida properties or contact RE/MAX Realty Team to connect with a local professional. With more than 100 agents serving Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding areas, our team can help you evaluate the numbers and the property-specific details behind them.

Closing takeaway

The September 2026 market is best described as active but selective. Sales are improving, real prices have softened, and buyers have more negotiating leverage than they did during the most competitive years. At the same time, mortgage rates near 6.76%, insurance expenses, waterfront maintenance, and condo financials can significantly change the total cost of ownership.

The best strategy is to focus less on headlines and more on the specific property, neighborhood, financing plan, and long-term goal.

Figures are approximate and may vary by source, property type, geography, and reporting period. This article is for general informational purposes only and is not an appraisal or insurance, lending, legal, or tax advice.

Read More
lQH58gFo8OT-740×480-1-740×480-2-740×480
Uncategorized
September 10, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Market pulse for the week of September 9–10, 2026

Southwest Florida’s housing market is becoming more active, but that does not mean every city, neighborhood, or property type is moving in the same direction.

The latest data show more transactions, softer median prices, improving affordability, and lower rents across Lee County. At the same time, buyers and sellers are facing a more complicated decision-making environment shaped by insurance costs, mortgage rates, waterfront access, property condition, and neighborhood-level supply.

For anyone following the Cape Coral market update 2026, comparing Cape Coral with Fort Myers, or considering SWFL waterfront homes, the most important takeaway is simple: broad regional statistics are useful, but hyper-local analysis matters more than ever.

Southwest Florida market snapshot

The FGCU Regional Economic Research Institute’s Southwest Florida Real Estate Third Quarter 2026 Report, released September 8, provides the latest regional context using second-quarter data:

  • Single-family home sales increased 14% year over year to approximately 5,600 sales.
  • Condo sales increased 17% to approximately 1,320 sales.
  • The real median single-family price declined 4% compared with Q2 2025.
  • The real median condo price declined 8% year over year.
  • Lee County’s Housing Affordability Index measured 1.35 for all residential properties and 1.30 for single-family homes.
  • Lee County rents declined approximately 9% year over year.

The combination of rising sales and falling median prices suggests a market where buyers are returning, but sellers no longer have the same pricing power seen during the peak years. More homes are changing hands, yet purchasers remain selective and negotiation is still a meaningful part of many transactions.

An affordability index above 1 generally indicates that the benchmark household has enough income to qualify for the typical home under the report’s assumptions. However, actual affordability still depends on the buyer’s down payment, credit profile, insurance premium, taxes, HOA fees, flood coverage, and financing terms.

For more regional research, buyers and investors can review the FGCU RERI real estate research.

Cape Coral: larger inventory, stronger waterfront distinctions

Cape Coral continues to offer one of the broadest selections of homes, canals, lots, and waterfront properties in Lee County. Current market indicators place the median sale price at approximately $352,000 to $355,000.

The city’s numbers require some explanation because different data sets are tracking different portions of the market:

  • Approximately 873 active listings appear in one current market segment.
  • Broader inventory is estimated at approximately 2,090 active listings.
  • The median list price is near $425,000.
  • Typical days on market are around 95 to 100 days.

The difference between the median sale price and median list price is important. It indicates that sellers may need to account for negotiation, inspection findings, appraisal considerations, or price reductions before reaching the closing table. A home listed near $425,000 is not automatically worth that amount simply because it is in Cape Coral.

Cape Coral also cannot be evaluated as one uniform market. A newer inland home without a canal may appeal to a different buyer than an older property on a freshwater canal. Gulf-access waterfront homes, sailboat-access properties, homes near lock systems, and direct river-access locations all carry different premiums.

Waterfront buyers should evaluate:

  1. Type of water access: freshwater, saltwater, gulf access, river access, or sailboat access.
  2. Travel time to open water: canal distance and bridge restrictions can affect usability.
  3. Dock and seawall condition: these can represent significant ownership costs.
  4. Flood zone and elevation: both may affect insurance and financing.
  5. Roof, electrical, plumbing, and storm protection: condition matters heavily to insurers and lenders.
  6. Rental rules: not every neighborhood or HOA permits the same rental strategy.

Waterfront homes and canal access in Cape Coral and Southwest Florida

For buyers, Cape Coral’s longer marketing period creates room to compare properties and negotiate. For sellers, it makes accurate pricing, strong presentation, complete disclosures, and a clear explanation of waterfront features essential.

Fort Myers: a different mix and a different buyer profile

Fort Myers is showing a median sale price near $325,000, with approximately 337 active listings and about 381 homes sold in the latest reported period. Days on market are around 100 days.

Compared with Cape Coral, Fort Myers includes a more varied mix of established neighborhoods, condominiums, townhomes, gated communities, older single-family homes, new construction, and properties closer to employment centers, medical services, shopping, and downtown amenities.

That mix can produce very different results from one ZIP code or neighborhood to another. A condo near the river or downtown may respond to different factors than a suburban single-family home east of I-75. A home in a deed-restricted community may have different monthly costs and rental rules than a non-HOA property.

The city’s lower median sale price does not necessarily mean every Fort Myers property is more affordable than every Cape Coral property. Buyers should compare the full monthly cost, including:

  • Mortgage principal and interest
  • Homeowners or condo insurance
  • Flood insurance, when required or recommended
  • HOA or condominium fees
  • Property taxes
  • Maintenance and reserves
  • Utilities and storm-related improvements

Fort Myers may be especially attractive to buyers who prioritize access to established amenities, healthcare, employment, and a shorter commute over a larger lot or extensive canal system. Cape Coral may be a better fit for buyers seeking more space, pool homes, boating options, or a wider range of waterfront tiers.

Mortgage rates and the September Fed meeting

Freddie Mac reported an average 30-year fixed mortgage rate of 6.71% for the week ending September 3, 2026. The average 15-year fixed rate was approximately 6.04%.

The Federal Open Market Committee is scheduled to meet September 15–16. While the Federal Reserve does not directly set mortgage rates, its policy decisions and economic outlook can influence bond markets and consumer borrowing costs. Mortgage rates may move before, during, or after the meeting based on expectations: not simply on the final announcement.

At current rates, buyers should avoid making decisions based solely on the hope that rates will fall soon. A stronger strategy is to:

  • Obtain a current preapproval before touring seriously.
  • Compare multiple loan programs and lender fees.
  • Consider the payment impact of insurance and HOA costs.
  • Negotiate seller credits where appropriate.
  • Buy within a comfortable payment range rather than stretching to the maximum approval amount.
  • Revisit refinancing only if future savings justify the closing costs.

Insurance is part of the real estate decision

In Cape Coral and Fort Myers, insurance is not a secondary detail. It can affect whether a buyer qualifies for financing, whether a seller’s asking price is realistic, and whether an investment property produces acceptable cash flow.

Two similar homes can have very different insurance costs because of roof age, construction type, elevation, storm protection, flood zone, prior claims, and proximity to water. Waterfront properties may also require additional review of docks, seawalls, retaining structures, and exterior improvements.

Before making an offer, buyers should request insurance estimates early: not after the inspection period begins. Investors should underwrite the property using realistic insurance, vacancy, maintenance, management, taxes, and financing costs rather than relying only on projected rent.

With Lee County rents down approximately 9% year over year, investors should be especially cautious about assuming that rent growth will immediately offset higher borrowing or insurance expenses.

What buyers, sellers, and investors should do now

For buyers

Use the current market to improve your choices, not just to search for a discount. Compare recent closed sales within the same neighborhood and property type. In Cape Coral, pay close attention to waterfront tier and access. In Fort Myers, compare HOA costs, location, age, and property condition.

A home that has been on the market for 100 days may represent an opportunity: but it may also have insurance, condition, pricing, or location challenges that require closer investigation.

For sellers

Pricing based on what a neighbor hoped to receive: or what the market supported several years ago: can lead to extended market time. Buyers are comparing properties carefully, and listings with high insurance costs, outdated finishes, or unclear waterfront advantages may face additional resistance.

A successful listing strategy should include a current comparative market analysis, realistic pricing, professional presentation, transparent property details, and a plan for responding to early buyer feedback.

For investors

Focus on the entire operating picture. Lower rents and mortgage rates near 7% can narrow cash flow, while insurance and maintenance may vary considerably by property. Evaluate long-term rental demand, local restrictions, future capital expenses, and resale liquidity.

In both Cape Coral and Fort Myers, the best investment is not necessarily the least expensive property. It is the property with a sustainable relationship between purchase price, operating costs, location, tenant demand, and long-term maintenance.

Local guidance makes a difference

The current market rewards careful analysis. Whether you are looking for a canal-front home in Cape Coral, a condo in Fort Myers, a rental property, or a primary residence, neighborhood-level information is more useful than a single regional median.

RE/MAX Realty Team serves Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding communities with more than 100 real estate professionals across Southwest Florida. You can search available homes and properties, learn more about our team, or contact RE/MAX Realty Team for guidance tailored to your goals.

RE/MAX Realty Team office in Cape Coral

The takeaway

The September 2026 market is active but selective. Regional sales are rising, median prices are softer, affordability has improved, and rents in Lee County have declined. Cape Coral offers more variation in inventory and waterfront value, while Fort Myers provides a diverse mix of established neighborhoods, condos, townhomes, and single-family properties.

For buyers, preparation and property-level due diligence are essential. For sellers, accurate pricing and presentation matter. For investors, conservative underwriting is more important than optimistic projections.

The right move depends less on timing the entire Southwest Florida market and more on understanding the specific home, neighborhood, insurance profile, and financial strategy in front of you.

Read More
lQH58gFo8OT-740×480-1-740×480
Uncategorized
September 8, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

September 7, 2026 market pulse

Labor Day weekend traditionally marks the beginning of Southwest Florida’s fall real estate season. This year, early momentum is developing in a market that is more balanced, more selective, and increasingly dependent on neighborhood and property type.

Cape Coral and Fort Myers are not moving in exactly the same direction. Cape Coral remains relatively stable, with fewer homes available than a year ago and stronger demand for well-priced single-family and waterfront properties. Fort Myers continues to provide more negotiating room, especially for condos and homes that need updates.

Mortgage rates remain an important part of the conversation. According to Freddie Mac’s Primary Mortgage Market Survey, the 30-year fixed mortgage averaged 6.71% for the week ending September 3, 2026. The 15-year fixed rate averaged 6.04%.

Here is the latest hyper-local look at the Cape Coral market update 2026, Fort Myers real estate trends, and the market for SWFL waterfront homes.

The September 7 market snapshot

The following figures combine the latest available local market data and directional MLS trends. Statistics vary by reporting period, property type, and geographic boundaries.

Metric Cape Coral Fort Myers Lee County
Median sale price Approximately $352,000–$375,000 Single-family: $430,000–$445,000 Varies by segment
Condos Varies by submarket Approximately $220,000–$233,000 Varies by segment
Recent sales activity Approximately 960 homes sold Split between single-family and condos Sales up approximately 7% year over year
Median days on market Approximately 100 days Longer for many condos and older homes Elevated but improving
Months of supply Approximately 4.9 months Single-family: 4.3–4.5 months; condos: 6.5–6.9 months Tightening gradually
Inventory trend Down approximately 25% year over year More balanced in single-family; buyer-leaning in condos Fewer listings than earlier in the year
Sale-to-ask performance Varies by property Varies by property Sellers receiving approximately 93% of asking price
Price reductions Common on stale listings More frequent in buyer-leaning segments Approximately 22% of listings

The overall message is not that the market has suddenly become hot. Instead, the fall season is beginning with fewer choices than last year, steady buyer interest, and a wide gap between properties that are priced correctly and those that are not.

Cape Coral canal homes and waterfront properties in bright natural light

Cape Coral: inventory is tighter, but buyers remain selective

Cape Coral’s median sale price is currently landing somewhere between approximately $352,000 and $375,000, depending on the reporting period and property mix. Roughly 960 homes sold in the latest tracked period, and the typical property has spent about 100 days on the market.

Inventory is down approximately 25% year over year, while absorption is near 4.9 months. That places Cape Coral close to a balanced market overall. It is not the highly competitive environment seen during the pandemic-era boom, but it is also not a market where every seller must accept a steep discount.

The strongest demand remains concentrated in homes with:

  • Updated roofs, electrical systems, and HVAC equipment
  • Pools and attractive outdoor living areas
  • Reasonable insurance profiles
  • Newer construction or completed renovations
  • Desirable canal access or larger lots
  • Convenient access to shopping, restaurants, schools, and major roads

Cape Coral’s size makes neighborhood-level analysis essential. Recent listing medians have illustrated the range:

  • Diplomat: approximately $340,000
  • Mariner: approximately $369,000
  • Burnt Store: approximately $459,000
  • Cape Harbour: approximately $509,000
  • Pelican: approximately $535,000
  • Cape Royal Country Club Estates: approximately $775,000

These figures are listing medians, not appraisals. They can also move substantially when only a small number of homes sell. Still, they show why a buyer comparing northern Cape Coral with Pelican, Cape Harbour, or Cape Royal may be looking at very different markets.

For sellers, the lesson is straightforward: pricing must reflect current competition, not the highest sale from several years ago. For buyers, the tighter inventory trend means the best homes may attract attention quickly, even while less competitive listings remain available for negotiation.

Fort Myers: different conditions for single-family homes and condos

Fort Myers remains more segmented than the citywide median suggests.

Single-family homes are reporting a median sale price of approximately $430,000 to $445,000, with 4.3 to 4.5 months of supply. That is near-balanced territory. Buyers have time to investigate a property and negotiate, but a well-maintained home in a desirable location may still attract multiple interested parties.

Condos are operating differently. Median prices are approximately $220,000 to $233,000, while inventory has expanded to roughly 6.5 to 6.9 months of supply. This gives condo buyers more selection and leverage, particularly when association fees, insurance costs, reserves, or potential assessments are high.

Established Fort Myers neighborhood with mature landscaping and well-maintained homes

Neighborhoods also tell different stories. Established areas such as Whiskey Creek, Briarcliff, and Heritage Palms may attract buyers who value mature landscaping, community amenities, and convenient access to shopping, healthcare, and employment centers. Other areas, including Island Park and older condo communities, may offer lower entry prices but require closer review of condition and carrying costs.

Fort Myers buyers should compare:

  • Monthly homeowners association fees
  • Association reserves and meeting minutes
  • Insurance coverage and deductibles
  • Roof age and building maintenance
  • Rental restrictions
  • Special assessments
  • Flood exposure and elevation
  • The property’s total monthly cost, not just the purchase price

SWFL waterfront homes: price tiers still vary dramatically

Waterfront remains one of the most important distinctions in the Cape Coral market. However, “waterfront” is not a single category.

Approximate price tiers for Cape Coral waterfront properties include:

Waterfront category Approximate price range
Freshwater canal homes Mid-$400,000s and up
Gulf-access homes with bridge restrictions Approximately $600,000–$650,000
Direct Gulf or sailboat access Approximately $700,000–$755,000 and up
Premium riverfront, wide-basin, or extensively upgraded homes $1 million or more

The exact value depends on canal width, bridge clearance, seawall condition, dock and lift improvements, boating route, storm protection, remodeling, lot size, and proximity to open water.

A buyer should ask more than whether a property is labeled “waterfront.” Important questions include:

  • How long does it take to reach the Caloosahatchee River or Gulf?
  • Are there bridges or height restrictions?
  • Is the seawall permitted and structurally sound?
  • Are the dock and lift insurable?
  • What flood insurance is required?
  • Has the property experienced storm damage?
  • Are short-term rentals permitted?

The least expensive waterfront home may not provide the most useful boating access. Likewise, a higher-priced property may justify its premium if it offers direct access, a newer seawall, a protected basin, or a more desirable location.

Mortgage rates and the September 15–16 FOMC meeting

At 6.71%, the current 30-year fixed rate continues to influence affordability. The 15-year rate of 6.04% may appeal to buyers who want to pay down principal more quickly, but the higher monthly payment requires careful budgeting.

The Federal Reserve’s September 15–16 FOMC meeting will be closely watched. The Fed does not directly set mortgage rates, but its policy decisions and economic guidance can affect bond markets and longer-term borrowing costs.

If rates ease after the meeting, some buyers may return to the market or gain additional purchasing power. If rates remain elevated, buyers are likely to continue emphasizing price, seller concessions, rate buydowns, and lower-cost properties.

The practical advice is to make decisions based on the payment you can afford today. Refinancing may become an option later, but it should not be the foundation of a purchase decision.

Insurance remains a major part of affordability

Insurance must be addressed early, particularly for coastal, older, waterfront, elevated, and condo properties.

Recent Citizens Property Insurance changes included an average decrease for some multiperil policies and a separate reduction for certain wind-only policies. The impact varies by property, coverage type, deductible, mitigation features, roof age, location, and prior claims history. Buyers should review Citizens Property Insurance resources and obtain a property-specific quote before the inspection period expires.

A complete housing budget should include:

  • Homeowners insurance
  • Wind and flood coverage
  • Property taxes
  • HOA or condo fees
  • Utilities
  • Maintenance
  • Seawall, dock, or pool expenses
  • Reserves for major repairs

Home-buying due diligence with keys, inspection materials, and insurance documents

Strategy for buyers, sellers, and investors

For buyers

The fall market may offer more negotiating room than the fastest-moving years, but preparation still matters.

  • Get fully pre-approved before touring homes.
  • Compare recent closed sales rather than relying on asking prices.
  • Review price reductions and total days on market.
  • Request insurance estimates early.
  • Investigate permits, roofs, seawalls, docks, and storm repairs.
  • For condos, review reserves, assessments, rental rules, and association finances.
  • Consider both Cape Coral and Fort Myers if your lifestyle and commute allow flexibility.

For sellers

The post-Labor Day season can bring more activity from seasonal residents, relocating households, and second-home buyers. However, buyers are informed and have alternatives.

Sellers should:

  • Price against current comparable homes.
  • Complete high-impact repairs before listing.
  • Gather roof, permit, insurance, and renovation records.
  • Present outdoor spaces and waterfront features clearly.
  • Explain bridge clearance, boating access, and seawall condition.
  • Monitor showing activity during the first two weeks.
  • Be prepared to adjust if the market provides negative feedback.

For investors

Investors should underwrite the entire property rather than focusing only on purchase price.

Include realistic rent, vacancy, management, insurance, taxes, HOA fees, repairs, utilities, financing, and capital reserves. Cape Coral waterfront homes may have strong lifestyle and rental appeal, but seawalls, lifts, flood exposure, and insurance can materially affect returns. Fort Myers condos may provide a lower entry price, but association restrictions and assessments require careful review.

The bottom line for September 7, 2026

Southwest Florida is entering its fall market with improving momentum but continued segmentation.

Cape Coral is close to balanced: inventory is down approximately 25% year over year, absorption is near 4.9 months, and well-priced single-family and waterfront homes can attract serious attention.

Fort Myers is split: single-family homes are near-balanced with 4.3 to 4.5 months of supply, while condos remain more buyer-friendly with 6.5 to 6.9 months of supply.

Across Lee County, sales are up approximately 7% year over year, sellers are capturing about 93% of asking price, and roughly 22% of listings have experienced price cuts. That combination points to a market that is active: but still rewards realistic pricing and careful analysis.

The key takeaway is simple: the citywide median is only the beginning. Neighborhood, property type, insurance profile, waterfront access, condition, and financing costs will determine the right strategy.

Search available Southwest Florida properties, meet the RE/MAX Realty Team, or contact our office for guidance from local cape coral real estate agents and experienced realtors cape coral buyers and sellers can trust throughout Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding communities.

Market figures are approximate and may vary by source, reporting period, property type, and geographic boundaries. This article is for general informational purposes only and is not an appraisal, insurance quote, lending decision, or substitute for individualized real estate, legal, tax, insurance, or financial advice.

Read More
rNR6H1lPJa8
Uncategorized
September 7, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Market pulse for the week of September 7, 2026

September brings a seasonal crossroads to Southwest Florida real estate. Historically, it is one of the quietest transaction months of the year, as buyers and sellers settle into post-Labor Day routines. At the same time, Atlantic hurricane season reaches its climatological peak, mortgage rates are pressing toward 7%, and the Federal Open Market Committee is scheduled to meet September 15–16.

Those factors are creating a market that rewards preparation rather than urgency. Buyers have selection and negotiating room, but financing and insurance costs still deserve careful attention. Sellers can attract serious interest, but pricing and property presentation matter more than they did during the fast-moving years of 2021 and 2022.

Here is the latest approximate snapshot based on MLS and licensed-market data where applicable.

Market at a glance: Lee County

Lee County remains more balanced than it was during the inventory surge, although buyers still have meaningful choices:

  • Median sale price: Approximately $375,000, down about 3% year over year
  • Active MLS listings: Approximately 9,304 at the end of August
  • Median time to contract: Approximately 60 days
  • Seller proceeds: About 93.4% of the original asking price, on average
  • Listings with price reductions: Approximately 22%
  • Market direction: More balanced overall, with buyer leverage in several segments

Inventory has eased from its peak, but this is not a market where every well-priced home sells immediately. Condition, location, flood exposure, insurance availability, property type, and pricing strategy can make a substantial difference.

Mortgage rates are another important part of the equation. According to Freddie Mac’s Primary Mortgage Market Survey, the average 30-year fixed mortgage rate was approximately 6.71% for the week ending September 3, up from 6.66% the prior week and 6.50% a year earlier. The 15-year fixed rate was near 6.04%.

The September 15–16 FOMC meeting will be closely watched, but buyers should remember that mortgage rates do not move in lockstep with the Federal Reserve’s overnight policy rate. They are influenced more directly by the 10-year Treasury, inflation expectations, bond-market conditions, and the broader economic outlook. A rate decision or press conference could affect market sentiment, but it will not automatically produce an immediate drop in mortgage rates.

Cape Coral: balanced market, highly local outcomes

Cape Coral is roughly balanced overall, with an approximate median sale price near $375,000, up a modest 0.4% year over year. New construction represented about 24% of recent sales, which continues to give buyers an alternative to existing homes.

However, citywide statistics only tell part of the story. A direct Gulf-access home near the Caloosahatchee River behaves very differently from an off-water resale several miles inland. Buyers comparing those properties need to evaluate them as separate market segments, not as interchangeable Cape Coral homes.

For example:

  • An off-water home may compete primarily on price, condition, age, layout, and proximity to shopping or schools.
  • A freshwater canal home may appeal to buyers seeking water views, kayaking, or a private dock without the cost of Gulf access.
  • A Gulf-access property is also evaluated on canal depth, bridge clearance, boating time, seawall condition, dock improvements, and the route to open water.
  • A newer construction home may include warranties, modern storm protection, and energy-efficient systems that influence its value beyond the basic sale price.

This is where working with experienced Cape Coral real estate agents becomes especially important. The best comparison is often not the nearest listing: it is the most similar home in terms of water access, construction age, flood zone, improvements, and insurance profile.

Buyers searching for realtors Cape Coral should look for professionals who can explain these distinctions clearly and connect the purchase price to long-term ownership costs.

Cape Coral canal-front home with a dock and screened lanai

Fort Myers: more leverage for prepared buyers

Fort Myers is currently more buyer-leaning than Cape Coral. The approximate median sale price is $348,000, down about 6.1% year over year, with homes taking approximately 64 days to go under contract.

Cash buyers represented roughly 52% of Fort Myers sales, compared with approximately 28% in Cape Coral. That cash presence can make certain neighborhoods and price points more competitive, but it does not eliminate negotiation. Buyers are negotiating approximately 9% below asking on average, depending on the property type and the difference between the initial list price and the home’s realistic market value.

For buyers, this may create opportunities to negotiate on:

  • Price
  • Closing costs or rate-buydown contributions
  • Repairs and credits
  • Inspection-related items
  • Closing dates
  • Personal property or furnishings, where appropriate

For sellers, the data reinforces the importance of entering the market with a realistic price from day one. A home that starts too high may accumulate days on market, require multiple reductions, and ultimately attract less attention than a comparable property priced correctly at launch.

The broader Fort Myers real estate trends also vary by neighborhood. Downtown-adjacent condos, established single-family communities, golf-course properties, and homes closer to the river or coast can have very different buyer pools and timelines.

SWFL waterfront homes: value depends on access and carrying costs

Waterfront property remains one of Southwest Florida’s strongest lifestyle draws, but “waterfront” is not a single category.

Approximate pricing tiers currently include:

  • Freshwater canal homes: Often in the mid-$400,000s
  • Gulf-access homes with bridge restrictions: Frequently in the $600,000s
  • Direct or sailboat-access homes: Commonly in the high-$600,000s to $700,000s and above
  • Premium riverfront, wide-basin, or extensively upgraded homes: Often above $1 million

These are broad ranges, not appraisals. A home’s price can change substantially based on seawall age, dock and lift condition, pool, roof, storm protection, water depth, bridge restrictions, lot orientation, renovations, and boating distance.

Many waterfront homes should be marketed with a realistic window of approximately 70–100 days or more, particularly when they are priced above the median or require specialized insurance underwriting. Buyers should also budget time for inspections that go beyond the typical home inspection, including seawall, dock, roof, elevation, electrical, and wind-mitigation reviews.

Insurance is central to the waterfront decision. The approximate average annual homeowners premium in Lee County is $2,197, although actual costs can vary dramatically by home age, construction, roof, wind mitigation, flood exposure, coverage limits, deductible, and whether the property is on a canal or open water.

Citizens Property Insurance approved an average rate decrease of approximately 8.7%, effective July 1, 2026, and Lee County had roughly 6,508 Citizens policies in force in the referenced data. The decrease is encouraging, but buyers should never assume that a statewide or countywide average will match a specific property’s quote.

Hurricane-season and insurance awareness

September is the climatological peak of Atlantic hurricane season. That does not mean a storm will affect Southwest Florida, but it does mean buyers and owners should treat preparation as part of responsible real estate planning.

Before purchasing, request insurance quotes early: especially for waterfront homes, older homes, homes with older roofs, and properties with unusual construction or additions. Ask about wind mitigation credits, flood insurance, deductibles, roof age requirements, and coverage limitations.

A strong real estate decision is not based only on whether a home fits the budget at closing. It also considers the recurring costs of insurance, flood coverage, utilities, maintenance, seawalls, docks, and reserves for future repairs.

What buyers should do now

The September market can reward buyers who are organized:

  1. Get an updated preapproval. A rate near 6.71% can produce a different monthly payment than an earlier estimate.
  2. Compare total monthly ownership costs. Include taxes, insurance, flood coverage, HOA fees, utilities, and maintenance.
  3. Separate price from value. A lower-priced home may need a roof, seawall, HVAC system, or major insurance investment.
  4. Use the FOMC meeting as information, not a deadline. Waiting for a rate announcement may or may not improve your financing outcome.
  5. Compare neighborhoods and property types carefully. Cape Coral off-water, freshwater, and Gulf-access homes are distinct markets.
  6. Build negotiation terms into the offer. Price is only one part of a successful contract.

What sellers should expect

Sellers should expect buyers to be more analytical. They are comparing not only list prices but also price reductions, days on market, insurance quotes, inspection findings, and likely resale value.

A strong listing strategy should include accurate pricing, high-quality photography, clear disclosure of improvements, documentation for roofs and storm protection, and a thoughtful explanation of waterfront features. If your property has a newer roof, updated electrical system, seawall improvements, wind mitigation, or favorable flood characteristics, make those details easy for buyers and their agents to understand.

The goal is not simply to be listed. It is to be the most compelling option among the homes buyers can see today.

A note for investors

Investors should underwrite conservatively in the current environment. Mortgage rates near 7%, insurance costs, maintenance, vacancy, property management, and local rental demand all affect the actual return.

Cape Coral and Fort Myers may offer opportunities, but investors should avoid relying on rapid appreciation to make a deal work. Analyze the property using realistic rents, realistic repair costs, conservative financing assumptions, and an adequate reserve fund. Waterfront rentals also require careful review of flood exposure, dock maintenance, storm preparation, and local regulations.

Real estate agent meeting with Southwest Florida buyers to review a market report

Bottom line: September favors informed decisions

The Cape Coral market update 2026 story is not one-size-fits-all. Lee County is more balanced, Cape Coral is relatively steady with wide neighborhood variation, and Fort Myers is giving prepared buyers more leverage. Mortgage rates are pressing toward 7%, the September FOMC meeting may influence expectations, and hurricane-season awareness makes insurance and property condition especially important.

For buyers, the opportunity is choice and negotiation. For sellers, the opportunity is to stand out through accurate pricing and preparation. For investors, the opportunity is selective: but only when the numbers work without relying on optimistic assumptions.

If you are considering a move, sale, investment, or waterfront purchase, connect with the RE/MAX Realty Team. Our 100+ agents bring local knowledge across Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding Southwest Florida communities. As the #1 producing brokerage in the region, we are ready to help you evaluate the market and take the next step with confidence.

Search available Southwest Florida properties.

Read More
lQH58gFo8OT-740×480-1-740×480
Uncategorized
September 5, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

First week of September 2026 | Market pulse refreshed September 4, 2026

Mortgage rates moved higher as fall begins. The average 30-year fixed rate reached 6.71%, up from 6.66% the previous week and the highest level since July 31, 2025. The 15-year fixed rate rose to 6.04%.

At the same time, the Federal Open Market Committee is scheduled to meet September 15–16. That timing may tempt buyers to pause and wait for a possible change in the federal funds rate. But mortgage rates do not move one-for-one with the Fed’s policy rate. Fixed mortgage rates are influenced more directly by the 10-year Treasury yield, inflation expectations, and investor demand for mortgage-backed securities.

So the practical question for Southwest Florida buyers and sellers is not simply, “What will the Fed do?” It is: What do this week’s numbers mean as the fall market begins?

The answer is a market with opportunity: but one that rewards preparation, realistic pricing, and careful attention to carrying costs.

The September market at a glance

The latest licensed MLS data show a clear difference between Cape Coral and Fort Myers, even though both are part of the broader Lee County market.

Market indicator Cape Coral Fort Myers
Median sale price Approximately $375,000 Approximately $348,000
Year-over-year price change Up approximately 0.4% Down approximately 6.1%
Sold price per square foot Approximately $220 Approximately $203
Sellers’ share of original asking price Approximately 94.2% Approximately 91.4%
Median days to contract Approximately 52 days Approximately 64 days
Momentum score 56/100 : balanced 40/100 : buyer-leaning
New construction share of recent sales Approximately 24% Approximately 4%
Cash-buyer share Approximately 28% Approximately 52%

Cape Coral is showing more price stability, supported in part by continued new-construction activity and demand for canal-front homes. Fort Myers is giving buyers more leverage, with softer pricing, longer marketing times, and a greater share of cash purchases.

For context, Lee County’s median sale price is approximately $375,000, down about 3% year over year. There were approximately 9,304 active MLS listings at the end of August. Sellers captured about 93.4% of original asking price, and the median time to contract was approximately 60 days. About 22% of listings had experienced a price cut.

Zillow’s for-sale inventory stood near 11,185 homes, down approximately 6.6% month over month, while the county’s typical home value was approximately $337,352, down about 5.4% year over year. July CoStar/Homes.com data also showed Fort Myers MSA sales up approximately 14.5% year over year, with a median price near $358,000 and inventory at its lowest level of 2026.

The takeaway: inventory has eased from its peak, but buyers still have choices: and sellers must compete.

Cape Coral: balanced, but very neighborhood-specific

Cape Coral’s overall momentum score of 56 suggests a balanced market. However, conditions vary significantly by location, property type, water access, age, and condition.

New construction represents approximately 24% of recent Cape Coral sales, making builders an important part of the competitive landscape. Buyers may compare an existing home not only with nearby resale properties but also with builder incentives, rate buydowns, warranties, and design selections.

Neighborhood-level numbers reinforce the importance of hyper-local analysis:

  • Rose Garden: approximately $850,000, up about 39% year over year; homes selling in roughly nine days.
  • Yacht Club: approximately $617,000, up about 14%.
  • Palaco Grande: up approximately 22%.
  • Cape Harbour: approximately $512,000, down about 20%.
  • Tarpon Landings: down approximately 24%, although the sample size is thin.

These figures should not be treated as guarantees for every property. A handful of sales can move the median sharply in a smaller neighborhood. Still, they show why broad headlines about “the Cape Coral market” are not enough. A direct Gulf-access home in one boating community may be behaving very differently from an off-water resale home several miles away.

Bright Southwest Florida neighborhood with canal-front homes and palm-lined streets

Fort Myers: more negotiating room for prepared buyers

Fort Myers is currently more buyer-leaning, with a momentum score of 40/100. The median sale price is approximately $348,000, down about 6.1% year over year, and the typical property takes approximately 64 days to reach a contract.

Buyers are negotiating roughly 9% below asking price in the current market, although the discount varies widely. A well-priced, updated home in a desirable neighborhood may still attract strong interest. A property with deferred maintenance, high insurance costs, or an ambitious list price may sit considerably longer.

Fort Myers also has a much higher cash-buyer share: approximately 52%: than Cape Coral’s 28%. That creates a different competitive environment. Cash buyers may be especially active in lower-priced homes, investment properties, and homes requiring repairs. Financing buyers can still compete, but they should be fully underwritten and ready to move when the right property appears.

Fort Myers neighborhood movers include:

  • Heritage Palms Estates: approximately $856,000; selling in about five days.
  • Whiskey Creek: approximately $514,000; selling in about six days.
  • Briarcliff: approximately $810,000; selling in about seven days.
  • The Forest: approximately $730,000, up about 21%.
  • Island Park Village: down approximately 47% on a thin sample.

Again, these neighborhood figures require context. Small samples, changes in the mix of homes sold, renovations, and waterfront exposure can all affect year-over-year comparisons.

SWFL waterfront homes: price tiers matter

Waterfront buyers should focus on the type and quality of access: not simply the word “waterfront” in a listing description.

Current pricing generally falls into these broad ranges:

  • Freshwater canal homes: often in the mid-$400,000s.
  • Gulf-access homes with bridge restrictions: frequently in the $600,000s.
  • Direct or sailboat-access homes: commonly in the high $600,000s to $700,000s and above.
  • Premium riverfront, wide-basin, or extensively upgraded properties: often above $1 million.

A realistic marketing window for many SWFL waterfront homes is approximately 70–100 days or more, depending on price, insurance, access, condition, and presentation. Desirable properties can move quickly, but sellers should not assume every waterfront listing will receive immediate offers.

Buyers should verify:

  • The actual boating route to open water
  • Bridge heights and clearance restrictions
  • Seawall, dock, lift, and electrical condition
  • Permits for seawalls, docks, lifts, pools, and additions
  • Flood zone and elevation information
  • Wind, flood, and homeowners insurance quotes

Insurance is part of the waterfront purchase decision, not an afterthought. The average annual homeowners premium in Lee County is approximately $2,197, although an individual property’s cost can vary substantially based on age, construction, mitigation features, location, roof, flood exposure, and coverage limits.

Citizens Property Insurance has approximately 6,508 policies in force in Lee County. Its first average rate decrease since 2015: approximately 8.7%: took effect July 1, 2026. Even with that change, buyers should obtain property-specific quotes before the inspection or due-diligence period expires.

Southwest Florida buyers reviewing market information with a real estate professional

What buyers should do this fall

Shop the market, not the Fed

If a home meets your needs and the payment works within your budget, waiting solely for the September FOMC meeting may not improve your position. Mortgage rates could move lower, remain steady, or rise depending on Treasury markets and economic expectations.

A future refinance may be possible, but the price, financing terms, and seller concessions available today are concrete factors.

Underwrite the full carrying cost

Before making an offer, estimate:

  • Principal and interest
  • Homeowners insurance
  • Flood insurance, if required or advisable
  • Property taxes
  • HOA or condo fees
  • Utilities and routine maintenance
  • Pool, seawall, dock, and boat-lift expenses
  • Possible storm-related repairs

This is especially important for waterfront homes and properties in communities with substantial reserves or upcoming assessments.

Compare closed sales: not just asking prices

Recent closed sales provide the most useful pricing evidence. Ask your agent to compare similar homes by neighborhood, living area, lot, water access, age, renovations, and condition.

In the current market, buyers may also consider requesting a temporary rate buydown, seller-paid closing costs, repair credits, or other concessions. The best strategy depends on the property and the seller’s priorities.

What sellers should expect

Sellers should price against today’s competition, including new construction in Cape Coral. A home that was competitive last year may now be compared with a builder offering incentives or a newer property with lower expected maintenance.

In Fort Myers especially, sellers should expect negotiation. Rate buydowns, closing-cost assistance, repair credits, and warranties are back on the table. These concessions can help a buyer manage the higher payment created by a 6.71% mortgage rate without requiring the seller to make a large headline price reduction.

The first two weekends matter. Strong photography, accurate pricing, easy showing access, clean presentation, and a clear explanation of insurance and improvements can help a listing stand out before it accumulates days on market.

A note for investors

Cash-buyer competition differs sharply between Cape Coral and Fort Myers. Investors should examine more than purchase price and projected rent. Review rental demand by neighborhood, seasonality, flood and insurance costs, property management fees, HOA rules, rental restrictions, reserves, and pending assessments.

For condominiums and gated communities, read the association documents carefully. The most attractive projected return can change quickly when insurance premiums, reserves, or maintenance obligations are higher than expected.

The bottom line for September 2026

Cape Coral is broadly balanced, with relatively stable pricing and meaningful new-construction competition. Fort Myers is more buyer-leaning, with greater negotiating room and a larger cash-buyer presence. Lee County overall offers more selection than a tight seller’s market, but the best homes: particularly well-priced waterfront and turnkey properties: can still move quickly.

Mortgage rates are now at 6.71% for a 30-year fixed loan, and the September FOMC meeting may influence market expectations. But buyers should shop the market rather than wait on the Fed. The right decision depends on the full monthly cost, the quality of the property, the negotiated terms, and your personal timeline.

For local guidance from experienced Cape Coral real estate agents and realtors in Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding communities, connect with RE/MAX Realty Team. With more than 100 real estate professionals and deep knowledge of Southwest Florida, our team can help you evaluate the numbers and move forward with confidence.

Search available Southwest Florida properties or contact our office to discuss your next move.

Market figures are approximate and based on licensed MLS data refreshed September 4, 2026. Neighborhood statistics may reflect small sample sizes and should be evaluated with a property-specific comparative market analysis.

Read More
lQH58gFo8OT-740×480
Uncategorized
September 4, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Updated September 3, 2026

Cape Coral and Fort Myers are no longer moving in lockstep with the rapid-growth market of a few years ago. Instead, Southwest Florida has entered a more balanced phase, where pricing, property type, location, insurance costs, and waterfront access all play a larger role in the outcome of a transaction.

For buyers, this means more choice and negotiating room in several segments. For sellers, it means accurate pricing and strong presentation matter more than simply listing high and waiting. For investors and second-home buyers, the opportunity is real: but the numbers need to be evaluated property by property.

Here is the latest hyper-local look at the Cape Coral market update 2026, Fort Myers real estate trends, and the market for SWFL waterfront homes.

Cape Coral market update 2026: A balanced market with meaningful variation

According to Realtor.com’s August 2026 Cape Coral market data, the city had approximately 5,910 homes for sale, a median listing price of $414,173, and a median sold price of $383,000. Homes spent a median of 85 days on the market, while the average sale-to-list price ratio was about 97%.

Realtor.com classified Cape Coral as a balanced market, meaning neither buyers nor sellers have a decisive overall advantage. However, the citywide numbers only tell part of the story.

A separate April 2026 single-family report using Florida Gulf Coast MLS data showed:

  • Median sale price: $381,000
  • Closed sales: 552
  • Median days on market: 44
  • List price received: 97.3%
  • Active inventory: 2,584 homes
  • Months of supply: 4.7

That April report also showed closed sales increasing year over year while active inventory and months of supply declined. In practical terms, well-priced single-family homes were attracting buyers faster than the broader citywide average.

The difference between 44 days and 85 days is a reminder that market statistics depend heavily on the reporting period and property mix. A citywide number may include condos, villas, luxury homes, waterfront properties, and listings that have already undergone one or more price reductions.

RE/MAX Realty Team agent reviewing Southwest Florida market trends with clients

Cape Coral neighborhoods are telling different stories

Cape Coral is a large and diverse city. Prices and marketing times can change considerably from one area to another.

August listing data showed approximate median prices such as:

  • Diplomat: $339,900
  • Mariner: $369,000
  • Burnt Store: $458,800
  • Pelican: $534,950
  • Cape Harbour: $509,225
  • Cape Royal Country Club Estates: $774,500

These are listing medians, not appraisals or guarantees of value. Still, they illustrate why buyers should compare homes within the same neighborhood, property type, construction era, and waterfront category.

ZIP codes also show a wide range:

  • 33909: approximately $342,500 median listing price
  • 33993: approximately $399,702
  • 33904: approximately $400,000
  • 33914: approximately $539,000

For buyers, this creates opportunities to adjust the search based on priorities. A buyer who wants a newer home, more living space, or a larger lot may find better value in northern Cape Coral. Someone prioritizing Gulf access, mature landscaping, restaurants, or proximity to the Caloosahatchee River may focus farther south and west: but should expect a different price range.

For sellers, neighborhood-level analysis is essential. A comparable sale several miles away may not reflect the value of a home with different canal access, flood exposure, road proximity, updates, or community amenities.

SWFL waterfront homes remain a separate market

Cape Coral’s waterfront market continues to behave differently from its non-waterfront segment. Buyers have more choices, but not every waterfront property offers the same lifestyle or boating value.

Recent 2026 market analyses place the median sale price for canal waterfront single-family homes near $610,000, while Gulf-access waterfront homes have been reported closer to $755,000 over selected 120-day periods. Other market summaries show a broader range depending on access and property condition.

A useful way to think about the segment is by category:

  • Freshwater canal homes: Often priced in the mid-$400,000s, depending on the home and canal setting
  • Gulf-access homes with bridge restrictions: Frequently in the $600,000 range, with boating limitations varying by route
  • Direct or sailboat-access homes: Commonly in the upper-$600,000s to $700,000s and higher
  • Premium riverfront, wide-basin, or highly upgraded homes: May exceed $1 million

Waterfront homes can also take longer to sell. A realistic marketing window for many canal and Gulf-access properties is approximately 70 to 100 or more days, particularly when the list price does not reflect current competition.

Buyers should evaluate more than the view. Important questions include:

  • How quickly can a boat reach open water?
  • Are there bridges, locks, or height restrictions?
  • Is the seawall in good condition?
  • Are the dock, lift, and electrical systems permitted and insurable?
  • What are the flood zone and elevation considerations?
  • How do homeowners insurance and flood insurance affect the monthly cost?
  • Is the home suitable for seasonal, long-term, or short-term rental use?

The phrase “waterfront” is not specific enough by itself. Two homes may both be advertised as waterfront while offering very different boating access, maintenance costs, and resale appeal.

Fort Myers real estate trends: Cooling, active, and highly location-dependent

Fort Myers is also showing a more measured market in 2026. Current market reporting places the city’s blended median sale price roughly between $330,000 and $350,000, depending on the reporting period and whether the data includes condos, villas, and single-family homes.

Realtor.com’s August 2026 Fort Myers market data characterized the city as a cooler market, with homes taking approximately 93 days on the market and selling for about 4.5% below asking price on average. Inventory was estimated at around five months of supply, placing the market near balanced to slightly buyer-leaning conditions.

These numbers support several important Fort Myers real estate trends:

  1. Buyers have time to compare options.
    Multiple properties may be available in similar price ranges, especially among condos, older homes, and higher-priced listings.

  2. Condition and location are increasingly important.
    Move-in-ready homes near popular corridors may perform better than properties requiring major repairs or insurance upgrades.

  3. Property type affects the headline number.
    A downtown condo, a Gateway-area home, a McGregor corridor property, and a home near the river may all have different buyer pools and pricing dynamics.

  4. Sellers need a plan for negotiations.
    Credits for closing costs, repairs, rate buydowns, or insurance-related items may be part of the transaction even when the list price appears competitive.

For anyone comparing Cape Coral and Fort Myers, the best choice depends on lifestyle as much as price. Cape Coral offers an extensive canal network, newer construction in many areas, and a suburban layout. Fort Myers provides a broader mix of established neighborhoods, condos, historic areas, riverfront locations, and access to major employment and cultural destinations.

What buyers should do in today’s market

The current market rewards preparation rather than urgency.

Before touring homes, buyers should:

  • Obtain a current preapproval based on a realistic monthly budget
  • Account for property taxes, homeowners insurance, flood insurance, HOA fees, and maintenance
  • Compare recent closed sales: not just active listings
  • Review the property’s insurance history when available
  • Schedule thorough inspections
  • Research rental restrictions before purchasing an investment property
  • Separate cosmetic concerns from major structural or mechanical issues

In Cape Coral, buyers interested in SWFL waterfront homes should also request information about seawalls, docks, lifts, canal access, and permits early in the process. A lower purchase price may not represent a bargain if major waterfront repairs are approaching.

You can search available Southwest Florida properties across Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding communities.

What sellers should do before listing

Sellers should begin with a property-specific pricing analysis rather than relying on a citywide median or an online estimate.

A strong listing strategy may include:

  • Reviewing the most recent comparable sales
  • Pricing against current competition, not past peak prices
  • Completing high-impact repairs and cosmetic updates
  • Improving exterior presentation and photography
  • Preparing documentation for permits, roof work, seawalls, and renovations
  • Clearly explaining waterfront access and boating characteristics
  • Building a marketing plan for both local and out-of-state buyers

The right price is designed to create activity early. A listing that starts too high may accumulate days on market, require multiple reductions, and eventually appear less attractive than a newer competing property.

Why working with local Cape Coral real estate agents matters

Hyper-local knowledge is especially valuable in a market where two nearby homes can perform very differently. Experienced cape coral real estate agents and realtors cape coral should be able to explain differences between neighborhoods, canal systems, insurance considerations, flood zones, construction types, and buyer demand.

RE/MAX Realty Team serves Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and neighboring Southwest Florida communities. With more than 100 full-time real estate professionals and offices serving the region, the team provides guidance for buyers, sellers, renters, second-home owners, and investors.

RE/MAX Realty Team office serving Southwest Florida real estate clients

Meet the RE/MAX Realty Team or contact the office to discuss your goals and receive advice based on your specific property, neighborhood, and timeline.

The takeaway

Cape Coral and Fort Myers are not experiencing a single, uniform market in 2026. Overall conditions are closer to balanced, but buyers may find stronger negotiating power in condos, higher-priced homes, and some waterfront segments. At the same time, well-priced, move-in-ready homes can still attract attention and sell more quickly.

The most important insight is simple: the citywide median is only the starting point. Your best strategy depends on the neighborhood, property type, condition, insurance profile, waterfront access, and intended use.

For a specific buying, selling, or investment decision, use current comparable sales and guidance from a local professional: not a broad market headline alone.

Market data cited in this article comes from Realtor.com’s August 2026 market pages and Florida Gulf Coast MLS data reported in the April 2026 Cape Coral single-family and condo update. Statistics can vary by source, date range, and property type.

Read More
  • 1
  • 2
  • 3

Exceptional Service. Local Expertise. Proven Results.

(239) 242-2000

Cape Coral Office
2326 Del Prado Blvd. S.
Cape Coral, FL 33990


Fort Myers Office
6611 Orion Dr. #104
Fort Myers, FL 33912

Quick Links

  • Company
  • Search Online
  • Sell With RE/MAX
  • Contact Our Office

Join Our Team

Build your real estate career with a collaborative, experienced team committed to helping agents grow, succeed, and reach their full potential.

© 2026 RE/MAX Realty Team. All Rights Reserved | Website By: OMG