RRT Logo
  • HOME
  • ABOUT US
  • PROPERTIES FOR SALE
  • SELL YOUR HOME
  • SEARCH BY LOCATION
    • Cape Coral
    • Fort Myers
    • Fort Myers Beach
    • North Fort Myers
    • Lehigh Acres
    • Sanibel
    • Alva
    • Labelle
    • Estero
    • Matlacha
  • (239) 242-2000
CONTACT US
RRT Logo
RRT Logo
  • HOME
  • ABOUT US
  • PROPERTIES FOR SALE
  • SELL YOUR HOME
  • SEARCH BY LOCATION
    • Cape Coral
    • Fort Myers
    • Fort Myers Beach
    • North Fort Myers
    • Lehigh Acres
    • Sanibel
    • Alva
    • Labelle
    • Estero
    • Matlacha
  • (239) 242-2000
CONTACT US
RRT Logo
  • HOME
  • ABOUT US
  • PROPERTIES FOR SALE
  • SELL YOUR HOME
  • SEARCH BY LOCATION
    • Cape Coral
    • Fort Myers
    • Fort Myers Beach
    • North Fort Myers
    • Lehigh Acres
    • Sanibel
    • Alva
    • Labelle
    • Estero
    • Matlacha
  • (239) 242-2000
CONTACT US
Uncategorized
HomeUncategorizedPage 3

Category: Uncategorized

qyDkAgCNuSn
Uncategorized
September 19, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Daily market update for Friday, September 18, 2026

Is the buyer’s market ending in Southwest Florida?

The short answer is: not exactly, but the market is changing.

Lee County’s single-family inventory has fallen to roughly 5,944 active listings, down about 18% year over year and back to its lowest listing baseline since January 2024. That is a meaningful shift after several years of elevated supply.

However, total active listings across all property types remain high. Condominiums, rental properties, and some higher-priced homes are still giving buyers negotiating leverage. In other words, Southwest Florida is not moving from a broad buyer’s market into a seller’s market overnight. Instead, the market is becoming more segmented.

Single-family homes are tightening. Condos and rentals remain softer. Insurance and mortgage costs continue to influence what buyers can afford. And across nearly every category, pricing is still the deciding factor.

That is the central message in this Cape Coral market update for 2026.

The larger Southwest Florida picture

The FGCU Regional Economic Research Institute’s Q3 2026 report, published September 8 and based primarily on Q2 data, shows a market with improving activity but softer real pricing.

Across Southwest Florida:

  • Single-family sales increased approximately 14% year over year to about 5,600 sales.
  • Condo sales rose approximately 17% to about 1,320 sales.
  • Real median single-family prices declined about 4%.
  • Real median condo prices declined about 8%.
  • Lee County’s Housing Affordability Index reached 1.35 for all residential property and 1.30 for single-family homes.
  • Real median rents in Lee County declined approximately 9% year over year.

An affordability index above 1.0 indicates that a median-income household has more income than the model estimates is needed to purchase the median-priced home. That is encouraging, but it does not mean every household feels comfortable. First-time buyers, buyers with limited savings, and households carrying other debt may still find monthly payments challenging.

Mortgage rates remain a major part of that calculation. The 30-year fixed rate averaged around 6.65% in late August 2026, keeping monthly payments substantially higher than they were during the ultra-low-rate period. Even when prices soften, financing costs can limit purchasing power.

Cape Coral real estate: less inventory, but still selective

Cape Coral remains one of the most closely watched markets in Lee County. Current snapshots place the approximate median sale price near $349,900, while broader MLS reporting has shown figures closer to $362,500, depending on the property mix and reporting period.

Homes are taking roughly 99 days to sell, and inventory ranges from approximately 2.35 to 4.3 months of supply, depending on the segment.

That range matters. A well-maintained home priced correctly may attract attention quickly, while an overpriced property can remain available for months. Buyers still have time to compare homes, request repairs, review insurance costs, and negotiate credits, but they may face more competition for desirable single-family properties than they did earlier in the year.

For buyers working with Cape Coral real estate agents, the most important question is not simply, “How many homes are available?” It is:

How many comparable homes are available in the neighborhood, price range, condition, and waterfront category I actually want?

Cape Coral’s market is unusually diverse. A dry-lot inland home, a freshwater canal home, and a direct Gulf-access property may technically be in the same city, but they appeal to different buyers and behave differently in the market.

Fort Myers real estate trends show a split market

Fort Myers is also showing two different stories.

For single-family homes, the median price is above $430,000, with typical marketing times around 45 to 50 days. That suggests a comparatively leaner and more active market for well-positioned detached homes.

The broader Fort Myers market, which includes condos and other property types, is softer. The blended median is closer to $325,000, with marketing times ranging from approximately 100 to 151 days in some snapshots.

This is why broad headlines can be misleading. Someone shopping for a single-family home in a desirable Fort Myers neighborhood may experience a very different market from someone comparing older condominiums with higher association fees, insurance concerns, or upcoming assessments.

For sellers, this split makes accurate positioning essential. For buyers, it creates opportunities, especially in condo segments where sellers may be more open to price reductions, closing-cost credits, or repairs.

Waterfront values depend on access, not just the word “waterfront”

Waterfront property remains one of Cape Coral’s defining categories, but not all waterfront homes offer the same boating experience or value.

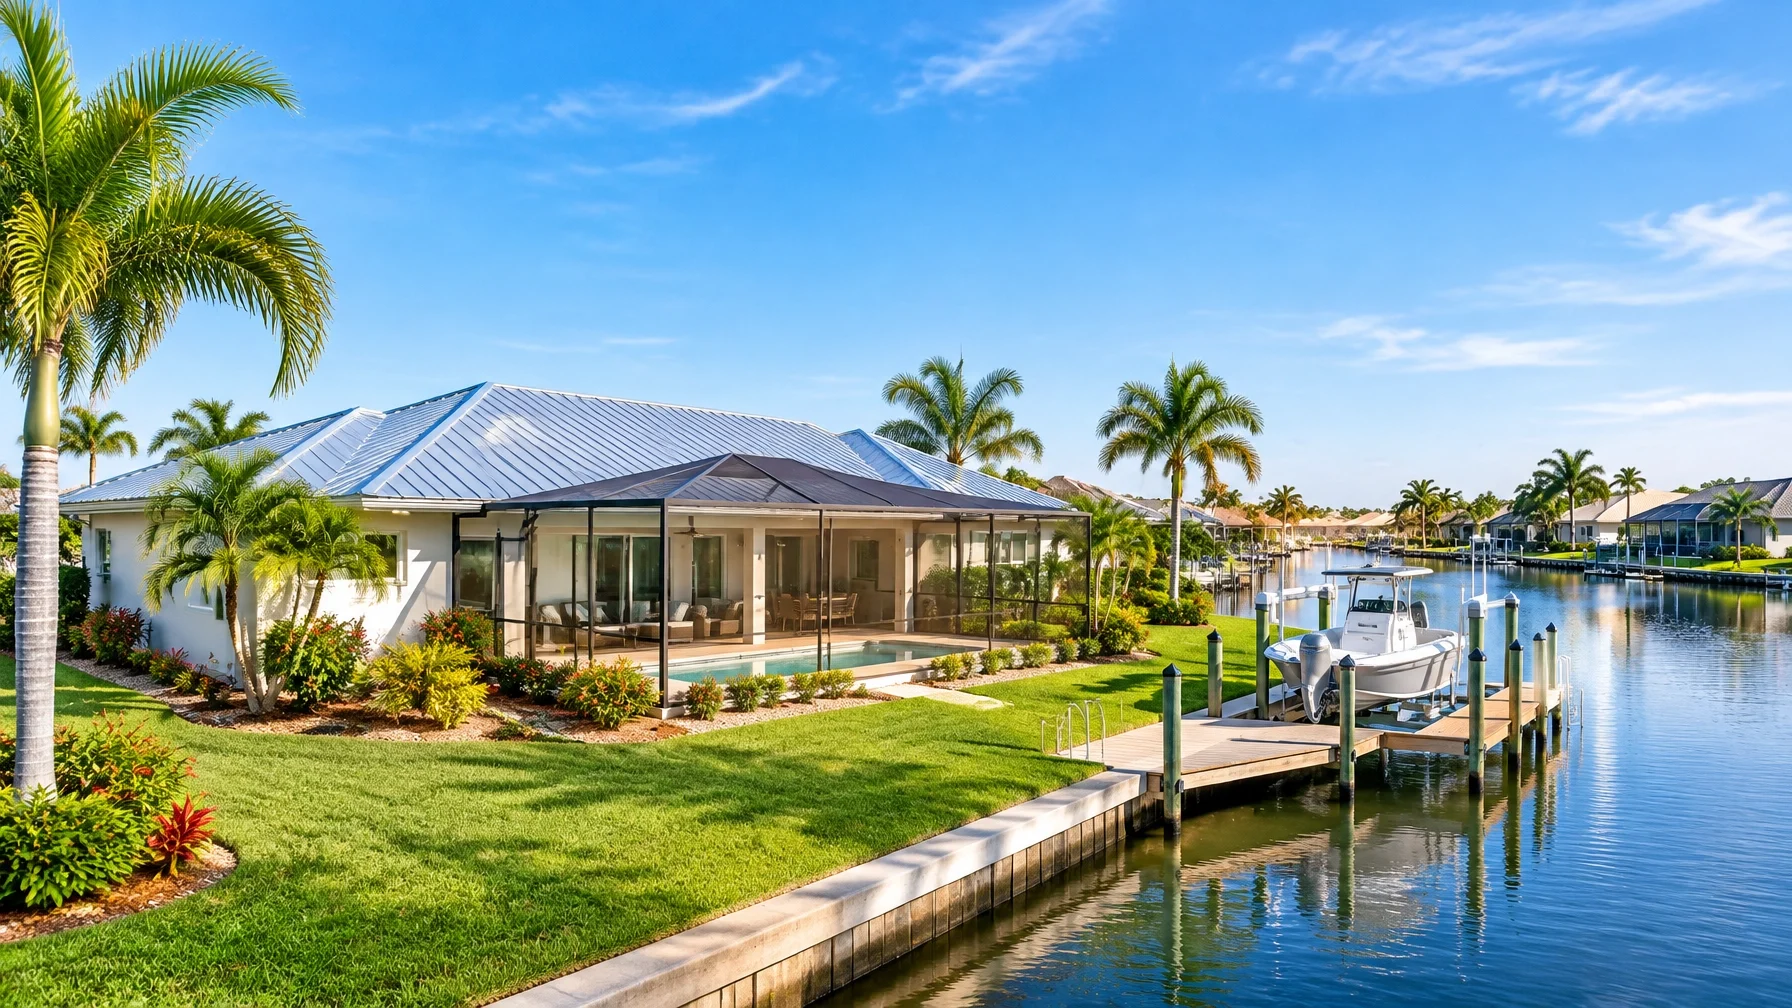
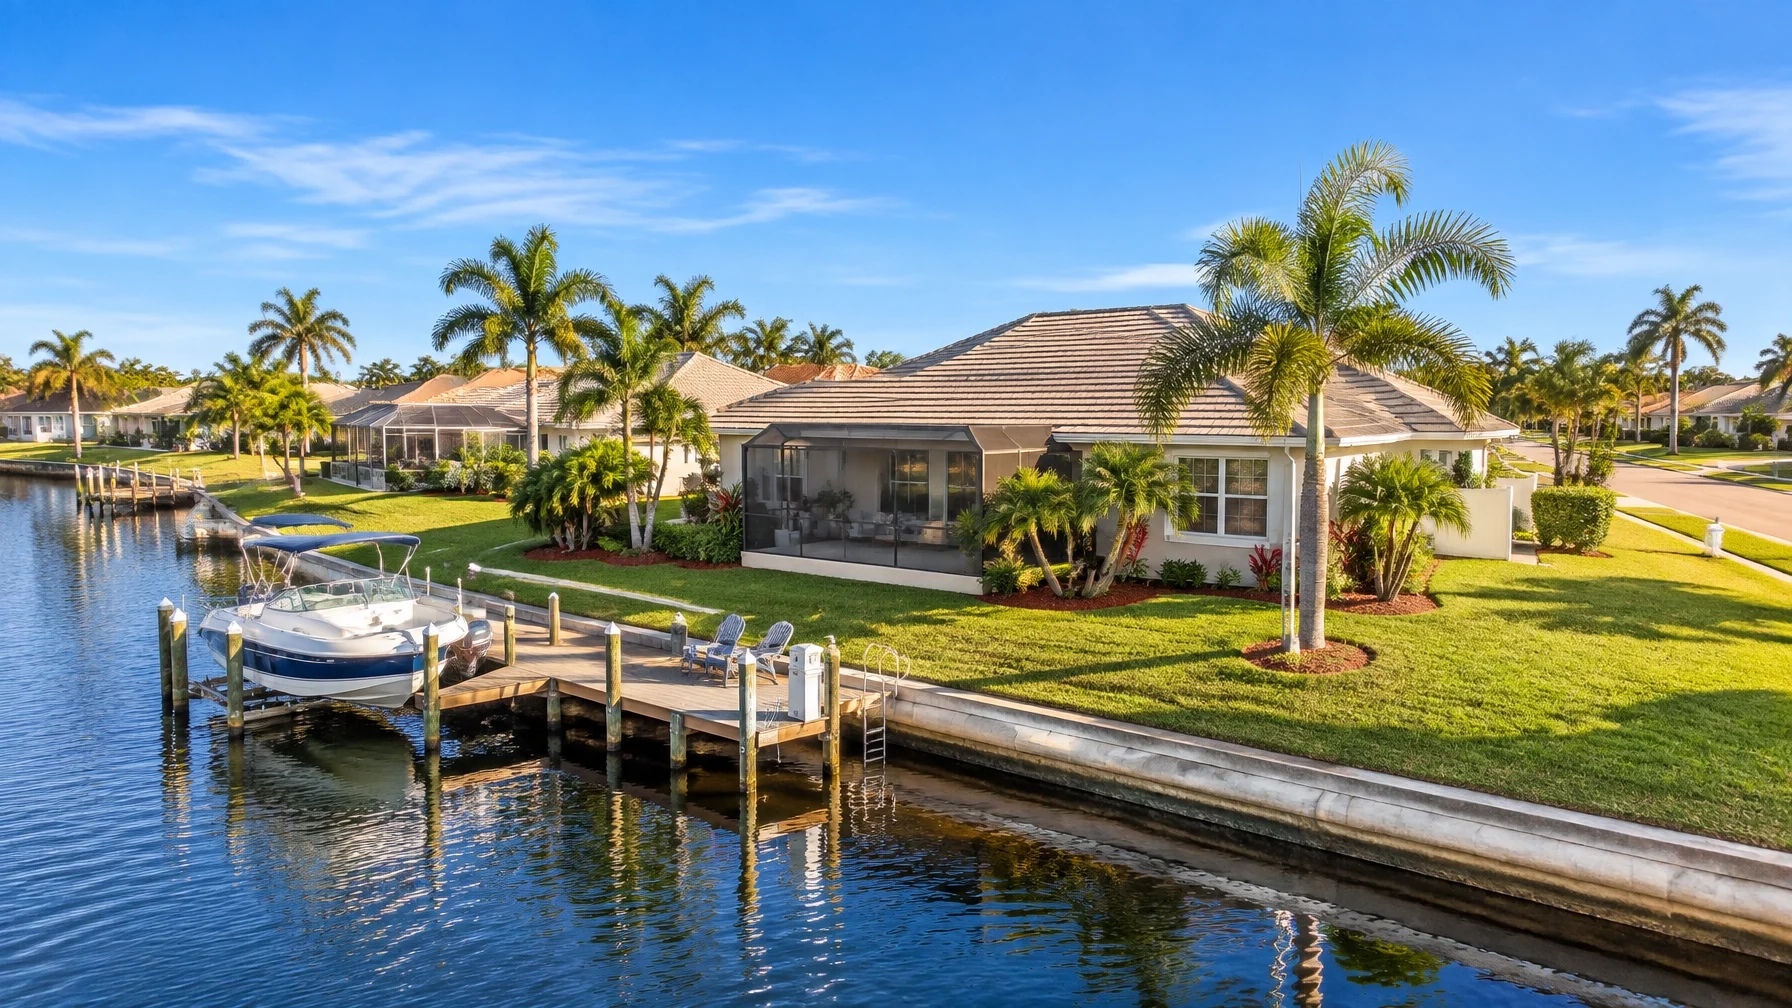
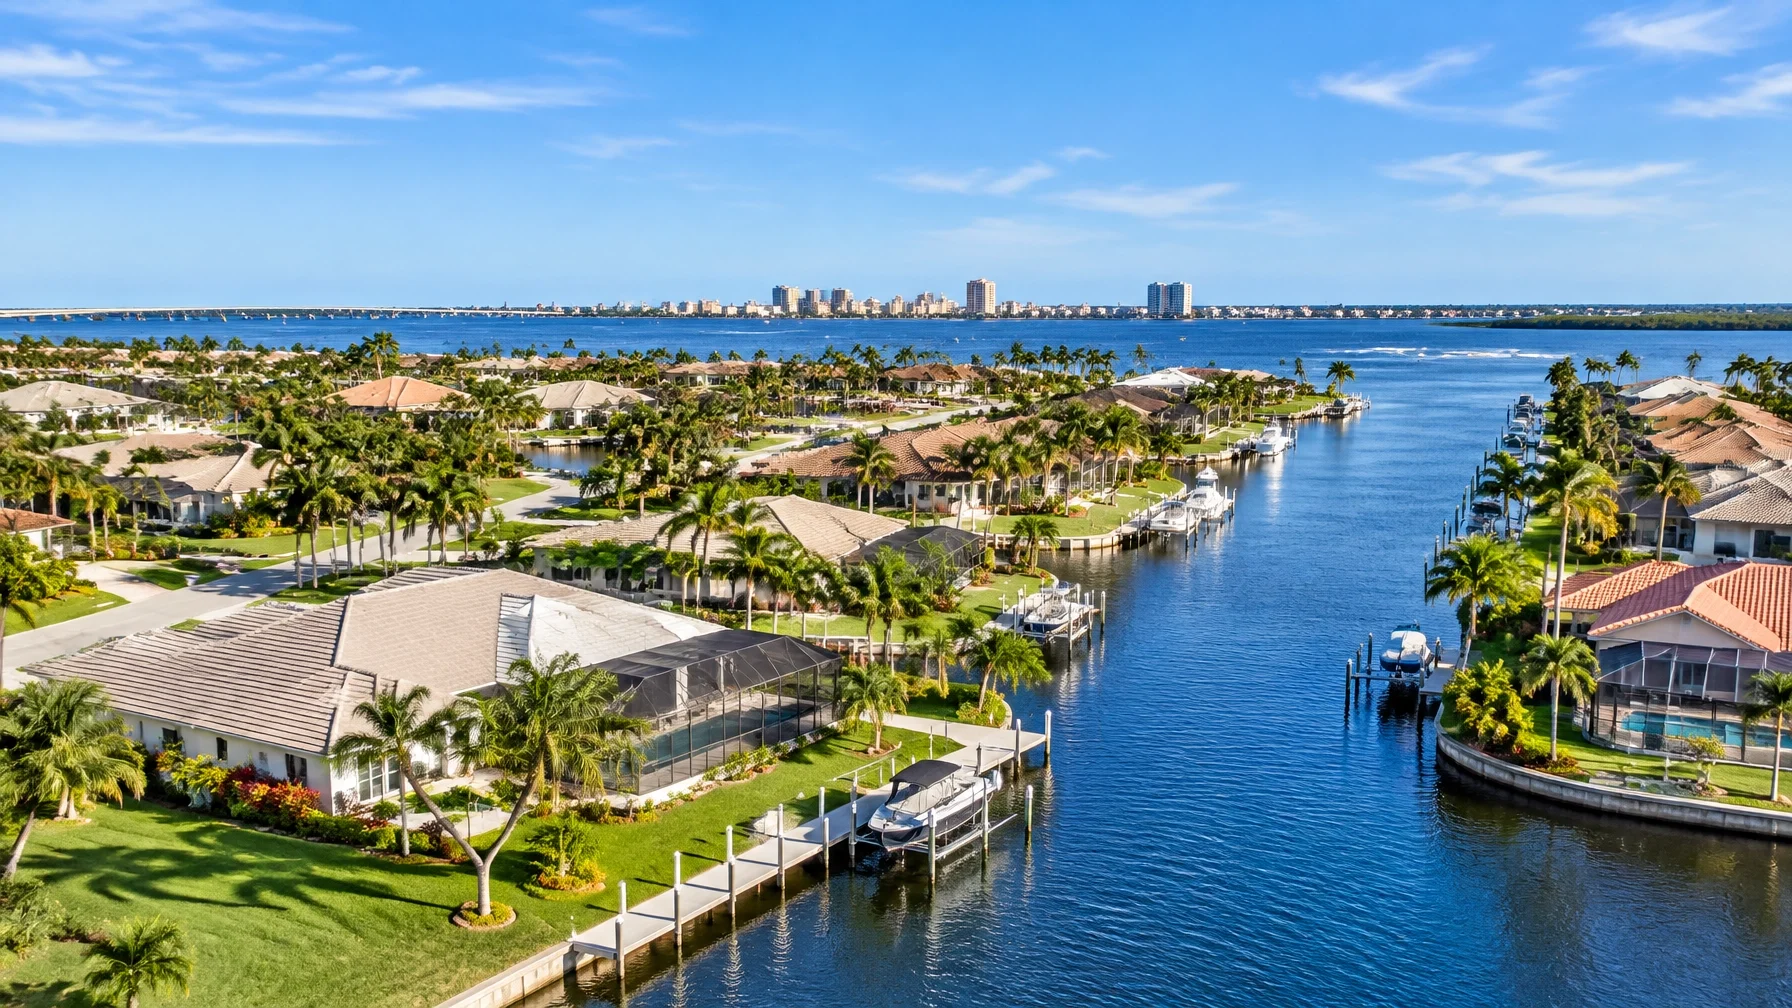
Cape Coral freshwater canal home with dock and palms

Freshwater canal homes

Freshwater canal properties generally offer attractive views, fishing, kayaking, and a peaceful setting. They are often more accessible from a pricing standpoint than Gulf-access homes.

Current snapshots place the median for freshwater canal homes near $465,000, although the actual value depends on the home’s condition, canal width, seawall, dock, pool, and neighborhood.

These homes can appeal to buyers who want the waterfront lifestyle without needing a boat route to the Gulf.

Bridge-restricted Gulf access

Bridge-restricted properties may connect to saltwater canals and offer boating access, but bridges, fixed-height clearances, canal dimensions, and route restrictions can affect the type of boat a buyer can use.

This category requires careful due diligence. “Gulf access” should never be treated as a complete description. Buyers should verify:

  • Bridge clearance and tide limitations
  • Navigation time to open water
  • Canal depth and width
  • Seawall condition
  • Dock and lift permits
  • Whether the route is suitable for the intended boat

Bridge-restricted homes may sit between freshwater and direct-access properties in pricing, but value can vary substantially by location and navigability.

Direct Gulf-access and sailboat-access homes

Direct Gulf-access homes generally command the strongest waterfront premiums because they provide a more convenient route to the Caloosahatchee River, Gulf of Mexico, and regional boating destinations.

The approximate median for direct Gulf-access homes is around $692,500. Sailboat-access properties, with fewer bridge restrictions, can command additional premiums depending on the route, lot, dock, seawall, and home quality.

For buyers searching for SWFL waterfront homes, the right comparison is not simply price per square foot. Boating access, insurance, flood exposure, seawall condition, and maintenance costs can have a major effect on long-term value.

Insurance remains the market’s biggest gatekeeper

Insurance continues to be one of the strongest forces shaping Southwest Florida real estate.

In many Lee County ZIP codes, premiums have increased approximately 60% to 100% since 2022. Average homeowner premiums are often in the $3,600 to $4,300 annual range, while properties in higher-risk flood zones can reach $12,000 or more.

That cost affects buyers in several ways:

  1. It raises the monthly payment beyond the mortgage alone.
  2. It can reduce the buyer’s approved loan amount.
  3. It may affect the affordability of older homes or homes with vulnerable roofs and building systems.
  4. It can influence resale demand and rental profitability.

Before making an offer, buyers should obtain an insurance estimate, not just a general quote for the ZIP code. Two homes a few streets apart can have very different premiums based on elevation, construction, roof age, flood zone, wind mitigation features, and replacement cost.

New construction is still adding supply

Southwest Florida continues to experience significant development activity. The region has the second-highest building permit rate in its peer group at approximately 17.10 permits per 1,000 residents.

New construction gives buyers more options, but it also creates competition for resale homes. Builders may offer rate incentives, upgrades, or closing-cost assistance that individual sellers cannot easily match.

In Cape Coral, the city repealed its 25% building permit fee discount and added a $55 floodplain review fee for applicable structural projects. Buyers of new construction and vacant land should account for permitting, site work, floodplain requirements, utilities, impact fees, and insurance, not just the advertised base price.

What this means for buyers, sellers, and investors

Buyers

Buyers still have negotiating opportunities, particularly in condos, properties with extended days on market, and homes needing updates. But waiting for a dramatic market collapse may not be the best strategy if you find the right home and can comfortably afford the payment.

Focus on the complete cost of ownership:

  • Mortgage payment
  • Homeowners and flood insurance
  • HOA or condo fees
  • Taxes
  • Utilities
  • Maintenance and reserves
  • Potential storm-related improvements

Work with a lender and local agent who can compare properties based on total monthly cost, not just list price.

Sellers

The shrinking single-family inventory is helpful, but it does not eliminate the need for realistic pricing. Buyers are still sensitive to insurance, condition, inspection findings, and monthly payment.

A strong launch strategy should include:

  • Pricing from the most relevant recent comparable sales
  • Up-to-date insurance information
  • Professional photography and presentation
  • Clear disclosure of roof, seawall, dock, and storm-related improvements
  • A plan for responding to inspection and appraisal concerns

The best listing is not necessarily the highest-priced listing. It is the home that gives buyers a compelling reason to act.

Investors

The rental market is softer, with rents down approximately 9% year over year and concessions appearing in some apartment communities. Elevated vacancies can create opportunities for tenants, but they require investors to be conservative.

Underwrite for realistic rent, vacancy, insurance, repairs, property management, and financing costs. Do not assume that past rent growth will quickly return. A property may still be a sound long-term investment, but the numbers need to work without relying on optimistic appreciation.

Data disclaimer

Market figures in this update are approximate and may vary by source, reporting period, property type, geographic boundary, and MLS methodology. Median prices, days on market, inventory, and months of supply can change significantly when the mix of single-family homes, condos, waterfront properties, and new construction changes.

The FGCU report provides valuable regional context, while local MLS snapshots and brokerage analyses may show different results for specific cities or neighborhoods. Buyers and sellers should request a current comparative market analysis and property-specific insurance estimates before making financial decisions.

Bottom line

Lee County’s single-family inventory is shrinking, with roughly 5,944 active homes and a high-teens year-over-year decline. That is a real shift, but it does not mean the buyer’s market has ended across the board.

The more accurate description is a selective, segmented market:

  • Single-family supply is tightening.
  • Condos and rentals remain softer.
  • Cape Coral waterfront values depend heavily on access.
  • Fort Myers single-family homes are outperforming the broader blended market.
  • Insurance and mortgage rates remain the primary affordability gatekeepers.
  • Sellers must price carefully, and buyers must evaluate total ownership costs.

If you are planning a move, explore available Southwest Florida properties or contact RE/MAX Realty Team for guidance from local realtors in Cape Coral and Fort Myers. With more than 100 real estate professionals serving the region, our team can help you interpret the numbers behind the headlines and make a decision based on your goals.

RE/MAX Realty Team office exterior in Southwest Florida

Read More
C7OCmnecFLH
Uncategorized
September 18, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Daily market update for September 16, 2026

Southwest Florida’s housing market is showing a more balanced pattern in late summer 2026: sales activity is improving, prices remain softer than their recent peaks, and buyers have more time to evaluate properties than they did during the pandemic-era rush.

The latest regional benchmark comes from the FGCU Regional Economic Research Institute’s September 8, 2026 Third Quarter Report. The report analyzes second-quarter 2026 results across Southwest Florida, while city-level figures below reflect approximate recent September reporting. These measures are useful for identifying direction, but they should not replace a property-specific comparative market analysis.

The regional trend: More sales, softer real prices

FGCU reports that Southwest Florida single-family home sales increased 14% year over year to approximately 5,600 sales in Q2 2026. Condominium sales rose even faster, increasing 17% to about 1,320 sales.

At the same time, real median prices declined:

  • Single-family home prices decreased approximately 4% year over year
  • Condo prices declined approximately 8%
  • Lee County’s Housing Affordability Index measured 1.35 for all residential properties
  • The Lee County single-family Housing Affordability Index was 1.30
  • Lee County real median rents declined approximately 9%

An affordability index above 1.0 generally indicates that a typical household has sufficient income to afford payments on a typical home under the report’s methodology. That does not mean every buyer feels comfortable with today’s mortgage rates, insurance costs, taxes, or association fees. It does suggest that the relationship between local incomes and home prices has improved compared with the most challenging years of the recent cycle.

The takeaway is important: demand is returning, but buyers are still price-sensitive. Sellers need to compete on condition, location, presentation, and value: not simply rely on older comparable sales.

Cape Coral market update 2026: A negotiation market

Recent September 2026 market reporting places Cape Coral’s approximate median sale price near $349,900, with homes taking roughly 99 days on market. Estimated inventory ranges from approximately 2.35 to 4.3 months of supply, depending on the source, property type, geographic boundary, and calculation method.

Some broader MLS snapshots report higher median prices or different marketing times. That variation is normal. Cape Coral includes a wide mix of newer construction, older homes, condos, freshwater canals, Gulf-access properties, inland neighborhoods, oversized lots, and homes with significant seawall or dock improvements.

For buyers, this creates opportunity:

  1. Ask for the complete history of a listing. A property that has been active for nearly 100 days may have experienced price changes, withdrawn periods, or contract cancellations.
  2. Compare like with like. A pool home on a Gulf-access canal should not be evaluated against an inland home simply because both have three bedrooms.
  3. Use inspection time carefully. Evaluate roof age, HVAC condition, drainage, windows, electrical systems, seawalls, docks, lifts, and permitting.
  4. Review total ownership costs. Insurance, flood coverage, taxes, utilities, maintenance, and HOA or condo fees can materially change affordability.

Whether you are relocating, investing, or searching for a second home, you can begin with the RE/MAX Realty Team property search and then narrow the results with local guidance.

Real estate advisor and buyers reviewing a property report in a Fort Myers home

Fort Myers real estate trends: Price matters more than speed

Approximate September reporting places the Fort Myers median sale price around $325,000. Reported marketing times range from roughly 100 to 151 days, depending on whether the source measures median days on market, average days, total listing time, or a specific segment.

Fort Myers is not one uniform market. Downtown condos, gated communities, golf properties, established single-family neighborhoods, newer construction, and homes near the river can behave differently. A well-priced home in a desirable condition may attract attention quickly, while a property with deferred maintenance or an ambitious list price can remain available for months.

For sellers, the current environment rewards preparation:

  • Set the price using recent, comparable closed sales: not the highest nearby listing.
  • Address visible repairs before professional photography and showings.
  • Highlight improvements with documentation, permits, and invoices.
  • Make insurance information available early when possible.
  • Plan for longer negotiations and potential buyer requests.
  • Review feedback quickly and be prepared to adjust if showing activity is weak.

For buyers, longer marketing times do not automatically mean a property is defective. They may indicate that the seller started too high, the home has a narrow buyer pool, or the property’s insurance, flood exposure, association rules, or repair needs require additional analysis.

Sanibel and Fort Myers Beach: Smaller markets, bigger swings

Sanibel and Fort Myers Beach are smaller coastal markets where a limited number of monthly closings can move the median significantly. Recent estimates place Sanibel near $856,000 and Fort Myers Beach near $510,000, but these figures should be treated as directional rather than definitive.

A single month may include an unusual concentration of luxury homes, condos, distressed properties, new construction, or storm-repaired residences. That can make month-to-month comparisons misleading. Buyers and sellers in these communities should typically examine a longer lookback period and separate waterfront, non-waterfront, condo, and single-family results.

Coastal property also requires a broader due-diligence process. Beyond price and condition, evaluate:

  • Flood zone and elevation information
  • Wind and flood insurance availability
  • Storm-hardening features
  • Rental and occupancy restrictions
  • Condo reserves and special assessments
  • Access to beaches, docks, and marinas
  • Repair permits and post-storm documentation
  • Rebuilding or renovation limitations

SWFL waterfront homes: “Waterfront” is not one category

Cape Coral waterfront home with a private dock and boat lift

Buyers searching for SWFL waterfront homes should define the type of water access before comparing properties. The difference can affect price, insurance, boating utility, maintenance, and resale demand.

Freshwater canal

Freshwater canal properties may provide attractive views, fishing, kayaking, and a private dock setting. They generally do not offer direct navigation to the Gulf. These homes can be a strong fit for buyers who value water views and outdoor living more than offshore boating.

Bridge-restricted Gulf access

Some canals connect toward the Gulf but include bridges that limit boat height or route flexibility. This may work well for smaller boats, kayaks, or buyers who do not need unrestricted passage. However, the access should be measured rather than described casually as “Gulf access.”

Direct Gulf or sailboat access

Properties with more direct navigation can command a premium, especially when they offer favorable boating routes, seawall condition, dock quality, and sufficient water depth. Buyers should still verify bridge clearances, tidal conditions, canal dimensions, navigability, and the practical route to open water.

In every category, inspect the seawall, dock, pilings, boat lift, electrical service, permits, flood exposure, and insurance requirements. Also confirm whether short-term rentals are permitted by the city, county, HOA, condominium association, or applicable deed restrictions. A waterfront purchase is a lifestyle decision: but it is also an infrastructure and risk-management decision.

Practical guidance for today’s market

For buyers: Get financing, insurance estimates, and an ownership-cost review before making an offer. Current conditions may provide negotiating room, but the best opportunities are not always the cheapest listings. A well-maintained property with documented improvements may offer better long-term value than a lower-priced home requiring immediate repairs.

For sellers: Pricing correctly at launch is still one of the most effective strategies. Buyers have more choices, and they are increasingly comparing condition, monthly costs, insurance, and resale potential. Your listing should make those answers easy to find.

For investors: Do not underwrite solely from projected rent. Lee County rents have softened approximately 9% according to FGCU’s Q2 findings. Model realistic vacancy, repairs, insurance, taxes, management, utilities, HOA restrictions, and changing short-term rental rules. A property that works only under peak-season assumptions may not be a resilient investment.

Data disclaimer

This update is for general informational purposes and is not an appraisal, valuation, investment recommendation, or guarantee of future performance. Figures vary by source, timeframe, property type, data set, and geographic boundary. Regional FGCU statistics reflect Q2 2026 data reported in September 2026; city-level figures are approximate recent market estimates and may change as additional transactions are recorded. Always consult a licensed real estate professional, lender, insurance agent, inspector, attorney, and other appropriate specialists for advice related to a specific property or transaction.

The bottom line

The September 16, 2026 Southwest Florida market is neither a runaway seller’s market nor a reason for buyers to wait indefinitely. Sales are recovering, prices remain under pressure in several segments, and affordability has improved: but property-specific costs and condition matter more than broad headlines.

Cape Coral and Fort Myers buyers can use today’s added negotiating room to perform better due diligence. Sellers can compete by pricing realistically and presenting their homes exceptionally well. Investors should focus on durable cash flow rather than optimistic rent assumptions. And anyone considering waterfront property should verify exactly what “waterfront” means before making a decision.

For local guidance from experienced cape coral real estate agents and realtors Cape Coral buyers and sellers can rely on throughout Lee County, learn more about the RE/MAX Realty Team or contact the office.

Read More
rXLMTCrWiWm
Uncategorized
September 17, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Daily Southwest Florida market update for September 17, 2026

Southwest Florida’s real estate market is entering fall with a more balanced, but increasingly divided, pattern. The headline is not simply “buyers’ market” or “sellers’ market.” Instead, conditions are separating by property type, location, price range, and insurance profile.

Single-family inventory is tightening in several parts of Cape Coral and Fort Myers, while condos and townhomes: particularly in Fort Myers and the beach communities: continue to offer buyers more selection and negotiating room. At the same time, insurance conditions are showing signs of relief, and seasonal activity is beginning to build as snowbirds, second-home buyers, and out-of-state shoppers return to Southwest Florida.

Here is today’s hyper-local look at Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, waterfront properties, luxury real estate, and investment opportunities.

Cape Coral market update 2026: A mid-$300,000s market with more variation

Cape Coral remains one of the most active and diverse residential markets in Lee County. Buyers can choose from inland starter homes, newer construction, gulf-access properties, pool homes, and high-end waterfront estates: but those categories are not moving at the same pace.

The current Cape Coral snapshot places the median sale price roughly between $350,000 and $362,500, with homes taking approximately 99 days to sell. That extended marketing time gives buyers room to compare properties, review inspections, and negotiate when a home has been sitting or has already experienced a price reduction.

However, the citywide median does not tell the full story. A well-maintained home in southwest Cape Coral with a newer roof, screened lanai, pool, and gulf access may attract significantly more attention than an older inland property with deferred maintenance.

Cape Coral and Fort Myers homes representing different property types and market conditions

For buyers, the most important comparison is not just the list price. Review:

  • Roof age and permit history
  • Flood zone and elevation
  • Homeowners insurance availability and cost
  • Seawall, dock, and boat-lift condition
  • Pool and enclosure repairs
  • Distance to open water
  • Potential assessment or maintenance expenses

Experienced Cape Coral real estate agents can help buyers compare the total cost of ownership: not just the number displayed in the listing.

Fort Myers real estate trends: Single-family homes are holding firmer

Fort Myers is showing a different dynamic from the broader Cape Coral market. Single-family homes are generally pricing above $430,000, with tighter inventory in desirable neighborhoods and continued demand for move-in-ready properties.

Homes near downtown Fort Myers, the river district, medical facilities, established neighborhoods, golf communities, and major transportation routes may see stronger competition than the regional average suggests. Buyers should be prepared to act when the right property appears, particularly if it is well-priced and has strong storm-resilience features.

That does not mean buyers should skip due diligence. A tighter segment still requires inspections, insurance research, flood-zone review, and careful evaluation of the roof, electrical systems, HVAC, plumbing, and permitting history.

For sellers, the message is equally clear: tighter inventory helps, but it does not eliminate the need for strategic pricing. Today’s buyers are comparing monthly payments, insurance premiums, taxes, maintenance, and utility costs. The best realtors in Cape Coral and Fort Myers will price a home against current competition and recent comparable sales: not against peak-market expectations.

The market is splitting by property type

One of the most important trends this week is the difference between single-family homes and condos or townhomes.

Single-family inventory has tightened from earlier 2026 levels in several parts of Lee County. Condo and townhome inventory remains more available, especially in Fort Myers, Sanibel, Fort Myers Beach, and other coastal areas. That creates more negotiating room for condo buyers, who may be able to request repairs, closing credits, price adjustments, or additional time for association document review.

Buyers should pay close attention to:

  • Condo association reserves
  • Pending or recent special assessments
  • Master insurance coverage
  • Flood and wind policies
  • Monthly association fees
  • Rental and pet restrictions
  • Post-storm repairs and building updates

A lower condo price does not necessarily mean a lower monthly cost. Association fees, insurance changes, and assessments can substantially affect affordability.

Insurance relief may improve buyer confidence: but get a quote first

Florida’s insurance market is providing some welcome relief. According to Citizens Property Insurance, approved 2026 rates reduce homeowners multiperil policies by an average of 8.8% statewide. Citizens’ wind-only policies are seeing an average reduction of approximately 5.5%.

For example, an 8.8% reduction on a $3,500 annual homeowners premium would equal approximately $308 in annual savings, or about $26 per month. That may not transform a buyer’s budget, but it can make a noticeable difference when combined with mortgage payments, taxes, utilities, and maintenance.

The lower rates may also help improve buyer confidence as the fall market begins. Still, the 8.8% figure is a statewide average: not a guarantee for every property. Actual premiums depend on the home’s age, roof, construction, location, flood zone, wind mitigation features, claims history, coverage limits, and insurer availability.

Buyers should request an insurance quote before making an offer whenever possible. Sellers can also strengthen their listing by providing documentation for roof replacements, storm shutters, impact windows, elevation improvements, and wind-mitigation inspections.

FGCU report: Southwest Florida is more balanced, but not uniform

The FGCU Regional Economic Research Institute’s Third Quarter 2026 report describes a market that continues to adjust after the pandemic-era surge and major storms.

The report found that during the second quarter:

  • Single-family home sales increased 14% year over year to approximately 5,600 sales.
  • Condominium sales increased 17% to about 1,320 sales.
  • Real median single-family prices declined 4% year over year.
  • Real median condo prices declined 8% year over year.
  • Active listings represented approximately 2.72% of total housing units, down from 3.38% one year earlier.
  • Lee County’s overall Housing Affordability Index reached 1.35, while single-family affordability measured 1.30.

The report supports a more balanced regional interpretation: but “balanced” does not mean every neighborhood is behaving the same way. The practical takeaway is to evaluate the specific property type and submarket rather than relying on a single Southwest Florida statistic.

Sanibel and Fort Myers Beach: Coastal lifestyle, detailed analysis

Sanibel and Fort Myers Beach continue to attract buyers looking for second homes, vacation properties, retirement residences, and rental opportunities. These markets are highly property-specific, particularly as buyers evaluate post-storm repairs, elevation, rebuilding standards, and association finances.

Sanibel and Fort Myers Beach coastal homes with calm Gulf waters

Before purchasing, review:

  • Repair permits and construction documentation
  • Roof age and storm-resistance features
  • Flood-zone and elevation information
  • Condo reserves and special assessments
  • Short-term rental rules
  • Parking and access
  • Insurance availability and deductibles

Coastal buyers should also understand that lifestyle value and investment value are not always the same. A property may be perfect as a personal retreat but less attractive as a rental after insurance, management, repairs, vacancy, and association costs are included.

Waterfront homes remain in demand

Interest in SWFL waterfront homes remains strong as buyers seek boating access, private docks, pools, outdoor living, and proximity to the Gulf. Yet waterfront properties require additional diligence.

A buyer should evaluate canal depth and width, bridge clearance, time to open water, seawall condition, dock permits, lift capacity, flood exposure, and the cost of maintaining waterfront infrastructure.

A property with direct gulf access and a newer seawall may command a premium, while a home with limited access or aging infrastructure may require a larger ownership budget. Experienced local guidance is especially valuable when comparing waterfront homes that appear similar on the surface.

Luxury real estate remains a buyer’s market

The market above $1 million continues to favor buyers, with approximately:

  • 5.9 months of supply in Cape Coral
  • 14 months of supply in Fort Myers

That gives qualified buyers more leverage to negotiate price, furnishings, closing costs, repairs, or other terms. Sellers in this segment need exceptional presentation, complete property information, professional photography, and realistic pricing.

Luxury buyers should still move quickly when a rare property appears. Deep-water access, a unique lot, exceptional construction, or a highly desirable location may justify a premium even when the overall luxury segment has substantial supply.

Investors should underwrite conservatively this fall

Investors may find better negotiating conditions in condos, townhomes, and selected waterfront properties, but the numbers must work after all expenses.

Before purchasing, calculate:

  1. Realistic long-term or seasonal rental income
  2. Insurance, taxes, utilities, and association fees
  3. Property management and maintenance
  4. Vacancy and turnover
  5. Storm-related improvements
  6. Rental restrictions and local regulations
  7. Likely resale demand

The fall season may bring more rental and second-home activity, but investors should not assume that seasonal demand will eliminate all vacancy or expense risks.

Buyer and seller strategy for the fall kickoff

Southwest Florida real estate agent meeting with buyers on a sunny canal-side lanai

Buyers

  • Get financing or proof of funds organized before touring seriously.
  • Request an insurance quote early.
  • Compare single-family homes separately from condos and townhomes.
  • Review flood, roof, seawall, and storm documentation.
  • Use longer marketing times to negotiate thoughtfully.
  • Be ready to act when a correctly priced property appears.

Sellers

  • Price against current competition, not 2022 or 2023 expectations.
  • Consider listing in late September if the home is prepared and priced accurately.
  • Highlight insurance-related improvements and storm-resilience features.
  • Provide permits, inspection reports, and upgrade documentation.
  • Consider credits or repairs when they improve the overall net result.
  • Review showing activity and buyer feedback quickly.

For sellers deciding between late September and January, waiting may bring more snowbird traffic: but it also means entering a busier competitive environment. Listing in late September can allow a prepared home to reach early seasonal buyers before inventory expands. The right choice depends on the property, condition, pricing strategy, and seller’s timeline.

The takeaway

The September 17, 2026 market is balanced: but it is not uniform. Cape Coral’s median sale price is approximately $350,000 to $362,500, with homes taking about 99 days to sell. Fort Myers single-family homes above $430,000 are showing firmer conditions, while condos and townhomes offer more supply and negotiating room, especially in Fort Myers and the beach communities.

Insurance relief is a positive development, with Citizens’ average homeowners multiperil rate decrease of 8.8%, but every buyer should obtain a property-specific quote before making an offer. FGCU’s latest report reinforces the broader message: sales are improving, affordability has strengthened, and Southwest Florida is moving toward a more balanced market: though each neighborhood and property type tells a different story.

Whether you are buying, selling, renting, or investing, the best strategy is hyper-local. Start with the SWFL property search, or contact RE/MAX Realty Team for guidance from experienced professionals serving Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding communities.

Read More
WJXM3EXH1dS
Uncategorized
September 16, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Daily Southwest Florida market update for September 15, 2026

Southwest Florida’s real estate market is settling into a more balanced rhythm as late summer transitions into early fall. Buyers have more room to negotiate than they did during the market’s busiest years, while well-priced homes: especially in desirable locations: continue to attract serious attention.

Across the region, inventory is down approximately 25% year over year, and the overall market is near 4.9 months of supply, generally considered neutral or balanced. That means neither buyers nor sellers have complete control. The strongest opportunities are increasingly found at the neighborhood, property-type, and price-band level.

Here is what today’s market looks like in Cape Coral, Fort Myers, Sanibel, and Fort Myers Beach.

Cape Coral market update 2026: Value and negotiation are both important

Cape Coral remains one of the most watched markets in Southwest Florida because it offers a broad range of housing: from inland starter homes and newer construction to gulf-access properties and luxury waterfront estates.

The current Cape Coral snapshot shows:

  • Median sale price near $350,000
  • Approximately 99 days on market
  • More negotiating flexibility than during the peak seller-driven market
  • A particularly varied market based on location, construction year, flood zone, and water access

The citywide median does not tell the entire story. Buyers may find meaningful differences between neighborhoods such as northeast Cape Coral, southwest Cape Coral, the Yacht Club area, and gulf-access canal communities.

For example, a home with a newer roof, updated storm protection, a screened lanai, and direct boating access may command a substantial premium over a similar-sized inland property. Buyers comparing homes should look beyond the list price and evaluate insurance costs, seawall condition, dock improvements, assessments, and the time required to reach open water.

Contemporary Cape Coral home beside a canal with a private dock

What this means for Cape Coral buyers

The roughly 99-day market provides buyers with an opportunity to be deliberate. You may have time to compare several properties, request inspections, and negotiate repairs or credits rather than making an immediate offer in a multiple-offer situation.

That does not mean every home is negotiable. Properties that are priced correctly and presented well can still move quickly. The greatest leverage is often found with homes that have been sitting on the market, experienced a price reduction, or need updates that are clearly reflected in the asking price.

Working with experienced Cape Coral real estate agents can help you distinguish between a true opportunity and a property that appears inexpensive because of insurance, deferred maintenance, or costly waterfront infrastructure.

Fort Myers real estate trends: Tighter inventory and stronger competition

Fort Myers is showing a somewhat different pattern. Single-family homes are generally pricing above $430,000, and inventory is tighter than in parts of Cape Coral.

This creates a more competitive environment for desirable Fort Myers homes, particularly those near:

  • Established residential neighborhoods
  • Downtown Fort Myers and the river district
  • Major employment centers
  • Medical facilities and shopping
  • Golf communities
  • Convenient routes toward the beaches and airport

Buyers in Fort Myers should be prepared to act when a home checks the right boxes. A property that is move-in ready, appropriately priced, and located in a high-demand area may not remain available as long as the broader regional average suggests.

At the same time, buyers should not skip due diligence simply because inventory is tighter. A professional inspection, insurance review, flood-zone evaluation, and careful examination of the property’s permitting history remain essential.

What this means for Fort Myers sellers

Sellers benefit from tighter inventory, but pricing still matters. Buyers are more informed and are comparing monthly payment costs, insurance premiums, taxes, and maintenance expenses: not just the listing price.

A home that is priced too aggressively may sit, while a similar property nearby attracts attention. Strategic preparation, accurate pricing, professional photography, and a clear explanation of upgrades can help a Fort Myers seller stand out.

The best realtors in Cape Coral and Fort Myers will evaluate recent comparable sales, active competition, pending transactions, and the specific characteristics that influence value in the immediate neighborhood.

Waterfront homes remain highly desirable: but the details matter

Demand for SWFL waterfront homes continues to be closely tied to lifestyle. Buyers are looking for boating access, outdoor living, private docks, pools, and proximity to the Gulf of Mexico.

However, waterfront property values are not determined by the view alone. Buyers should examine:

  • Canal width, depth, and bridge clearance
  • Distance to open water
  • Seawall age and condition
  • Dock and lift permits
  • Pool enclosure and storm damage history
  • Flood zone and elevation information
  • Homeowners insurance availability and cost
  • Rental restrictions, if the property will be an investment

In Cape Coral, gulf-access homes may command a significant premium compared with inland properties. In Fort Myers, Sanibel, and Fort Myers Beach, coastal proximity can also influence pricing, insurance requirements, rebuilding standards, and rental regulations.

Sanibel and Fort Myers Beach: Lifestyle value with added due diligence

Sanibel and Fort Myers Beach continue to attract buyers seeking coastal living, second homes, vacation properties, and investment opportunities. These markets are highly property-specific and should not be evaluated using citywide averages alone.

Buyers should pay close attention to:

  • Post-storm repairs and documentation
  • Elevation and flood-resilience features
  • Roof age and construction standards
  • Condo association reserves and special assessments
  • Short-term rental rules
  • Local permitting requirements
  • Access, parking, and storm-related evacuation considerations

For buyers seeking a vacation home or rental property, projected income should be based on realistic occupancy, seasonal demand, management fees, insurance, repairs, utilities, and applicable local regulations.

A coastal property can be an excellent lifestyle purchase, but the financial analysis needs to be comprehensive. A local agent who regularly works in these communities can help coordinate inspections, insurance questions, rental research, and contract timelines.

Sanibel and Fort Myers Beach coastal lifestyle with calm Gulf water and sea oats

Luxury real estate: A buyer’s market above $1 million

The luxury market is behaving differently from the mainstream market. Properties priced above $1 million are currently in a buyer’s market, with approximately:

  • 5.9 months of supply in Cape Coral
  • 14 months of supply in Fort Myers

The longer supply period gives qualified luxury buyers more negotiating leverage. Sellers may need to consider price adjustments, closing-cost credits, furnishings, repair allowances, or other terms that help a property stand out.

Luxury buyers should still move carefully. The right property may be rare, even when the overall segment has substantial inventory. A one-of-a-kind waterfront setting, deep-water access, exceptional construction, or proximity to the beach may justify a premium that broad market statistics cannot capture.

For sellers, presentation is especially important. High-end buyers expect detailed property information, strong visual marketing, accurate disclosures, and a clear explanation of improvements and ownership costs.

What investors should watch this fall

Investors evaluating Cape Coral and Fort Myers should focus on net performance rather than headline rent or purchase price.

Important questions include:

  1. What is the realistic long-term or seasonal rental demand?
  2. Are short-term rentals permitted in the city, neighborhood, or condominium?
  3. How do insurance and property taxes affect the monthly budget?
  4. Will the property require flood-related improvements or storm upgrades?
  5. What is the likely resale audience?
  6. How much vacancy should be assumed?
  7. Are projected repairs and management costs fully included?

The current balanced market may create more opportunities to negotiate, but investors still need conservative numbers. A lower purchase price does not automatically create a good investment if insurance, maintenance, or rental restrictions reduce the property’s income potential.

Practical advice for buyers and sellers in mid-September

Buyers

  • Get financing or proof of funds organized before touring seriously.
  • Compare total monthly ownership costs, not just sale prices.
  • Ask for insurance estimates early.
  • Review flood, roof, seawall, and storm-related information.
  • Use the late-summer and early-fall season to negotiate thoughtfully.
  • Be ready to act when a well-priced property appears.

Sellers

  • Price against current competition, not last year’s peak.
  • Address visible maintenance issues before listing.
  • Highlight storm protection, updates, permits, and energy-efficient features.
  • Prepare for questions about insurance and flood zones.
  • Consider credits or flexible terms when they improve the net result.
  • Review showing activity and feedback quickly.

For current listings throughout Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding communities, visit the SWFL property search. You can also contact RE/MAX Realty Team for neighborhood-level guidance.

The takeaway

The September 2026 Southwest Florida market is balanced, but it is not uniform. Cape Coral offers more time and negotiating room, with a median sale price near $350,000 and homes averaging about 99 days on market. Fort Myers single-family homes above $430,000 are seeing tighter inventory and stronger competition. Coastal markets require additional due diligence, while the luxury segment currently gives buyers meaningful leverage.

The best strategy is hyper-local: compare the right neighborhood, property type, price range, and condition: not just broad market headlines. Whether you are buying, selling, renting, or investing, experienced local guidance can help you turn today’s market conditions into a better real estate decision.

Read More
rNR6H1lPJa8-740×480-1-740×480
Uncategorized
September 15, 2026by Penny

Hyper-Local Cape Coral & Fort Myers Real Estate Insights

Daily market read for Monday, September 14, 2026

The Cape Coral and Fort Myers real estate markets are active, but buyers and sellers are not experiencing the same conditions everywhere. Neighborhood, property type, waterfront access, insurance costs, HOA fees, and overall condition are having more influence than broad citywide averages.

The latest local figures available as of September 12 place Cape Coral’s median sale price near $349,900, with homes spending approximately 99 days on the market. Fort Myers is showing a median sale price near $325,000, with marketing times close to 100 days.

Those numbers are useful starting points, but they do not tell the full story. A direct Gulf-access home in Cape Coral, a downtown Fort Myers condominium, a home in the Yacht Club area, and a property in an inland subdivision may all be responding to different buyer demand.

Southwest Florida market conditions this month

The latest regional data points to a market that is stabilizing rather than surging.

The FGCU Regional Economic Research Institute reported improving sales activity across the three-county coastal region, with approximately:

  • 14% year-over-year growth in single-family home sales
  • 17% year-over-year growth in condominium sales
  • A 4% decline in the real median single-family sale price
  • An 8% decline in the real median condominium sale price
  • A Lee County Housing Affordability Index near 1.35 for all residential properties
  • A real median rent decline of approximately 9% year over year

In practical terms, more transactions are taking place, but buyers remain selective. Sellers are no longer able to rely on limited competition or rapid price appreciation to support an ambitious asking price.

Mortgage rates are also keeping buyers focused on the complete cost of ownership. Freddie Mac’s weekly mortgage survey reported a 30-year fixed average near 6.76% for the week ending September 10, 2026. Insurance, property taxes, flood coverage, HOA fees, and maintenance can significantly change the monthly payment beyond principal and interest.

Cape Coral market update 2026: waterfront access is the dividing line

Cape Coral remains one of the most varied real estate markets in Southwest Florida. Citywide statistics combine several very different categories, including inland homes, freshwater canal properties, bridge-restricted Gulf-access homes, and direct sailboat-access residences.

Freshwater canal homes

Freshwater canal properties continue to appeal to buyers who want water views, a dock, kayaking, fishing, or an attractive outdoor setting without paying the full premium associated with direct Gulf access.

However, buyers should verify the canal’s width, depth, seawall condition, dock configuration, and connection to the broader canal system. “Waterfront” does not automatically mean that a property offers practical boating access to the Gulf.

Gulf access with bridges

Some Cape Coral homes provide saltwater access but require travel beneath one or more bridges. This may work well for buyers using smaller boats, pontoons, or other vessels that fit within the available clearance.

When comparing two homes advertised as Gulf access, ask:

  • How many bridges are along the route?
  • What are the bridge clearances?
  • Is the route navigable at typical tide levels?
  • How long is the trip to open water?
  • Are there locks, canals, or other restrictions?
  • What are the current conditions of the seawall, dock, and lift?

Direct Gulf and sailboat access

Direct Gulf-access and sailboat-access homes typically command the highest waterfront premiums because they offer a more convenient route to open water and may accommodate larger vessels.

Current broad pricing ranges reported for Cape Coral include approximately:

Property category General pricing range
Freshwater canal homes Mid-$400,000s and up
Gulf access with bridge restrictions Approximately $600,000–$650,000
Direct Gulf or sailboat access Approximately $700,000–$755,000 and up
Premium riverfront or extensively upgraded homes $1 million or more

These figures are not appraisals. A home’s value can change substantially based on renovation quality, canal exposure, bridge clearance, seawall age, dock and lift condition, flood zone, insurance availability, and distance to the Caloosahatchee River.

Cape Coral canal-front home with dock and boat access

Cape Coral neighborhoods to watch

Yacht Club area

The Yacht Club area and surrounding 33904 properties continue to attract buyers who value established neighborhoods, river access, and proximity to Cape Coral amenities.

At the same time, many homes in the area are older. Buyers are paying close attention to roofs, electrical systems, storm history, permits, seawalls, flood insurance, and the quality of renovations.

A renovated direct-access home may draw strong interest, while an older property requiring significant work needs to be priced according to its actual condition: not simply its waterfront location.

Cape Harbour

Cape Harbour remains a distinct lifestyle destination, with marina amenities, waterfront dining, and a more defined community atmosphere. Recent neighborhood-level reporting placed the median list price near $509,000, although individual properties vary considerably.

Buyers should evaluate the specific view, building, association fees, rental restrictions, dock rights, and relationship to the marina. Investors should also test projected rental income against management costs, insurance, vacancy, and association rules.

Pelican

Pelican includes a mix of inland, canal-front, and Gulf-access homes. Recent reporting placed the neighborhood’s median near $535,000, but that figure covers a wide range of properties.

The most relevant comparable sale for a Gulf-access home is usually another Gulf-access home with a similar boating route: not simply any property within the same ZIP code.

Fort Myers real estate trends: a segmented market

Fort Myers offers a different mix of housing from Cape Coral. Buyers can choose among established single-family neighborhoods, downtown condominiums, gated communities, golf properties, townhomes, and newer developments near major roads and employment centers.

Recent local reporting places Fort Myers single-family median sale prices in the general $430,000–$445,000 range for certain tracked segments, with approximately 4.3 to 4.5 months of supply. Broader citywide statistics, which include more property types and geographic areas, show a median closer to $325,000 and marketing times around 100 days.

This difference demonstrates why buyers should avoid relying on one statistic without checking the property category behind it.

Downtown Fort Myers and riverfront condominiums

Downtown Fort Myers attracts buyers who value restaurants, cultural events, historic character, river views, and a more walkable lifestyle.

Condominiums may offer a lower entry price than waterfront single-family homes, but the monthly ownership cost can vary significantly. Before purchasing, review:

  • Association reserves and financial statements
  • Current or planned special assessments
  • Master insurance and individual unit coverage
  • Roof and building maintenance responsibilities
  • Rental and pet restrictions
  • Flood exposure and deductibles
  • Parking and storage arrangements

The reported decline in real median condo prices may create opportunities, but a lower purchase price does not necessarily mean a lower total cost.

Established Fort Myers neighborhood with mature landscaping and well-maintained homes

Golf and gated communities

Golf communities continue to attract seasonal residents, retirees, and buyers looking for organized amenities. However, costs vary widely between communities.

Buyers should investigate mandatory or optional memberships, club dues, food and beverage minimums, HOA fees, capital reserves, rental restrictions, and future assessment risk. A home with a lower asking price may still have a high monthly carrying cost.

What buyers should do now

The current market gives buyers more time to compare properties than they had during the peak years. That does not mean every home is easy to negotiate. Well-priced, move-in-ready properties with manageable insurance profiles can still attract serious attention.

Buyers should:

  1. Obtain a current preapproval before making offers.
  2. Compare recent closed sales, not just active listings.
  3. Request insurance estimates early.
  4. Review roof age, permits, storm repairs, and major systems.
  5. Investigate seawalls, docks, lifts, and boating routes on waterfront properties.
  6. Review HOA or condominium documents during the due diligence period.
  7. Calculate the full monthly cost, including taxes, insurance, fees, and maintenance.
  8. Pay attention to cumulative days on market and repeated price reductions.

For buyers relocating from another state or country, local conditions can be especially difficult to evaluate remotely. A property may look attractive online while presenting very different insurance, flood, maintenance, or rental considerations in person.

Home-buying due diligence with keys, inspection materials, and insurance documents

What sellers and investors should watch

Sellers

Today’s buyers have alternatives, and pricing based on a neighbor’s optimistic list price can lead to extended market time.

Sellers should price against recent comparable sales in the same neighborhood and property category. Waterfront sellers should clearly explain the access route, bridge clearance, seawall condition, dock, lift, and insurance profile. A listing described only as “waterfront” may leave buyers with unanswered questions.

High-impact repairs, complete documentation, strong photography, and realistic pricing can help a property stand out.

Investors

Investors should underwrite conservatively. With Lee County rents reportedly down approximately 9% year over year and mortgage rates near 7%, projected returns should not depend on aggressive rent growth or immediate appreciation.

A complete analysis should include:

  • Realistic rent and vacancy
  • Insurance and flood coverage
  • Property management
  • Taxes and HOA fees
  • Repairs and capital reserves
  • Pool, seawall, dock, or lift maintenance
  • Financing costs
  • Rental restrictions
  • Resale liquidity

A less expensive condominium may offer a lower entry point, but association assessments or rental rules can affect returns. A waterfront home may have strong lifestyle and rental appeal, but its maintenance and insurance costs must be modeled carefully.

The September 14 takeaway

The Cape Coral and Fort Myers market is active, but selective. Sales are improving across Southwest Florida, while real prices remain softer than a year ago. Inventory has tightened in some segments, but buyers still have negotiating room when a property is overpriced, outdated, or burdened by high insurance and association costs.

Cape Coral buyers should distinguish carefully between freshwater canals, bridge-restricted Gulf access, and direct sailboat access. Fort Myers buyers should separate single-family homes from condominiums and evaluate the complete cost of ownership.

Whether you are researching cape coral real estate agents, comparing realtors cape coral buyers and sellers can work with, or tracking the latest Fort Myers real estate trends, the most useful market information is specific to the property and neighborhood.

You can search available Southwest Florida properties, learn more about RE/MAX Realty Team, or contact the office for property-specific guidance throughout Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding communities.

RE/MAX Realty Team office serving Cape Coral and Southwest Florida

Market figures are approximate and may vary by source, reporting period, property type, and geographic boundary. This article is for general informational purposes only and is not an appraisal, insurance quote, lending decision, or substitute for individualized real estate, legal, tax, insurance, or financial advice.

Read More
92VFnQSTNEJ
Uncategorized
September 14, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Daily market read for Sunday, September 13, 2026

Today’s Southwest Florida market conversation is less about broad headlines and more about the costs and characteristics that determine whether a specific property makes sense.

For buyers, insurance availability and waterfront access can change the monthly budget and long-term value of a home. For sellers, accurate pricing and clear property details are increasingly important. For investors, declining rents mean that conservative underwriting is essential.

Here is the latest hyper-local read for Cape Coral and Fort Myers.

Florida’s insurance market is showing signs of stabilization

Florida’s property insurance market remains an important part of every real estate decision, but conditions are improving compared with the uncertainty of recent years.

More than 17 private insurance carriers have re-entered or newly entered the Florida market, giving homeowners and buyers more options than they had during the tightest part of the insurance crisis. The Florida Office of Insurance Regulation has reported continued growth in the number of companies writing residential property policies.

Citizens Property Insurance has also approved an average rate reduction of approximately 8.7% for many policyholders in 2026. The exact change depends on the policy type, location, coverage, and individual risk profile, but the broader direction is positive.

You can review updates from the Florida Office of Insurance Regulation and Citizens’ rate information through Citizens Property Insurance.

Older roofs still require extra attention

A more stable insurance market does not mean every home is equally easy to insure.

Older homes, particularly those with aging roofs, may still face more detailed underwriting questions, inspection requirements, coverage limitations, or higher premiums. Buyers should not assume that a property is insurable simply because it is currently occupied or has an existing policy.

Before making an offer, ask for:

  • The roof’s installation date and permitting records
  • Recent four-point or roof inspections
  • Wind mitigation documentation
  • Information about prior claims
  • Current insurance declarations, when available
  • Estimates for replacement cost and wind coverage

Carriers are increasingly willing to consider older roofs when their condition and construction can be documented. However, roof age remains a major factor in both insurability and negotiations.

Wind mitigation inspections can deliver meaningful savings

A wind mitigation inspection is often one of the most cost-effective steps a Florida homeowner can take to reduce insurance costs. The inspection documents features such as:

  • Roof shape and construction
  • Roof-to-wall connections
  • Roof deck attachment
  • Secondary water resistance
  • Hurricane-resistant windows and doors
  • Shutters and garage-door protection

Depending on the home and carrier, qualifying features may generate significant credits on the wind portion of the policy. Buyers should ask whether a current inspection is available, while sellers may benefit from completing one before listing.

A relatively modest inspection cost can make a home easier to evaluate, improve buyer confidence, and potentially reduce the total insurance premium.

Southwest Florida home inspection focused on roof and hurricane-readiness features

Cape Coral waterfront pricing depends on the access tier

Cape Coral waterfront properties are not one uniform category. A freshwater canal, a Gulf-access canal with bridges, and direct Gulf access can attract different buyers and command very different prices.

Based on July–August 2026 market data, approximate median prices are:

Waterfront category Approximate median price
Freshwater canal $465,000
Gulf access with bridges $615,000
Direct Gulf access, no bridges $692,500

These figures help explain why a simple “waterfront” label is not enough when comparing Cape Coral homes.

Freshwater canal homes

Freshwater canal properties often appeal to buyers who want a water view, private dock, kayaking, fishing, or a larger outdoor setting without paying the full premium for Gulf access.

The key questions are usability and condition. Buyers should confirm the canal’s width and depth, the condition of the seawall, dock, and boat lift, and whether the waterway connects to other canals or recreational areas.

Freshwater access may offer excellent lifestyle value, but it should not be priced like a direct Gulf-access property.

Gulf access with bridges

Gulf-access homes with bridges can provide a boating lifestyle while remaining more affordable than direct-access properties. However, the route to open water may be affected by bridge clearance, tides, canal conditions, and the size of the buyer’s boat.

During due diligence, buyers should ask:

  • How many bridges are on the route to open water?
  • What are the bridge clearances?
  • Is the route navigable at typical tide levels?
  • How long is the trip to the river or Gulf?
  • Are there locks, restrictions, or maintenance concerns?

The answers can affect both enjoyment and resale appeal.

Direct Gulf access

Direct Gulf-access properties, particularly those with no bridges between the home and open water, generally command the highest waterfront premium. They may be especially attractive to boaters who want faster access and fewer route limitations.

That premium should still be evaluated against the full ownership picture. Seawalls, docks, boat lifts, electrical systems, flood exposure, storm damage history, and insurance costs can materially affect the value of a waterfront property.

Cape Coral waterfront inventory is down year over year, with approximately 4.9 months of supply in this segment. That is roughly balanced rather than extremely tight. Well-priced, move-in-ready homes can sell efficiently, while properties with aging marine infrastructure or unrealistic list prices may give buyers meaningful negotiating leverage.

Cape Coral canal-front home with private dock and boat lift

Overall inventory still gives buyers room to negotiate

Cape Coral’s overall market has approximately 7 to 8 months of supply, which favors buyers. The waterfront segment is tighter than the broader citywide market, but buyers still have options and time to compare condition, access, insurance, and price.

Current citywide benchmarks remain approximately:

  • Cape Coral: $349,900 median sale price and about 99 days on market
  • Fort Myers: $325,000 median sale price and about 100 days on market

These are broad figures. A renovated home with a newer roof, manageable insurance, and a desirable location may perform very differently from an outdated property with deferred maintenance.

For buyers, longer marketing periods create opportunities to negotiate repairs, credits, price adjustments, or favorable terms. For sellers, the message is straightforward: accurate pricing and preparation matter more than simply testing the highest possible list price.

Lee County investors should underwrite conservatively

Lee County rents have declined, making it more important for investors to use realistic income assumptions. A property that appeared attractive when rents were rising may produce a very different return today.

Investors should stress-test each purchase using:

  • Conservative market rent
  • Vacancy and turnover
  • Property management
  • Insurance increases
  • Property taxes
  • Repairs and maintenance
  • HOA or condominium fees
  • Flood coverage, when applicable
  • Financing costs
  • Future capital expenditures

For a Cape Coral waterfront rental, that analysis should also include seawall, dock, lift, pool, and exterior maintenance. For a Fort Myers condominium, association reserves, master insurance, assessments, rental rules, and building condition deserve close review.

The best investment is not necessarily the property with the lowest purchase price. It is the property whose income, expenses, tenant demand, and resale prospects remain reasonable under conservative assumptions.

Well-maintained Cape Coral rental home with tropical landscaping in bright natural light

Practical guidance for today’s market

For buyers

Get an insurance estimate before making an offer, especially for older homes, waterfront properties, and homes with aging roofs. Verify the exact type of water access rather than relying on listing language. Review seawalls, docks, lifts, flood exposure, and permitting during due diligence.

For sellers

Gather roof records, wind mitigation reports, permits, insurance information, and marine-infrastructure documentation before listing. Price the property against comparable homes with similar access and condition. Clear information can reduce buyer uncertainty and help prevent renegotiation later.

For investors

Use current rents rather than optimistic projections. Include vacancy, insurance, maintenance, management, and capital expenses in the first version of your analysis: not as an afterthought. If the deal only works with perfect occupancy or aggressive rent growth, it may not be sufficiently durable.

Search Southwest Florida properties with local guidance

RE/MAX Realty Team serves buyers, sellers, renters, and investors throughout Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding communities.

  • Search SWFL properties
  • Learn more about RE/MAX Realty Team
  • Contact our office

Summary and takeaway

The September 13, 2026 market is being shaped by property-level details.

Florida’s insurance landscape is stabilizing, with more private carriers returning, an approximately 8.7% Citizens rate reduction, and increased attention to wind mitigation. Older roofs still require careful review, but documented condition and storm-resistant features can improve a home’s insurance profile.

In Cape Coral, waterfront value depends heavily on access: approximately $465,000 for freshwater canal homes, $615,000 for Gulf access with bridges, and $692,500 for direct Gulf access. Inventory is tighter in the waterfront category, but buyers retain leverage when marine infrastructure is aging or pricing is unrealistic.

Across Cape Coral and Fort Myers, longer marketing periods give buyers room to compare and negotiate. Investors should remain cautious because Lee County rents have declined.

The best real estate decisions today come from evaluating the complete ownership picture: price, insurance, condition, access, monthly costs, and long-term usability.

Data disclaimer: All figures in this article are approximate and may vary by source, property type, geographic boundary, and reporting period. Cape Coral waterfront figures reflect July–August 2026 market data, while citywide prices, days on market, inventory, insurance conditions, and rent trends reflect the latest available information as of September 13, 2026. This article is for general informational purposes only and is not financial, legal, tax, insurance, or investment advice. Consult qualified professionals before making a real estate decision.

Read More
R2clqscSl2j
Uncategorized
September 12, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Daily market read for Saturday, September 12, 2026

Southwest Florida’s housing market is becoming more active, but the recovery is not uniform across every city, neighborhood, or property type. Buyers are returning, sellers are adjusting expectations, and the details of a property: water access, insurance, HOA fees, condition, and location: matter more than a broad regional headline.

For today’s hyper-local read, Cape Coral’s median home sale price is approximately $349,900, with homes spending about 99 days on the market. Fort Myers is showing a median sale price near $325,000, with approximately 100 days on the market.

Those figures provide useful context, but they do not tell the whole story. A freshwater canal home in Cape Coral, a direct Gulf-access property, a downtown Fort Myers condominium, and a home in a golf community may all respond to different market forces.

The broader Southwest Florida market

The latest regional benchmark comes from the FGCU Regional Economic Research Institute’s Third Quarter 2026 Real Estate Report, published September 8 and based primarily on second-quarter data.

The report shows a market with improving sales activity but softer real prices:

  • Single-family home sales increased 14% year over year, reaching approximately 5,600 sales across the three-county coastal region.
  • Condominium sales increased 17%, reaching approximately 1,320 sales.
  • Real median single-family prices declined about 4% year over year.
  • Real median condominium prices declined about 8% year over year.
  • Lee County’s Housing Affordability Index was approximately 1.35 for all residential properties and 1.30 for single-family homes.
  • Real median rents in Lee County declined approximately 9% year over year.

An affordability index above 1.0 generally indicates that the benchmark household has enough income to qualify for the typical home under the report’s assumptions. However, the actual monthly cost of ownership still depends on mortgage terms, insurance, taxes, flood coverage, HOA or condominium fees, and maintenance.

The overall message is not that the market is collapsing. It is that Southwest Florida is moving through a reset: more transactions are taking place, while buyers remain selective and inflation-adjusted prices are softer than they were a year ago.

Cape Coral: the waterfront category matters

Cape Coral’s approximately $349,900 median sale price and 99-day marketing period suggest a market where buyers have time to compare options. But Cape Coral is not one single market. Waterfront access can create substantial differences in value, usability, insurance, and buyer demand.

Waterfront homes and canal access in Cape Coral

Freshwater canals

Freshwater canal homes are often attractive to buyers who want water views, a dock, kayaking, fishing, or a more open backyard setting without paying the premium associated with Gulf access.

These properties can offer a compelling lifestyle value, but buyers should understand that freshwater canal access is not the same as navigable access to the Gulf. The canal’s width, depth, seawall condition, and connection to the broader canal system all deserve review.

Gulf access with bridges

Some Cape Coral homes offer saltwater or Gulf access but require travel beneath bridges. This can be perfectly suitable for many boaters, particularly those using smaller vessels. However, bridge height and timing can affect the type of boat that can reach the property and how easily an owner can access open water.

When comparing two homes that are both advertised as “Gulf access,” buyers should ask:

  • How many bridges are between the property and open water?
  • What are the bridge clearances?
  • Is the route navigable at typical tide levels?
  • How long does the boat trip take?
  • Are there restrictions related to canals, locks, or neighboring structures?

Direct Gulf access

Direct Gulf-access properties, including some sailboat-access locations, often command a premium because they reduce travel time and may accommodate larger boats. But the premium should be evaluated against the entire ownership profile.

Buyers should examine the dock, seawall, lift, electrical systems, storm exposure, flood zone, elevation, and insurance availability. A waterfront feature can increase enjoyment and resale appeal, but it can also add significant maintenance and replacement costs.

Cape Coral’s current market rewards buyers who distinguish between these waterfront tiers rather than relying on a listing description alone. Sellers, meanwhile, need to explain the access clearly and price the property according to comparable homes with similar boating characteristics.

Fort Myers: single-family homes and condos are different markets

Fort Myers’ median sale price near $325,000, combined with approximately 100 days on market, reflects a diverse housing landscape. The city includes established single-family neighborhoods, townhomes, condominium communities, gated developments, golf properties, and homes near downtown, medical services, shopping, and employment centers.

The most important distinction is often between single-family homes and condominiums.

Single-family buyers typically focus on lot size, roof age, storm protection, renovation needs, insurance, and proximity to services. In Fort Myers, a modest home in an established neighborhood can appeal to a full-time resident, retiree, or investor seeking fewer community restrictions.

Condominium buyers must look beyond the purchase price. Monthly association fees, reserves, building maintenance, master insurance, assessments, rental rules, pet policies, and approval procedures can materially change the total cost of ownership. The FGCU report’s approximately 8% year-over-year decline in real median condo prices may create opportunities, but buyers should complete careful association-level due diligence.

Established Fort Myers neighborhood with single-family and condominium homes

Neighborhood-level differences to watch

Yacht Club area

The Yacht Club area is appealing to buyers who value proximity to the Caloosahatchee River, waterfront recreation, and established Fort Myers amenities. Properties near the river may receive additional buyer interest, but flood exposure, insurance, seawall condition, and storm-related improvements should be evaluated carefully.

The neighborhood’s location can support lifestyle appeal, yet buyers should compare the cost of ownership against nearby homes that may offer similar access without the same waterfront-related expenses.

Cape Harbour

Cape Harbour represents a distinct Cape Coral lifestyle, with marina-oriented amenities, waterfront dining, and a more defined destination feel than many residential canal areas. Condominiums, attached homes, and nearby single-family properties may attract buyers looking for boating access and walkable entertainment.

Values can vary considerably depending on the view, marina relationship, building, association fees, rental policies, and proximity to amenities. For investors, projected rental income should be tested against current rents, management costs, insurance, vacancy, and association rules.

Downtown Fort Myers

Downtown Fort Myers attracts buyers who prioritize restaurants, cultural events, historic character, and a more walkable environment. The housing mix includes condominiums, loft-style residences, historic homes, and nearby single-family properties.

Downtown properties may have a different resale audience from suburban homes. Some buyers are paying for lifestyle and location rather than a large yard or extensive square footage. Parking, building reserves, association fees, flood considerations, and rental restrictions are especially important when evaluating a downtown condominium.

Golf communities

Golf communities throughout Cape Coral and Fort Myers can appeal to seasonal residents, retirees, and buyers seeking organized amenities. However, golf ownership costs vary. Some communities have mandatory memberships, while others operate with optional or social memberships. HOA fees, club dues, capital reserves, course maintenance, and rental restrictions should be reviewed before making an offer.

A lower purchase price does not automatically mean a lower monthly cost. Buyers should compare the full carrying cost of a golf-community home with similar properties outside the community.

Mortgage rates remain part of the equation

Freddie Mac’s weekly mortgage data place average 30-year fixed mortgage rates near 6.7% to 6.8%. At those rates, even modest differences in purchase price, insurance, taxes, and HOA fees can have a meaningful effect on the monthly payment.

Buyers should obtain a current preapproval, compare loan programs, and ask lenders to estimate the full payment: not just principal and interest. It is also wise to request insurance estimates early, particularly for older homes, waterfront properties, condominiums, and homes with prior storm damage or aging roofs.

The right question is not simply, “Can I qualify for this home?” It is, “Does the complete monthly cost fit comfortably within my long-term plan?”

What today’s market means for buyers, sellers, and investors

Buyers

Use longer marketing times to compare properties and negotiate thoughtfully. Review recent closed sales from the same neighborhood and property type. In Cape Coral, compare waterfront access in detail. In Fort Myers, compare single-family homes with condos only after accounting for all recurring fees and maintenance responsibilities.

Sellers

Pricing must reflect current buyer behavior rather than past peak-market expectations. A well-presented home with accurate pricing, clear disclosures, and realistic insurance information can stand out. Properties that are overpriced or unclear about waterfront access, association costs, or condition may remain on the market considerably longer.

Investors

Lee County rents are down approximately 9% year over year, so investment projections should remain conservative. Underwrite using realistic rent, vacancy, insurance, maintenance, taxes, financing, and management costs. The best investment is not necessarily the least expensive property; it is the one with a sustainable relationship between purchase price, operating expenses, tenant demand, and resale potential.

RE/MAX Realty Team serves Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding Southwest Florida communities. Buyers, sellers, and investors can search available SWFL properties, learn more about the team, or contact RE/MAX Realty Team for property-specific guidance.

RE/MAX Realty Team office serving Southwest Florida

Summary and takeaway

The September 12, 2026 market is active but selective. Cape Coral’s median sale price is approximately $349,900, with homes taking about 99 days to sell. Fort Myers is near $325,000, with approximately 100 days on market. Regional sales are rising, real prices are softer, Lee County affordability has improved, and rents have declined.

Cape Coral buyers should focus closely on the difference between freshwater canals, Gulf access with bridges, and direct Gulf access. Fort Myers buyers should separate the single-family and condominium markets and review total ownership costs. Neighborhoods such as Yacht Club, Cape Harbour, downtown Fort Myers, and golf communities each bring their own pricing and lifestyle considerations.

The best decision will come from understanding the specific property, neighborhood, insurance profile, and financial plan: not from relying on one broad median.

Data disclaimer: Market conditions change frequently, and the figures in this article are approximate. Cape Coral and Fort Myers statistics may vary by source, property type, geographic boundary, and reporting period. The FGCU figures primarily reflect regional second-quarter 2026 data, while the local median prices and days-on-market estimates reflect the latest available market read as of September 12, 2026. This article is for general informational purposes and is not financial, legal, tax, insurance, or investment advice. Consult qualified professionals before making a real estate decision.

Read More
rNR6H1lPJa8-740×480
Uncategorized
September 11, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Daily market read for September 11, 2026

Southwest Florida’s real estate market is active, but it is not moving uniformly. Cape Coral waterfront homes, downtown Fort Myers condos, golf communities, and traditional single-family neighborhoods are each responding to different levels of inventory, pricing, insurance costs, and buyer demand.

The latest regional data points to a market that is stabilizing rather than surging. Sales are improving, inventory has tightened in several segments, and prices are generally softer than during the market’s peak. However, well-priced homes in desirable locations can still attract serious attention: especially when they offer strong condition, manageable insurance costs, and features buyers cannot easily replace.

Here is the hyper-local Cape Coral market update 2026 buyers, sellers, and investors need to know.

The Southwest Florida market at a glance

The latest available reports show a market with more transactions but less pricing power for sellers than in recent boom years.

According to the latest Realtor.com Cape Coral–Fort Myers market report, the combined market recorded:

  • A median list price near $380,000
  • Approximately 95 days on market
  • Median asking prices down roughly 6.2% year over year
  • Nearly one in five listings with a price reduction
  • Active listings down year over year, even as new listings edged higher

The FGCU Regional Economic Research Institute adds important context. In its latest regional report, single-family sales increased approximately 14% year over year, while the real median single-family price declined about 4%. Condo sales also increased, but median condo prices fell more sharply.

That combination: more sales alongside softer prices: suggests buyers are returning, but they remain selective and price-conscious.

Mortgage rates are still part of the equation. Freddie Mac reported a 30-year fixed average of 6.76% for the week ending September 10, 2026, up from 6.71% the previous week. At this rate, insurance, taxes, HOA fees, and flood coverage can materially change a buyer’s monthly payment.

Cape Coral: the citywide numbers do not tell the whole story

Cape Coral remains one of the most varied real estate markets in Southwest Florida. A home in northern Cape Coral without water access is competing in a very different market from a renovated sailboat-access property in the Yacht Club area or a newer home near Cape Harbour.

Current Cape Coral indicators show:

  • Median sale prices generally in the mid-$300,000s
  • Median list prices closer to the low-to-mid $400,000s
  • Typical market times around 85 to 100 days, depending on the data source and property type
  • Approximately 4.5 to 4.9 months of supply
  • Fewer listings than last year in several segments

The gap between list price and sold price is especially important. A property listed at $425,000 is not automatically worth $425,000. Buyers are comparing recent closed sales, insurance estimates, inspection findings, seawall condition, and total monthly ownership costs before making offers.

The strongest demand continues to center on properties with:

  • Newer roofs and updated major systems
  • Pools and usable outdoor living areas
  • Reasonable insurance profiles
  • Completed renovations with permits
  • Larger lots or attractive canal exposure
  • Convenient access to shopping, dining, schools, and major roads

Cape Coral canal homes and waterfront properties in bright natural light

Cape Coral waterfront: access matters more than the label

“Waterfront” is not one category in Cape Coral. The value of a canal home depends heavily on how the property connects to open water and what ownership costs come with that access.

Approximate current pricing tiers include:

Property type Approximate market range
Freshwater canal homes Mid-$400,000s and up
Gulf-access homes with bridge restrictions Approximately $600,000–$650,000
Direct Gulf or sailboat access Approximately $700,000–$755,000 and up
Premium riverfront or extensively upgraded properties $1 million or more

These are broad ranges, not appraisals. A canal’s width, bridge clearance, lock system, seawall age, dock, lift, boating route, and proximity to the Caloosahatchee River can significantly affect value.

Yacht Club area

The historic Yacht Club area and surrounding 33904 properties benefit from established neighborhoods and desirable access to the river and Gulf. However, many homes are older, and buyers are paying close attention to renovation quality, storm history, roofs, electrical systems, seawalls, and flood insurance.

A renovated direct-access home can command a substantial premium. An older property requiring major work may need a significant adjustment, even if the location is attractive.

Cape Harbour

Cape Harbour remains a premium lifestyle location because of its marina, waterfront setting, restaurants, and community atmosphere. Recent neighborhood-level listing data placed its median list price near $509,000, although individual properties vary widely.

Buyers should separate marina or lifestyle appeal from actual boating access. They should also verify rental rules, dock rights, association fees, and any restrictions affecting future use.

Pelican

Pelican includes a mix of off-water, canal-front, and Gulf-access homes. Recent listing data placed the neighborhood’s median near $535,000, but the range is broad. Updated Gulf-access homes can sit well above the neighborhood median, while inland properties may trade closer to the broader Cape Coral market.

For both buyers and sellers, the most relevant comparable sales are usually within the same waterfront tier: not simply within the same ZIP code.

Fort Myers: single-family homes and condos are moving differently

Fort Myers is more segmented than a citywide median suggests. The area includes downtown condos, established neighborhoods, gated golf communities, older single-family homes, townhomes, and newer construction near major roads and employment centers.

Recent local market reporting places Fort Myers single-family median sale prices roughly in the $430,000–$445,000 range, with approximately 4.3 to 4.5 months of supply. One local snapshot showed median days on market near 50 days for single-family homes, although broader Fort Myers and metro statistics are closer to 90–100 days depending on the reporting method.

Condos are generally more buyer-friendly. Median prices have been reported around $220,000–$233,000, with approximately 6.5 to 6.9 months of supply in some segments.

Established Fort Myers neighborhood with mature landscaping and well-maintained homes

Downtown Fort Myers and riverfront condos

Downtown Fort Myers attracts buyers who prioritize restaurants, entertainment, river views, walkability, and proximity to the historic river district. Condo pricing is often more accessible than waterfront single-family pricing, but monthly carrying costs can vary considerably.

Before purchasing a downtown or riverfront condo, review:

  • Association reserves and financial statements
  • Current and potential special assessments
  • Master insurance and individual unit coverage
  • Roof and building maintenance
  • Rental restrictions
  • Pet and occupancy rules
  • Flood exposure and deductibles
  • Parking and storage arrangements

A lower purchase price does not always mean a lower monthly cost. HOA fees, insurance, taxes, and assessments need to be included in the affordability calculation.

Golf and gated communities

Golf communities such as Heritage Palms and other established Fort Myers developments continue to appeal to seasonal residents, retirees, and lifestyle buyers. Buyers are comparing more than the home itself. They are also evaluating club fees, membership requirements, food and beverage minimums, rental rules, reserves, and future assessments.

Well-maintained homes with reasonable fees can attract attention. Properties with dated interiors, high monthly costs, or unclear association finances may require more time and sharper pricing.

What the current market means for buyers

Buyers have more negotiating room than they did during the fastest years of the market, but the best properties may still move quickly.

If you are shopping in Cape Coral or Fort Myers:

  1. Get fully pre-approved before making serious offers.
  2. Compare recent closed sales, not just active listings.
  3. Request insurance estimates early.
  4. Investigate roofs, permits, seawalls, docks, lifts, and storm repairs.
  5. Review HOA or condo documents before the inspection period expires.
  6. Calculate the complete monthly payment.
  7. Pay attention to cumulative days on market and repeated price reductions.

For waterfront buyers, ask specifically about travel time to open water, bridge height restrictions, seawall permits, flood insurance, and dock condition. For Fort Myers condo buyers, association finances may be just as important as the unit’s finishes.

Home-buying due diligence with keys, inspection materials, and insurance documents

What sellers should do now

Today’s buyers are informed and have alternatives. Pricing based on a neighbor’s ambitious asking price: or on a sale from several years ago: can lead to extended market time.

Sellers should:

  • Price against recent comparable sales in the same neighborhood and property type
  • Complete high-impact repairs before listing
  • Gather roof, permit, insurance, and renovation records
  • Present pools, outdoor areas, docks, and canal access clearly
  • Explain bridge clearance and boating routes
  • Review showing activity during the first two weeks
  • Be prepared to respond to market feedback

In waterfront neighborhoods, presentation must communicate the property’s practical advantages. “Waterfront” is not enough. Buyers want to know whether the access is useful, whether the seawall is sound, and whether the insurance profile is manageable.

What investors should watch

Investors should underwrite Cape Coral and Fort Myers properties conservatively. Lee County rents have declined approximately 9% year over year in recent regional reporting, while mortgage rates remain near 7%.

A complete investment analysis should include:

  • Realistic rent and vacancy
  • Property management
  • Insurance and flood coverage
  • Property taxes
  • HOA or condo fees
  • Repairs and capital reserves
  • Pool, seawall, dock, or lift maintenance
  • Financing costs
  • Rental restrictions
  • Resale liquidity

A lower-priced condo may offer an attractive entry point, but association restrictions or assessments can affect returns. A waterfront home may have strong rental and lifestyle appeal, but seawall, storm, insurance, and maintenance expenses must be modeled carefully.

The September 11 takeaway

The Cape Coral and Fort Myers market is active, but selective. Regional sales are improving, inventory has tightened in important segments, and prices are generally stabilizing after a period of correction. At the same time, buyers still have time to investigate properties and negotiate: particularly when a home is overpriced, outdated, or burdened by high insurance and association costs.

Cape Coral offers the greatest range of waterfront possibilities, from freshwater canals to direct Gulf access. Fort Myers provides a broader mix of established neighborhoods, golf communities, downtown condos, and single-family homes near employment and amenities.

The most important lesson is simple: the citywide median is only the starting point. Neighborhood, access, property condition, insurance, HOA costs, and financing will determine the real opportunity.

Whether you are comparing Cape Coral real estate agents, searching for experienced Realtors Cape Coral buyers and sellers can rely on, or evaluating current Fort Myers real estate trends, local guidance matters. Search available Southwest Florida properties, learn more about RE/MAX Realty Team, or contact our office for help with your next move.

RE/MAX Realty Team office in Cape Coral

Market figures are approximate and may vary by source, reporting period, property type, and geographic boundaries. This article is for general informational purposes only and is not an appraisal, insurance quote, lending decision, or substitute for individualized real estate, legal, tax, insurance, or financial advice.

Read More
lQH58gFo8OT-740×480-1-740×480-2-740×480-1-740×480
Uncategorized
September 11, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Weekly market pulse for Friday, September 11, 2026

Southwest Florida’s housing market is giving buyers more room to evaluate their options, while well-positioned homes still attract serious attention. Sales activity is improving, prices have softened from recent highs, and the cost of borrowing remains an important part of every buyer’s decision.

Here is the latest hyper-local look at Cape Coral and Fort Myers real estate, including ZIP-level pricing, waterfront premiums, neighborhood comparisons, mortgage rates, and the upcoming Federal Reserve meeting.

Mortgage rates rose slightly this week

According to Freddie Mac’s Primary Mortgage Market Survey, the average 30-year fixed mortgage rate was 6.76% on September 10, 2026, up from 6.71% the previous week and 6.35% a year ago.

The average 15-year fixed rate was 6.09%, up from 6.04% last week and 5.50% a year ago. The 30-year fixed rate’s 52-week range is currently 5.98% to 6.76%.

The increase is modest, but affordability math still matters. On a $400,000 loan, the principal-and-interest payment at 6.76% is approximately $2,600 per month before taxes, insurance, HOA fees, and other costs. A small rate change may not determine whether a buyer qualifies, but it can affect the comfortable purchase price and monthly budget.

The practical approach is to compare multiple lenders, understand the full monthly payment, and avoid assuming rates will automatically fall after the next Federal Reserve meeting.

What to watch during the September FOMC meeting

The Federal Open Market Committee is scheduled to meet September 15–16, 2026.

Buyers should not assume that a Federal Reserve announcement will immediately produce lower mortgage rates. The Fed influences short-term interest-rate policy, while 30-year mortgage rates are also heavily affected by bond markets, inflation expectations, economic data, and investor demand.

Even if the FOMC changes policy, mortgage rates could move higher, lower, or remain relatively steady depending on how markets interpret the announcement. Sellers should also avoid pricing a home around an expected rate change. Current comparable sales, condition, location, insurance costs, and buyer demand remain more reliable pricing indicators.

Southwest Florida market direction: more sales, softer real prices

The FGCU Regional Economic Research Institute’s Third Quarter 2026 SWFL Real Estate Report, released September 8, provides important regional context from the second quarter.

Across Southwest Florida:

  • Single-family home sales increased 14% year over year to approximately 5,600.
  • Condominium sales rose 17% to approximately 1,320.
  • Real median single-family prices declined 4% compared with Q2 2025.
  • Real median condominium prices declined 8% year over year.
  • Lee County’s Housing Affordability Index was 1.35 for all residential properties and 1.30 for single-family homes.
  • Real median rents in Lee County declined approximately 9% year over year.

In simple terms, more properties are changing hands even as prices remain below prior peaks. That combination can create opportunities for buyers who are prepared, while sellers need realistic pricing and strong presentation.

Lee County’s July and August market context

Lee County recorded approximately 1,762 closed residential sales in July 2026. Single-family inventory was around 5.5 months, while condo and townhome supply was approximately 6.9 months.

The median time to contract was about:

  • 73 days for single-family homes
  • 112 days for condominiums

Homes sold for roughly 93% of asking price, depending on the report and whether the metric uses original or final list price. Approximately 22% of listings had experienced price reductions, reinforcing the importance of launch pricing and ongoing market feedback.

This is not a market where every property sells immediately. However, it is also not a market without demand. Buyers have more opportunities to negotiate, particularly when a property has been sitting, needs repairs, carries high insurance costs, or is priced above comparable sales.

Cape Coral ZIP-level snapshot

Cape Coral waterfront home and canal in bright natural light

Cape Coral remains highly segmented. A canal-front home, a newer inland home, and a property near the river can have very different values even within the same ZIP code.

Approximate 2026 snapshots include:

Cape Coral ZIP Approximate median sale price Typical market time
33904 Around $375,000 Approximately 52–81 days, depending on source
33914 Roughly $421,000–$495,000 Highly variable by property type and location
33991 Around $389,900 Approximately 102–161 days in some reporting periods
33993 Around $445,000 Approximately 86 days

Citywide Cape Coral median sale prices are approximately $352,000–$355,000, while median list prices are closer to $414,000–$425,000. The gap between list and sale prices shows why buyers should analyze closed sales rather than relying only on active listings.

Water access creates another layer of pricing:

  • Freshwater canal homes: generally mid-$400,000s and up
  • Gulf-access homes with bridge restrictions: approximately $600,000–$650,000
  • Sailboat or direct-access properties: approximately $700,000–$755,000 and higher
  • Premium riverfront, wide-basin, or extensively upgraded homes: often $1 million or more

For buyers seeking SWFL waterfront homes, boating access is only part of the analysis. Bridge clearance, canal depth, tides, seawall condition, dock permits, boat lift capacity, and travel time to open water can materially affect value.

Fort Myers real estate trends by area

Fort Myers neighborhood near the Caloosahatchee River with palms and condominium buildings

Fort Myers citywide median sold prices are approximately $319,900–$329,000, depending on the reporting period and property mix. The city offers a wider range of housing styles and price points than many buyers realize.

  • Gateway: Master-planned homes commonly range from approximately $400,000 to $700,000, depending on size, updates, amenities, and location within the community.
  • McGregor corridor: Many homes fall in the mid-$400,000s to more than $2 million, with river proximity, mature landscaping, lot size, and renovations driving the spread.
  • San Carlos Park: A practical option for buyers seeking homes without mandatory HOA fees, with many properties typically priced around $300,000–$500,000.
  • Downtown riverfront condos: Established buildings often range from $400,000–$800,000, while newer luxury construction can exceed $900,000.

Fort Myers tends to offer more established neighborhoods, mature trees, proximity to downtown amenities, and a broader selection of condos. Cape Coral offers a larger supply of single-family homes, canals, boating access, and newer construction in many areas.

Cape Coral vs. Fort Myers: which fits your goals?

Consideration Cape Coral Fort Myers
Typical citywide pricing Approximately $352,000–$355,000 median sale price Approximately $319,900–$329,000
Strongest lifestyle appeal Canal living, boating, newer residential areas Downtown, established neighborhoods, riverfront, cultural amenities
Waterfront options Freshwater, gulf-access, sailboat-access, riverfront Riverfront homes and condos, McGregor corridor
Condo options Available, but single-family homes are prominent Broader selection of established and downtown condos
Buyer priorities Water access, lot, seawall, bridge restrictions Location, building condition, HOA, flood and insurance considerations

The right choice depends on how you plan to use the property. A boater may prioritize Cape Coral access, while a buyer who values walkability, downtown dining, or a condominium lifestyle may prefer Fort Myers.

Total-cost underwriting is essential

Purchase price is only one part of the decision in Southwest Florida. Buyers should review:

  • Roof age and remaining useful life
  • Flood zone and elevation
  • Wind mitigation features
  • Current homeowners and flood insurance estimates
  • Seawall, dock, lift, and pool condition
  • Electrical, plumbing, and HVAC age
  • Condo reserves, master insurance, pending assessments, and association budgets

For investors, Lee County’s approximately 9% decline in real median rents is also important. A property that looked attractive using older rent assumptions may produce a different return today.

For sellers, these same details influence buyer confidence. Documentation of roof work, mitigation improvements, seawall repairs, permits, and insurance history can help reduce uncertainty during negotiations.

How local guidance can help

Whether you are comparing Cape Coral waterfront homes, evaluating a Fort Myers condo, preparing to sell, or looking for a rental investment, hyper-local advice matters. A neighborhood-level pricing strategy is more useful than a broad city average.

Search available Southwest Florida properties or contact RE/MAX Realty Team to connect with a local professional. With more than 100 agents serving Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding areas, our team can help you evaluate the numbers and the property-specific details behind them.

Closing takeaway

The September 2026 market is best described as active but selective. Sales are improving, real prices have softened, and buyers have more negotiating leverage than they did during the most competitive years. At the same time, mortgage rates near 6.76%, insurance expenses, waterfront maintenance, and condo financials can significantly change the total cost of ownership.

The best strategy is to focus less on headlines and more on the specific property, neighborhood, financing plan, and long-term goal.

Figures are approximate and may vary by source, property type, geography, and reporting period. This article is for general informational purposes only and is not an appraisal or insurance, lending, legal, or tax advice.

Read More
lQH58gFo8OT-740×480-1-740×480-2-740×480
Uncategorized
September 10, 2026by Penny

Hyper-local Cape Coral & Fort Myers Real Estate Insights

Market pulse for the week of September 9–10, 2026

Southwest Florida’s housing market is becoming more active, but that does not mean every city, neighborhood, or property type is moving in the same direction.

The latest data show more transactions, softer median prices, improving affordability, and lower rents across Lee County. At the same time, buyers and sellers are facing a more complicated decision-making environment shaped by insurance costs, mortgage rates, waterfront access, property condition, and neighborhood-level supply.

For anyone following the Cape Coral market update 2026, comparing Cape Coral with Fort Myers, or considering SWFL waterfront homes, the most important takeaway is simple: broad regional statistics are useful, but hyper-local analysis matters more than ever.

Southwest Florida market snapshot

The FGCU Regional Economic Research Institute’s Southwest Florida Real Estate Third Quarter 2026 Report, released September 8, provides the latest regional context using second-quarter data:

  • Single-family home sales increased 14% year over year to approximately 5,600 sales.
  • Condo sales increased 17% to approximately 1,320 sales.
  • The real median single-family price declined 4% compared with Q2 2025.
  • The real median condo price declined 8% year over year.
  • Lee County’s Housing Affordability Index measured 1.35 for all residential properties and 1.30 for single-family homes.
  • Lee County rents declined approximately 9% year over year.

The combination of rising sales and falling median prices suggests a market where buyers are returning, but sellers no longer have the same pricing power seen during the peak years. More homes are changing hands, yet purchasers remain selective and negotiation is still a meaningful part of many transactions.

An affordability index above 1 generally indicates that the benchmark household has enough income to qualify for the typical home under the report’s assumptions. However, actual affordability still depends on the buyer’s down payment, credit profile, insurance premium, taxes, HOA fees, flood coverage, and financing terms.

For more regional research, buyers and investors can review the FGCU RERI real estate research.

Cape Coral: larger inventory, stronger waterfront distinctions

Cape Coral continues to offer one of the broadest selections of homes, canals, lots, and waterfront properties in Lee County. Current market indicators place the median sale price at approximately $352,000 to $355,000.

The city’s numbers require some explanation because different data sets are tracking different portions of the market:

  • Approximately 873 active listings appear in one current market segment.
  • Broader inventory is estimated at approximately 2,090 active listings.
  • The median list price is near $425,000.
  • Typical days on market are around 95 to 100 days.

The difference between the median sale price and median list price is important. It indicates that sellers may need to account for negotiation, inspection findings, appraisal considerations, or price reductions before reaching the closing table. A home listed near $425,000 is not automatically worth that amount simply because it is in Cape Coral.

Cape Coral also cannot be evaluated as one uniform market. A newer inland home without a canal may appeal to a different buyer than an older property on a freshwater canal. Gulf-access waterfront homes, sailboat-access properties, homes near lock systems, and direct river-access locations all carry different premiums.

Waterfront buyers should evaluate:

  1. Type of water access: freshwater, saltwater, gulf access, river access, or sailboat access.
  2. Travel time to open water: canal distance and bridge restrictions can affect usability.
  3. Dock and seawall condition: these can represent significant ownership costs.
  4. Flood zone and elevation: both may affect insurance and financing.
  5. Roof, electrical, plumbing, and storm protection: condition matters heavily to insurers and lenders.
  6. Rental rules: not every neighborhood or HOA permits the same rental strategy.

Waterfront homes and canal access in Cape Coral and Southwest Florida

For buyers, Cape Coral’s longer marketing period creates room to compare properties and negotiate. For sellers, it makes accurate pricing, strong presentation, complete disclosures, and a clear explanation of waterfront features essential.

Fort Myers: a different mix and a different buyer profile

Fort Myers is showing a median sale price near $325,000, with approximately 337 active listings and about 381 homes sold in the latest reported period. Days on market are around 100 days.

Compared with Cape Coral, Fort Myers includes a more varied mix of established neighborhoods, condominiums, townhomes, gated communities, older single-family homes, new construction, and properties closer to employment centers, medical services, shopping, and downtown amenities.

That mix can produce very different results from one ZIP code or neighborhood to another. A condo near the river or downtown may respond to different factors than a suburban single-family home east of I-75. A home in a deed-restricted community may have different monthly costs and rental rules than a non-HOA property.

The city’s lower median sale price does not necessarily mean every Fort Myers property is more affordable than every Cape Coral property. Buyers should compare the full monthly cost, including:

  • Mortgage principal and interest
  • Homeowners or condo insurance
  • Flood insurance, when required or recommended
  • HOA or condominium fees
  • Property taxes
  • Maintenance and reserves
  • Utilities and storm-related improvements

Fort Myers may be especially attractive to buyers who prioritize access to established amenities, healthcare, employment, and a shorter commute over a larger lot or extensive canal system. Cape Coral may be a better fit for buyers seeking more space, pool homes, boating options, or a wider range of waterfront tiers.

Mortgage rates and the September Fed meeting

Freddie Mac reported an average 30-year fixed mortgage rate of 6.71% for the week ending September 3, 2026. The average 15-year fixed rate was approximately 6.04%.

The Federal Open Market Committee is scheduled to meet September 15–16. While the Federal Reserve does not directly set mortgage rates, its policy decisions and economic outlook can influence bond markets and consumer borrowing costs. Mortgage rates may move before, during, or after the meeting based on expectations: not simply on the final announcement.

At current rates, buyers should avoid making decisions based solely on the hope that rates will fall soon. A stronger strategy is to:

  • Obtain a current preapproval before touring seriously.
  • Compare multiple loan programs and lender fees.
  • Consider the payment impact of insurance and HOA costs.
  • Negotiate seller credits where appropriate.
  • Buy within a comfortable payment range rather than stretching to the maximum approval amount.
  • Revisit refinancing only if future savings justify the closing costs.

Insurance is part of the real estate decision

In Cape Coral and Fort Myers, insurance is not a secondary detail. It can affect whether a buyer qualifies for financing, whether a seller’s asking price is realistic, and whether an investment property produces acceptable cash flow.

Two similar homes can have very different insurance costs because of roof age, construction type, elevation, storm protection, flood zone, prior claims, and proximity to water. Waterfront properties may also require additional review of docks, seawalls, retaining structures, and exterior improvements.

Before making an offer, buyers should request insurance estimates early: not after the inspection period begins. Investors should underwrite the property using realistic insurance, vacancy, maintenance, management, taxes, and financing costs rather than relying only on projected rent.

With Lee County rents down approximately 9% year over year, investors should be especially cautious about assuming that rent growth will immediately offset higher borrowing or insurance expenses.

What buyers, sellers, and investors should do now

For buyers

Use the current market to improve your choices, not just to search for a discount. Compare recent closed sales within the same neighborhood and property type. In Cape Coral, pay close attention to waterfront tier and access. In Fort Myers, compare HOA costs, location, age, and property condition.

A home that has been on the market for 100 days may represent an opportunity: but it may also have insurance, condition, pricing, or location challenges that require closer investigation.

For sellers

Pricing based on what a neighbor hoped to receive: or what the market supported several years ago: can lead to extended market time. Buyers are comparing properties carefully, and listings with high insurance costs, outdated finishes, or unclear waterfront advantages may face additional resistance.

A successful listing strategy should include a current comparative market analysis, realistic pricing, professional presentation, transparent property details, and a plan for responding to early buyer feedback.

For investors

Focus on the entire operating picture. Lower rents and mortgage rates near 7% can narrow cash flow, while insurance and maintenance may vary considerably by property. Evaluate long-term rental demand, local restrictions, future capital expenses, and resale liquidity.

In both Cape Coral and Fort Myers, the best investment is not necessarily the least expensive property. It is the property with a sustainable relationship between purchase price, operating costs, location, tenant demand, and long-term maintenance.

Local guidance makes a difference

The current market rewards careful analysis. Whether you are looking for a canal-front home in Cape Coral, a condo in Fort Myers, a rental property, or a primary residence, neighborhood-level information is more useful than a single regional median.

RE/MAX Realty Team serves Cape Coral, Fort Myers, Sanibel, Fort Myers Beach, and surrounding communities with more than 100 real estate professionals across Southwest Florida. You can search available homes and properties, learn more about our team, or contact RE/MAX Realty Team for guidance tailored to your goals.

RE/MAX Realty Team office in Cape Coral

The takeaway

The September 2026 market is active but selective. Regional sales are rising, median prices are softer, affordability has improved, and rents in Lee County have declined. Cape Coral offers more variation in inventory and waterfront value, while Fort Myers provides a diverse mix of established neighborhoods, condos, townhomes, and single-family properties.

For buyers, preparation and property-level due diligence are essential. For sellers, accurate pricing and presentation matter. For investors, conservative underwriting is more important than optimistic projections.

The right move depends less on timing the entire Southwest Florida market and more on understanding the specific home, neighborhood, insurance profile, and financial strategy in front of you.

Read More
  • 1
  • 2
  • 3
  • 4
  • 5
  • 6

Exceptional Service. Local Expertise. Proven Results.

(239) 242-2000

Cape Coral Office
2326 Del Prado Blvd. S.
Cape Coral, FL 33990


Fort Myers Office
6611 Orion Dr. #104
Fort Myers, FL 33912

Quick Links

  • Company
  • Search Online
  • Sell With RE/MAX
  • Contact Our Office

Join Our Team

Build your real estate career with a collaborative, experienced team committed to helping agents grow, succeed, and reach their full potential.

© 2026 RE/MAX Realty Team. All Rights Reserved | Website By: OMG